What Is a Cash Advance? Card, Merchant and Trade Meanings
Cash advance meaning: credit card cash advances, merchant cash advances repaid from sales, and cash in advance in trade, with CFPB, Visa and ITA rules.
Article summary
TL;DR
A cash advance is money obtained in cash, or as an advance, before it is earned or repaid. The term has three uses: a credit card cash advance (cash drawn on a card's credit line), a merchant cash advance (a business advance repaid from a share of future sales), and cash in advance (a buyer paying before goods ship).
- Check the context first: card statement, business funding offer or export contract. Each meaning has different rules.
- On a credit card, interest on a cash advance generally starts on the transaction date, with no grace period (CFPB).
- Visa forbids merchants from handing cash to a cardholder unless they offer Cash-Back, Cash-Out or sell foreign currency (section 1.5.5.6).
- A merchant cash advance is repaid as a percentage of sales. New York calls it sales-based financing and requires an estimated APR in the offer.
- In trade, cash in advance means the buyer pays first. The US ITA calls it the most secure method for the exporter.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
"Cash advance" means three different things depending on who says it. A cardholder means cash drawn on a credit card. A business owner usually means a merchant cash advance. An exporter means getting paid before shipping. This page defines each one, with the rules that apply.
What is a cash advance? Three meanings
| Meaning | Who uses it | What happens | How it is repaid | Key rule |
|---|---|---|---|---|
| Credit card cash advance | Cardholders, card issuers | Cash drawn on a credit card line at an ATM, a bank counter or with an issuer check | Through the card balance, with interest from the transaction date | Regulation Z disclosures; Visa Cash Disbursement rules |
| Merchant cash advance (MCA) | Small businesses, funders | A lump sum paid now against future sales | A percentage of sales or revenue until a set total is reached | State disclosure laws (New York); FTC Act |
| Cash in advance (CIA) | Exporters, importers | The buyer pays before the goods ship | Not repaid: it is the payment itself | Contract terms; ITA guidance |
Credit card cash advance
A credit card cash advance is cash you borrow on your card's credit line. The CFPB explains that grace periods "typically apply only to purchase transactions." With a cash advance, "generally you must start paying interest as of the date of the transaction."1CFPB, What is a grace period for a credit card? (last reviewed September 23, 2024) The same applies to checks sent by your card issuer.
Regulation Z requires the issuer to disclose the APR for "a cash advance" in the account-opening table, and "any fee imposed for an extension of credit in the form of cash or its equivalent" (12 CFR 1026.6(b)(2)(i) and (vii)).2CFPB, Regulation Z, 12 CFR 1026.6 and official interpretation (read October 14, 2026) Your exact rate and fee are in that table, not in any average.
Visa calls the transaction a Cash Disbursement: currency "provided to a Cardholder" as a Cash-Out, as a Manual Cash Disbursement (at a bank counter, face to face) or through an ATM (Visa Core Rules, April 2026, Glossary).3Visa Core Rules and Visa Product and Service Rules, April 18, 2026 It has its own merchant codes: MCC 6010 for manual cash disbursements and MCC 6011 for automated ones (section 4.36.1.1). Close to it, a Quasi-Cash Transaction is the sale of items "directly convertible to cash," such as money orders, travelers cheques or foreign currency, often coded MCC 6051.3Visa Core Rules and Visa Product and Service Rules, April 18, 2026
Before a face-to-face Manual Cash Disbursement or Quasi-Cash Transaction, the acquirer or merchant "must validate the identity of the Cardholder" by reviewing an ID. Some PIN or CDCVM transactions are exempt, such as chip transactions of USD 500 or less (section 5.4.2.1).3Visa Core Rules and Visa Product and Service Rules, April 18, 2026
Merchants cannot hand out cash on a card sale
Visa section 1.5.5.6, Merchant Cash Disbursement Prohibition, reads: "A Merchant must not provide cash to a Cardholder unless the Merchant provides Cash-Back or Cash-Out or sells foreign currency."3Visa Core Rules and Visa Product and Service Rules, April 18, 2026 Cash-Back itself has strict conditions: authorized online, face to face, with a PIN or CDCVM (a PIN in the US), and the cash part identified separately (section 5.8.1.4). Visa adds that a member "must not process a credit refund" for the Cash-Back part.3Visa Core Rules and Visa Product and Service Rules, April 18, 2026 An online store has no legal way to pay out cash through a card sale.
Inside Tagada
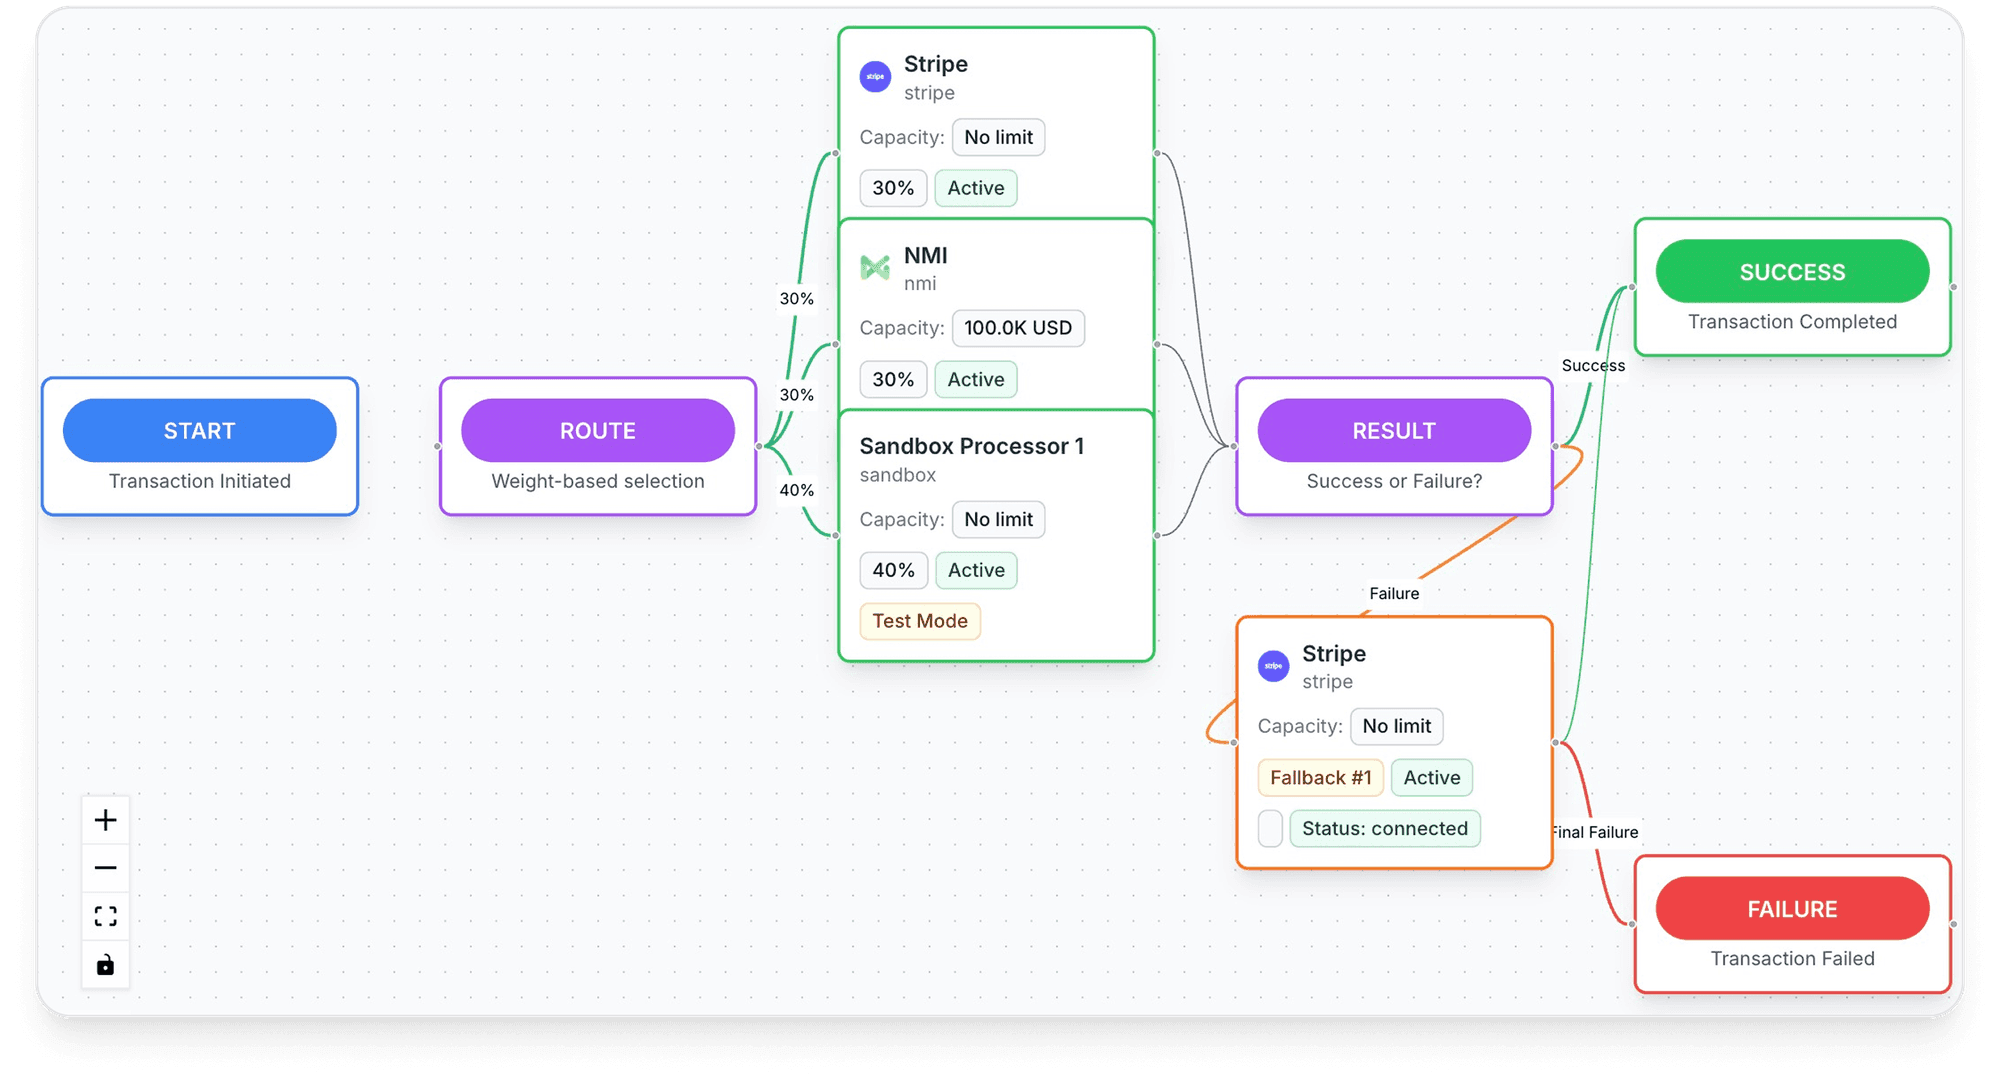
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
Merchant cash advance (MCA)
A merchant cash advance gives a business a lump sum now. The business repays it from future sales, often card sales, until an agreed total is paid. New York law calls this "sales-based financing": a transaction "repaid by the recipient to the provider, over time, as a percentage of sales or revenue," where the payment "may increase or decrease according to the volume of sales" (Financial Services Law section 801(j)).6New York Financial Services Law, section 801 (definitions)
- Offer. The provider quotes the amount funded, the total repayment amount and the share of sales it will collect.
- Disclosure. In New York, the offer must show the finance charge, an estimated APR, the total repayment amount, the estimated term and prepayment charges.
- Funding. The business receives the money, minus any fees deducted.
- Holdback. The provider collects its percentage of sales, from card settlements or by debiting the bank account.
- Payoff. Collection stops once the total repayment amount is reached.
Sources: New York Financial Services Law sections 801 and 803.
The disclosure list comes from section 803 of the same law, which also requires "the payment amounts, based on the projected sales volume."7New York Financial Services Law, section 803 (sales-based financing disclosures) Some contracts use a fixed daily or weekly payment with a "true-up" that adjusts it back to a percentage of sales (section 801(j)). That answers a common question: a holdback moves with sales, a fixed withdrawal does not until it is reconciled.
Illustrative example (round numbers for the arithmetic, not market terms): a store gets $10,000 and agrees to repay $12,000 through a 10% holdback. On a day with $3,000 in card sales, $300 goes to the provider. On a $1,000 day, $100. The $12,000 total stays the same; only the time to reach it changes.
What the FTC has acted on
The FTC said one MCA provider, Yellowstone Capital, "made false claims about collateral, personal guarantees, and the cash amounts it provides" and took unauthorized withdrawals from bank accounts.4FTC Business Blog, Protecting small businesses seeking financing during COVID (August 3, 2020) In FTC v. RCG Advances, the court banned RCG Advances and Robert Giardina from the MCA industry and ordered $1.5 million upfront plus more than $1.2 million in refunds.5FTC, FTC v. RCG Advances, LLC, case page (updated February 14, 2024)
Cash in advance in trade
Cash in advance (CIA) is a payment term, not a loan. The International Trade Administration defines it as the method where "the importer pays the full or a significant amount of the payment before the goods are shipped," and calls it "the most secure method of payment for the exporter."8International Trade Administration, Cash-in-Advance (read October 14, 2026) The exporter "can avoid credit risk," but it is "the least attractive option for the buyer, because it creates unfavorable cash flow."9International Trade Administration, Methods of Payment (read October 14, 2026)
The ITA names three ways to pay: a wire transfer ("the most secure and preferred" option), a credit card ("especially for small consumer goods transactions") and an escrow service.8International Trade Administration, Cash-in-Advance (read October 14, 2026) Example: an online store asks a wholesale buyer abroad to pay by wire before it ships. That is cash in advance. Most online stores selling to consumers work this way: the card is charged at checkout, before shipping.
Other uses of the term
In accounting, a cash advance can be money given ahead of expenses to an employee or a subsidiary. An "unliquidated" cash advance is one not yet settled with receipts or repaid. For how card funds actually reach a merchant, see settlement. For the codes that flag cash-like sales, see high-risk MCC codes.
How Tagada helps
Payments that follow the card network rules
Tagada follows Visa and Mastercard rules and the laws that apply to payments.
Frequently asked questions
What is a cash advance in simple terms?
How is a credit card cash advance repaid?
How is a merchant cash advance repaid?
What does cash in advance mean in payment terms?
What is a cash advance to a subsidiary?
Sources
Checked October 15, 2026- CFPB, What is a grace period for a credit card? (last reviewed September 23, 2024)
- CFPB, Regulation Z, 12 CFR 1026.6 and official interpretation (read October 14, 2026)
- Visa Core Rules and Visa Product and Service Rules, April 18, 2026
- FTC Business Blog, Protecting small businesses seeking financing during COVID (August 3, 2020)
- FTC, FTC v. RCG Advances, LLC, case page (updated February 14, 2024)
- New York Financial Services Law, section 801 (definitions)
- New York Financial Services Law, section 803 (sales-based financing disclosures)
- International Trade Administration, Cash-in-Advance (read October 14, 2026)
- International Trade Administration, Methods of Payment (read October 14, 2026)
TagadaPay
Selling online? Run every processor from one checkout
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors