What Is Chip and PIN?
Chip and PIN meaning: how chip plus PIN works, chip and PIN vs chip and signature vs contactless, and what Visa rules mean for a business terminal.
Article summary
TL;DR
Chip and PIN is a way to pay in a store: the customer inserts a card with an EMV chip into the terminal and types a secret PIN on the keypad. The chip proves the card is genuine, and the PIN proves the person is the cardholder. In the UK, it fully replaced signatures for in-store card payments in 2006.
- Two checks in one payment: the EMV chip authenticates the card, the PIN verifies the cardholder.
- Visa calls these cards PIN-Preferring Chip Cards: the chip's verification list puts PIN, offline or online, first.
- Chip and signature leaves the check to store staff, and Visa lets merchants skip the signature.
- To accept it, a business needs an EMV PIN-compliant terminal, one that meets the PCI PIN requirements.
- Chip and PIN is for card-present payments only. Online, the issuer checks the buyer through 3D Secure.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
Chip and PIN is the name the UK gave to EMV chip cards verified with a PIN. Here is what it means, how it compares with signature and contactless, and what a business needs to accept it.
What is chip and PIN?
Chip and PIN joins two checks at a store terminal. The card's EMV chip creates a one-time code for each payment, so the card cannot be copied like a magnetic stripe. Then the cardholder types a PIN, which either the chip (offline PIN) or the issuing bank (online PIN) checks. The chip proves the card. The PIN proves the person.
Visa calls a card set up this way a "PIN-Preferring Chip Card": a chip card whose verification list specifies "a preference for a PIN-based Cardholder Verification Method (either offline or online)."1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 The issuer writes that order on the chip; see cardholder verification method.
The term comes from the UK. On February 14, 2026, UK Finance marked "twenty years since Chip & PIN fully replaced signatures for in-store card purchases." It reports "a 95 per cent reduction in losses to counterfeit card fraud over the last 20 years." Chip and PIN still accounts "for 30 per cent of all credit and debit card payments by value", with an average payment of £93, against £17 for contactless.2UK Finance, 20 years of change in payments: from Chip & PIN to mobiles, February 14, 2026
Inside Tagada
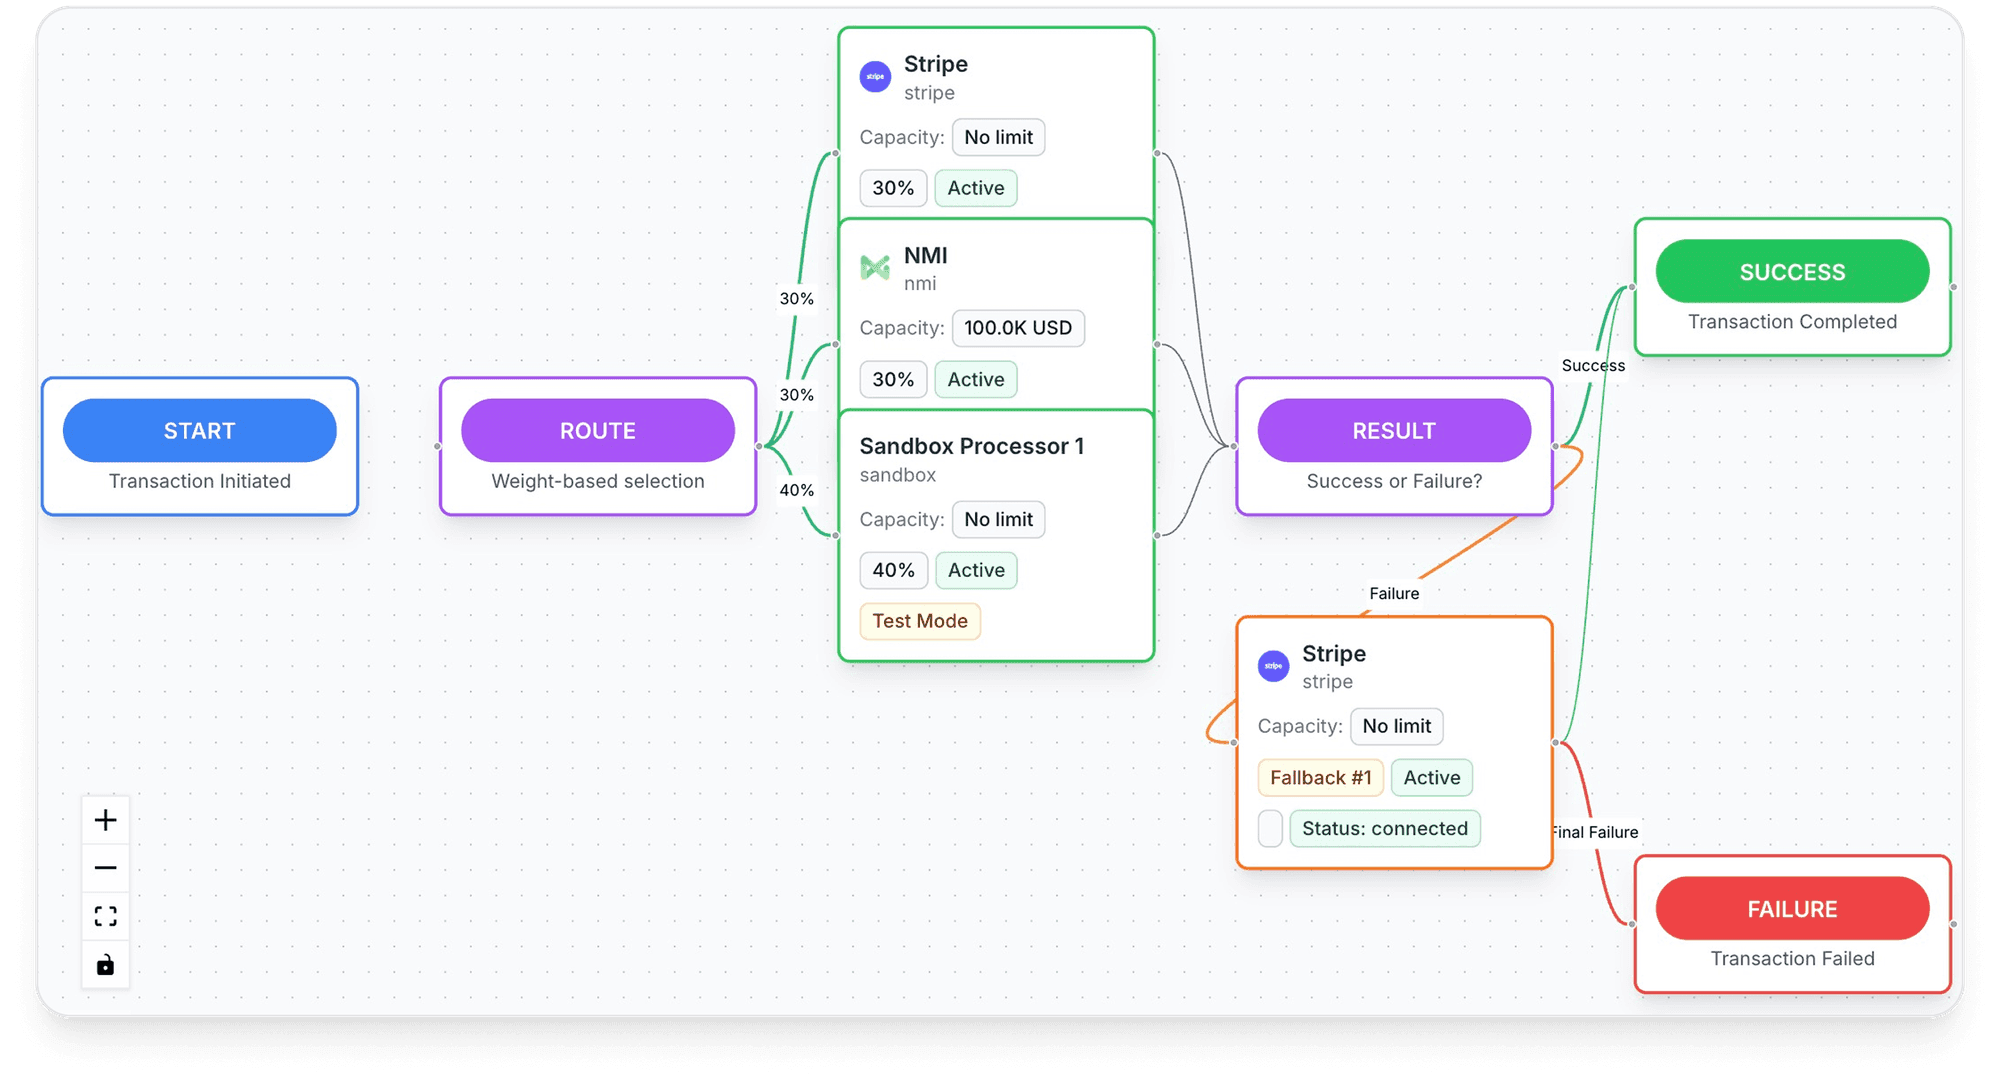
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
Chip and PIN vs chip and signature vs contactless
The same card can pay all three ways. What changes is who checks the cardholder, and who pays when a lost or stolen card is used.
| Chip and PIN | Chip and signature | Contactless | |
|---|---|---|---|
| Card read | Inserted, chip read | Inserted, chip read | Tapped card, phone or watch |
| Who checks the cardholder | The chip or the issuer, through the PIN | Store staff, if they check the signature | Nobody under the country limit; PIN or phone unlock above it |
| Lost or stolen card fraud (Visa) | The issuer's loss at an EMV PIN-compliant device (4.1.17.46) | Can fall on the acquirer when the card prefers PIN and no PIN was checked (5.8.2.5) | Visa's lost or stolen chip dispute (10.2) is invalid (11.7.3.3) |
Source: Visa Core Rules, April 2026.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 This lost or stolen rule only applies in regions where Visa's liability shift covers non-counterfeit fraud; in the US it covers counterfeit cards only. See liability shift. Visa also lets a merchant process a payment "without the Cardholder signature" even when the card prefers one (section 5.6.1.1).1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 Contactless limits by country are on our cardholder verification method page.
What a business needs for chip and PIN
- An EMV PIN-compliant terminal. Visa defines it as "A Chip-Reading Device that complies with the PIN requirements of the Payment Card Industry Security Standards Council."1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 In practice, pick a model on the PCI list: the PCI SSC "approves PTS POI devices, and provides a listing of approved devices."3PCI Security Standards Council, PTS Point of Interaction (POI) (read October 14, 2026) How to check a model is on our smart terminal page.
- Chip first. Insert the card. Swiping or keying a chip card is a fallback for when the chip cannot be read, and it has its own rules: see manual keyed entry.
- Hands off the PIN. Merchants must not store "PIN or the encrypted PIN block" after authorization (section 1.9.4.1).1Visa Core Rules and Visa Product and Service Rules, April 18, 2026
Chip and PIN stops at the store door. Online, there is no terminal: the issuer checks the buyer through 3D Secure. For how that works, see our guide to payment authentication.
How Tagada helps
Payments that follow the card network rules
Tagada follows Visa and Mastercard rules and the laws that apply to payments.
Frequently asked questions
What does chip and PIN mean for a business?
What is the difference between chip and PIN and chip and signature?
Does chip and PIN work for online payments?
Sources
Checked October 15, 2026TagadaPay
Selling online too? Run card payments from one checkout, across processors
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors