What Is a Commercial Card and How Does It Work?
Commercial card types from Visa's own rules, how issuance and reporting work, and what merchants pay: 2.70% online, 1.75% with Level 3 data, EU rules.
Article summary
TL;DR
A commercial card is a payment card issued to a business, a public body or a self-employed person for business expenses only. Employees use it for travel, supplies or fuel, and the company gets the bill and a spending report. Corporate, purchasing, fleet, business and virtual cards are all commercial cards.
- Visa's rules allow commercial cards only for business-related purchases, issued to employees, contractors or sole proprietors.
- Corporate cards cover travel, purchasing cards cover company purchases, fleet cards cover fuel and vehicle repairs, business cards serve small companies.
- On Visa's April 2026 US table, a commercial card online sale costs 2.70% + $0.10 in interchange, against 1.89% + $0.10 for a basic consumer credit card.
- Sending line-item (Level 3) data that passes Visa's checks moves corporate and purchasing card sales to 1.75% + $0.10.
- In the EU, the interchange caps don't apply to commercial cards, and a merchant may choose not to accept them.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
A commercial card is a payment card a company gives to its employees, or uses itself, to pay for business expenses. Visa, Mastercard and the banks that issue the cards treat it as its own product family, with its own rules and its own interchange rates. This page covers the types, how a program works, and what changes when a merchant accepts one.
What is a commercial card?
Visa defines its commercial cards as "a physical or virtual Card intended for business expense use."1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 An issuer "may only issue Visa Commercial Cards to provide a means of payment for business-related goods and services" and must not issue one to an individual, except employees, contractors in an employer program, sole proprietors and self-employed people (Visa Core Rules, April 2026, section 4.14.1.1).1Visa Core Rules and Visa Product and Service Rules, April 18, 2026
EU law uses the same idea. Regulation 2015/751 defines a commercial card as one "issued to undertakings or public sector entities or self-employed natural persons which is limited in use for business expenses," where payments are "charged directly to the account" of the business (article 2).3Regulation (EU) 2015/751 on interchange fees for card-based payment transactions
Types of commercial cards
The table uses Visa's own definitions from the glossary of its rules.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026
| Type | Visa definition | Used for |
|---|---|---|
| Corporate card (travel card) | "Targeted to mid-to-large size companies," primarily for "employee business travel and entertainment expenses" | Flights, hotels, meals |
| Purchasing card (P-card) | "Issued to commercial entities (public and private) that is used for commercial purchases" | Supplies, equipment, supplier invoices |
| Fleet card | Used "for the purchase of fuel and vehicle maintenance services" at listed merchant categories | Fuel, repairs, EV charging |
| Business card | Issued "to employees or sole proprietors of small businesses" for travel and "general business expenses" | Small business spending |
| Virtual card | Commercial cards can be "physical or virtual." A virtual account has "no physical Card" and is mainly for online payments | Online and supplier payments |
In Visa's list, the fleet card sits inside the purchasing card family. In the US, Visa also has a Visa Travel Card for public sector and non-profit bodies (section 4.14.1.1).1Visa Core Rules and Visa Product and Service Rules, April 18, 2026
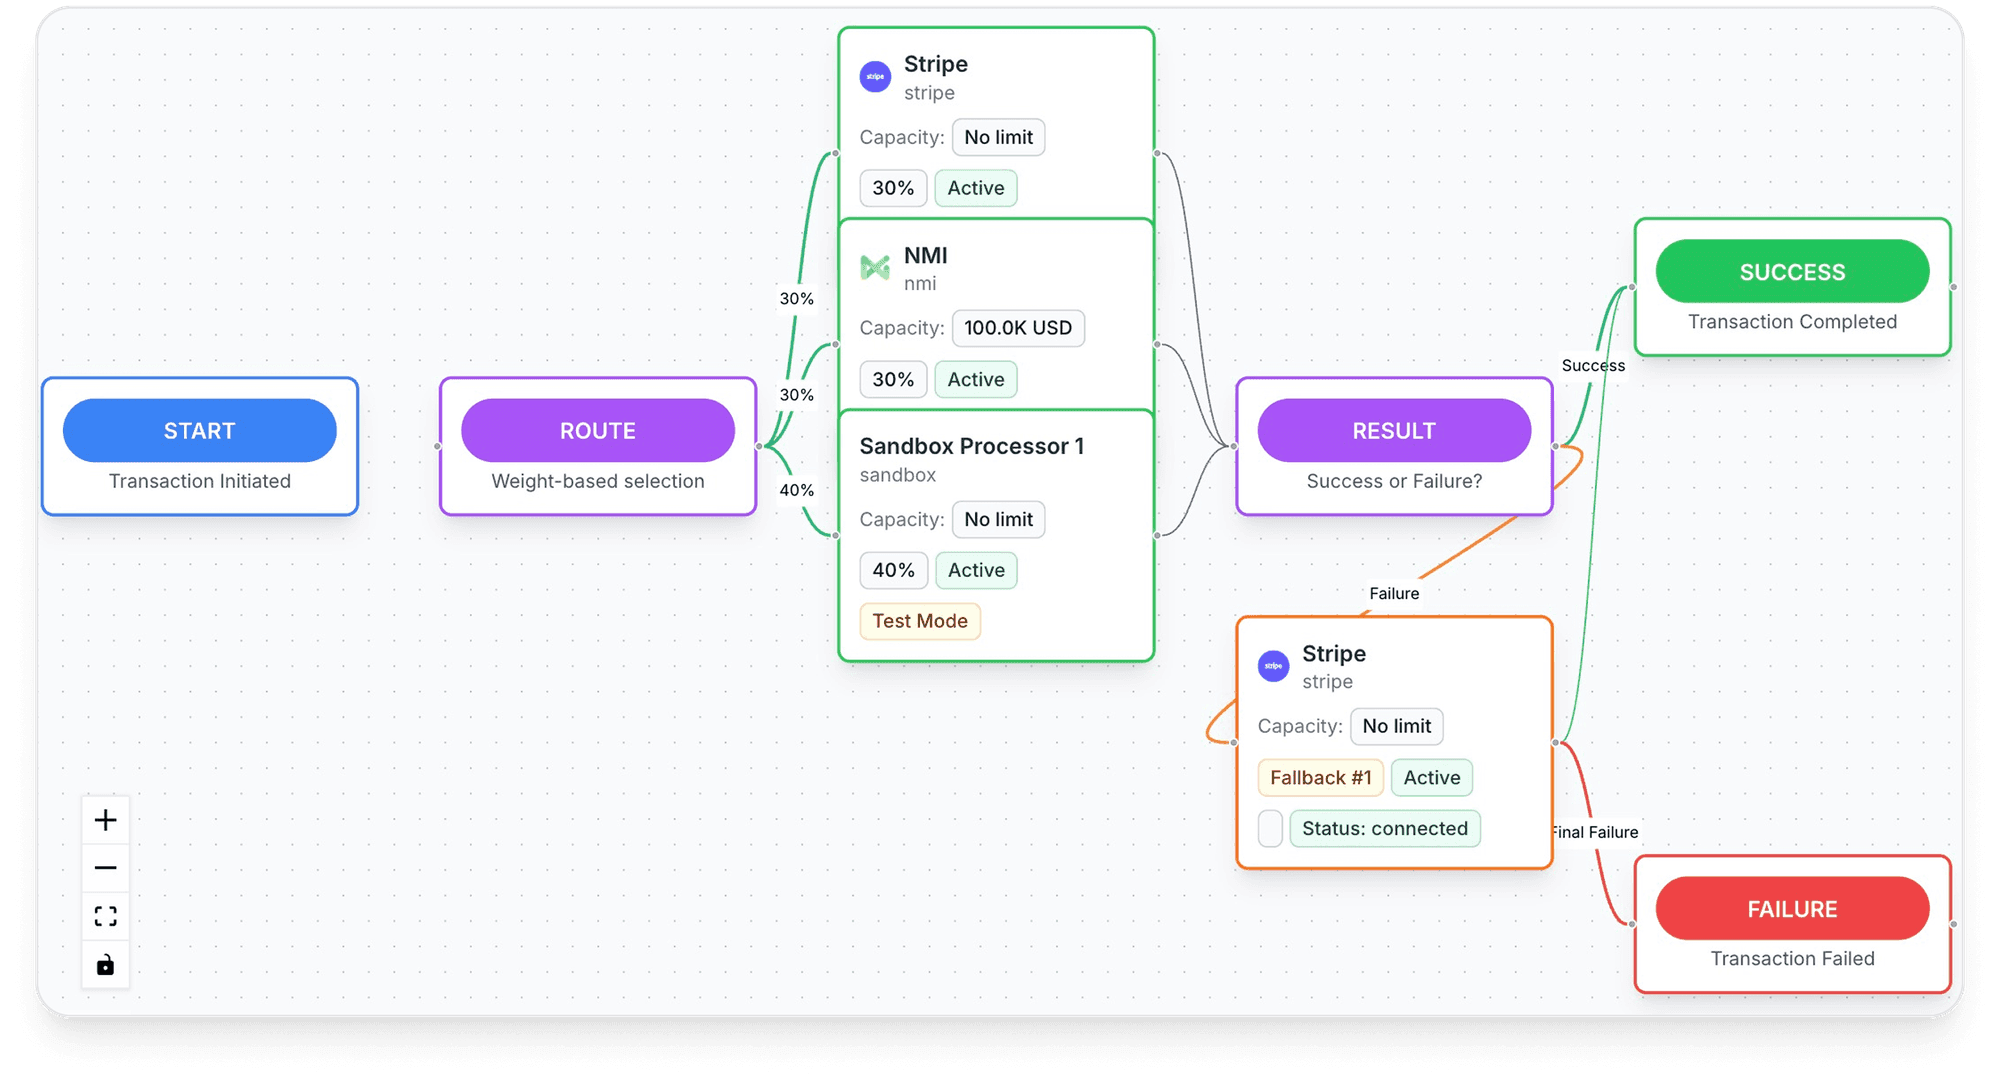
Inside Tagada
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
How a commercial card program works
- Issuance. A bank opens a program for the company and issues cards to named employees, vehicles or as virtual numbers. Visa doesn't allow consumer and commercial cards on the same BIN (section 2.2.3.1).
- Billing setup. Corporate and purchasing card issuers must offer individual billing, individual billing with company payment, and central company billing (in Europe, purchasing cards are billed centrally only).
- Controls. Purchasing cards need "flexible Transaction authorization": the issuer can block a purchase by amount or merchant category code chosen by the company.
- Purchase. The employee pays like with any card, in store or online.
- Reporting. The issuer sends management reports: corporate card spend "by vendor, employee, and company organization units." In the US, purchasing card issuers must report all transactions, matched to merchant profiles or not.
Source: Visa Core Rules, April 18, 2026, sections 4.14.1.1, 4.14.1.2 and 4.21.1.3.
What changes for a merchant
Higher interchange
Business cards cost more to accept than basic consumer cards. On Visa's US table effective April 18, 2026, a corporate or purchasing card used online falls under "Commercial Card Not Present" at 2.70% + $0.10. A basic consumer credit card online costs 1.89% + $0.10.2Visa, Visa USA Interchange Reimbursement Fees, April 18, 2026 (read October 14, 2026) On a $100 sale, that's $2.80 against $1.99. To see how this reaches your bill, see pass-through pricing.
Level 2 and Level 3 data
Visa's rules call it Enhanced Data. The transaction part includes the "accounting code," "sales tax or value-added tax," and "description of items purchased, cost per unit, number of units."1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 Level 2 means the tax; Level 3 means the line items.
Stripe explains that Visa replaced its US Level 3 program with the Commercial Enhanced Data Program (CEDP) on October 18, 2025, with "Product 3" rates, and sunset Level 2 on April 18, 2026. Visa checks the data quality, and a scheme fee applies to transactions sent with line-item data.4Stripe Support, Understand the Visa Commercial Enhanced Data Program (CEDP) (read October 14, 2026) On Visa's table, Commercial Product 3 is 1.75% + $0.10 for purchasing and corporate cards.2Visa, Visa USA Interchange Reimbursement Fees, April 18, 2026 (read October 14, 2026)
Example: one B2B order, with and without Level 3
This example is illustrative: a $2,500 online order paid with a US Visa purchasing card, using Visa's April 2026 rates.2Visa, Visa USA Interchange Reimbursement Fees, April 18, 2026 (read October 14, 2026) The CEDP scheme fee and your processor's markup are not included.
| Same $2,500 online sale | Visa program | Interchange |
|---|---|---|
| Purchasing card, no line-item data | Commercial Card Not Present, 2.70% + $0.10 | $67.60 |
| Purchasing card, Level 3 data accepted by Visa | Commercial Product 3, 1.75% + $0.10 | $43.85 |
| Basic consumer credit card, for comparison | Product 1, All Other Products, 1.89% + $0.10 | $47.35 |
Verdict
With accepted Level 3 data, the business card costs $23.75 less in interchange on this order, and less than a basic consumer card.
For every Visa program and the other ways to qualify for lower rates, see credit card interchange fees.
In the EU: no cap, and acceptance is optional
The EU caps consumer card interchange, but article 1(3)(a) of Regulation 2015/751 says the chapter with those caps "does not apply" to "transactions with commercial cards."3Regulation (EU) 2015/751 on interchange fees for card-based payment transactions The same law lets merchants refuse a card category: the honor all cards obligation covers consumer cards only (article 10). Visa's rules agree: a Limited Acceptance merchant in the EEA "is not required to accept commercial Cards issued in the EEA" (section 1.5.4.6).1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 If you refuse them, the law says to tell buyers clearly on your website before they buy. See honor all cards rule and scheme fee.
Exact amounts on commercial payables
For a Visa purchasing card commercial payables transaction, the final amount must match the authorized amount. See overcapture.
How Tagada helps
Payments that follow the card network rules
Tagada follows Visa and Mastercard rules and the laws that apply to payments.
Frequently asked questions
What are commercial cards and how do they work?
What is the difference between corporate and commercial cards?
What is a commercial card for employees?
What is a Mastercard commercial card?
What is commercial card reporting?
Sources
Checked October 15, 2026- Visa Core Rules and Visa Product and Service Rules, April 18, 2026
- Visa, Visa USA Interchange Reimbursement Fees, April 18, 2026 (read October 14, 2026)
- Regulation (EU) 2015/751 on interchange fees for card-based payment transactions
- Stripe Support, Understand the Visa Commercial Enhanced Data Program (CEDP) (read October 14, 2026)
TagadaPay
Selling to businesses and consumers? Run every processor from one checkout
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors