What Is a MOTO (Mail Order/Telephone Order) Payment?
MOTO meaning: how mail and telephone order payments are processed and flagged, MOTO vs e-commerce, and Visa rules on CVV2, disputes and receipts.
Article summary
TL;DR
MOTO (mail order/telephone order) is a card payment where the customer sends their card details by phone, mail, fax or email and the merchant enters them to charge the card. Visa calls it a Mail/Phone Order Transaction and treats it as card-absent: no 3-D Secure, card-not-present fraud rules, and its own flag in the authorization.
- Visa defines a Mail/Phone Order as a purchase in a Card-Absent Environment ordered by telephone, mail or other means of telecommunication.
- The payment must be flagged as MOTO in the authorization: moto in Stripe, shopperInteraction Moto in Adyen, commerce indicator moto in Cybersource.
- Visa forbids changing the POS Entry Mode or the Electronic Commerce Indicator when you retry a declined authorization (section 1.7.2.1).
- Fraud claims on MOTO payments fall under Visa condition 10.4, and a signed order form is accepted compelling evidence for a mail or phone order (Table 11-6).
- In the EU, genuine phone and mail orders are out of scope of SCA, but the issuer still decides and can refuse the MOTO flag.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
MOTO is the oldest form of remote card payment. The customer reads their card out on the phone or writes it on an order form, and the merchant charges it. No card reader, no checkout page, and no way for the cardholder to authenticate with their bank. Those three facts decide how the payment is flagged, who pays for fraud and what you may keep.
What is a MOTO payment?
Visa defines a Mail/Phone Order as a "purchase in a Card-Absent Environment where a Cardholder orders goods or services from a Merchant by telephone, mail, or other means of telecommunication."1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 So fax and email orders count too. What matters is that the customer hands over card details and the merchant, not the customer, submits them.
Some merchant categories are built around this channel. Visa's merchant code manual lists, for example:2Visa Merchant Data Standards Manual, April 2026
- MCC 5964, Direct Marketing – Catalog Merchant: sells through catalogs with no face-to-face way to buy.
- MCC 5966, Direct Marketing – Outbound Telemarketing Merchant: the merchant calls or mails prospects first.
- MCC 5969, Direct Marketing – Other Direct Marketers: orders placed by mail, telephone or fax through an order form, address or phone number.
Any business can take MOTO payments, though: a store taking a phone deposit, a clinic billing by phone, or an online brand whose customer prefers to call.
How telephone and mail order processing works
approved declined or closed routing step
- CustomerCalls, mails or faxes the order with card details
- reads outMerchantKeys the card in a virtual terminal or sends it by API
- submitsProcessorFlags the authorization as MOTO
- routes toIssuerChecks CVV2 and address, then approves or declinesApproved
The key step is the flag. Each provider has its own name for it: Stripe uses a moto parameter on Payment Intents and Setup Intents,3Stripe Docs, Mail order telephone order (MOTO) Adyen sets shopperInteraction to Moto,5Adyen Docs, Mail order and telephone order: API request and Cybersource, which belongs to Visa, uses the commerce indicator moto for a mail or telephone order.6Cybersource Developer Center, commerceIndicator field reference The flag tells the issuer the order did not come from a web checkout, so it does not expect a 3-D Secure result. The ECI page covers the codes used for online payments.
Visa requires complete and accurate data in every authorization. When you retry after a decline, you must not change the POS Entry Mode, the Electronic Commerce Indicator or the MCC of the original request (section 1.7.2.1).1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 In plain terms: a declined online payment cannot be resent as MOTO to get it through.
Most merchants key MOTO orders in a virtual terminal. That page covers the screen itself, PCI SAQ C-VT and provider fees.
MOTO vs e-commerce vs card-present
| MOTO | E-commerce | Card-present | |
|---|---|---|---|
| Who enters the card | The merchant | The customer | The card, at a terminal |
| Visa environment | Card-absent | Card-absent | Card-present |
| 3-D Secure | Not possible | Possible | Not used |
| Authorization flag | MOTO | E-commerce (ECI) | POS Entry Mode of the chip or tap |
| Visa fraud dispute | 10.4 | 10.4, blocked by 3-D Secure in most cases | 10.1 or 10.3 |
| Receipt | Paper only or email only, your choice (5.9.1.1) | Paper only or email only, your choice | Paper unless the cardholder agrees to email |
| EU SCA | Out of scope | Required unless exempt | Required unless exempt |
Sources: Visa Core Rules, April 2026, sections 5.9.1.1, 10.11.3.5 and Chapter 11; EBA Q&A 2019_4788.1Visa Core Rules and Visa Product and Service Rules, April 18, 20267EBA Single Rulebook Q&A 2019_4788 (final, March 12, 2021)
Inside Tagada
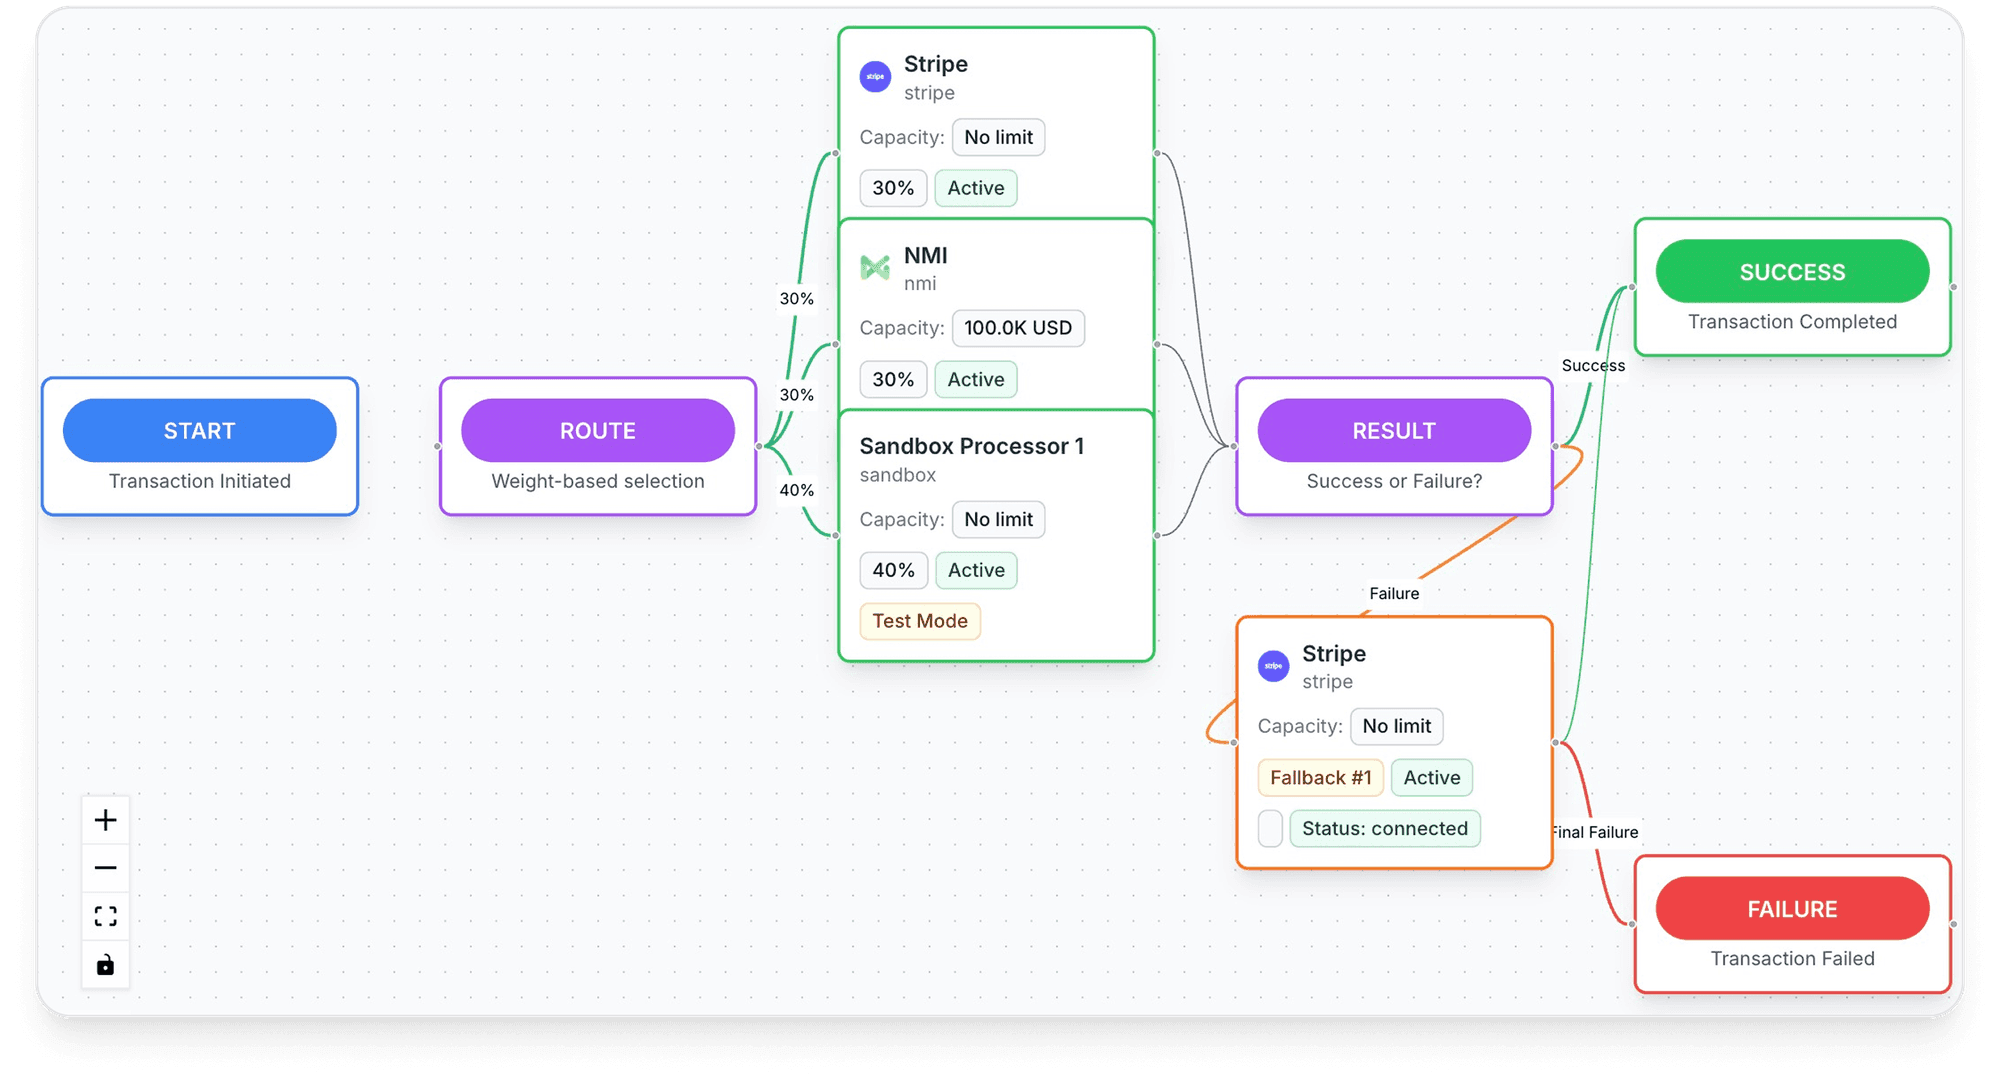
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
Visa rules a MOTO merchant must follow
- CVV2, 10.11.3.4 (Canada)Mail/Phone Order Merchants must capture the CVV2 and send it, except for paper order forms, written mail orders, stored credentials and recurring paymentsAsk for the code on every phone order
- CVV2, 10.11.3.5 (Europe)Card-absent authorizations must carry the CVV2. An issuer that approves despite a CVV2 result N is liableNever skip the code to save time
- Merchant country, 5.8.6.1A Mail/Phone Order Merchant must disclose its outlet country when presenting payment optionsSay it on the call or print it on the form
- Surcharge, 5.5.1.9 (US, Canada) and 5.5.1.2 (Australia)After the surcharge is disclosed, the cardholder must be able to cancel. In Australia, the telephone clerk must state the surcharge amountAnnounce any surcharge before you charge
- Retry data, 1.7.2.1No changing POS Entry Mode, ECI or MCC on a retry after a declineKeep MOTO and online flows separate
For card-not-present costs and interchange, see card-not-present. Surcharge rules are detailed in credit card surcharges.
Disputes and liability on MOTO payments
A cardholder who says they never placed a phone order disputes it under condition 10.4, Other Fraud – Card-Absent Environment.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 With no 3-D Secure, the merchant cannot shift that loss to the issuer. What remains is evidence.
Visa's list of allowable compelling evidence for a 10.4 pre-arbitration includes, for a Mail/Phone Order Transaction, "a signed order form" (section 11.5.1, Table 11-6, item 6).1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 Visa's Order Form is a document bearing the cardholder's signature, "either written or electronic", and may be a mail order form, a recurring transaction form or an email or other electronic record.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 Other items work for MOTO too, such as delivery to an address that got an AVS match of Y or M (item 3).
So for phone orders, send the customer a written confirmation they sign or approve by email. For mail orders, keep the form, but never the CVV2: Visa forbids storing it after authorization (section 1.9.4.1).1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 For the full method, see compelling evidence and ecommerce fraud prevention.
Recurring MOTO and saved cards
A phone order often turns into a subscription. Stripe lets you flag the Setup Intent that saves the card as MOTO, not just a one-off payment.3Stripe Docs, Mail order telephone order (MOTO) Later charges are not new phone orders: they run on a stored credential, and Visa's CVV2 rules in Canada and Europe exempt stored-credential and recurring payments.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 Cybersource uses a separate recurring indicator for them.6Cybersource Developer Center, commerceIndicator field reference Get the customer's agreement to future charges on record before saving the card.
MOTO and SCA in Europe
The EBA says remote non-electronic payments "initiated and executed via a mail order or telephone order can be considered out of scope of the SCA requirement."7EBA Single Rulebook Q&A 2019_4788 (final, March 12, 2021) The flag must be honest. Stripe says your integration "must correctly flag transactions as MOTO", that the cardholder's bank makes the final decision, and that if the bank does not support the MOTO exemption, "the customer must complete the payment on your website."3Stripe Docs, Mail order telephone order (MOTO) In the EEA, Stripe treats payments with manually entered card details as MOTO automatically.4Stripe Support, When to categorize transactions as MOTO The virtual terminal page covers the European Commission's limit on keyed payments.
How Tagada helps
When the customer can pay for themselves
Tagada's checkout runs native 3DS2, device intelligence and a rules engine, so a phone customer can be sent a checkout, authenticate and be screened before authorization instead of reading out their card. Payments route across TagadaPay and processors such as Stripe, NMI and Airwallex with one logic, with a cascade to another processor when one is down or times out. Tagada follows Visa and Mastercard rules and the laws that apply to payments.
Frequently asked questions
What does MOTO stand for in payments?
Is a MOTO payment card-not-present?
Do you need the CVV for a telephone order payment?
Are MOTO payments exempt from SCA?
Can I set up recurring payments over the phone?
What is telephone and mail order processing?
Sources
Checked October 15, 2026- Visa Core Rules and Visa Product and Service Rules, April 18, 2026
- Visa Merchant Data Standards Manual, April 2026
- Stripe Docs, Mail order telephone order (MOTO)
- Stripe Support, When to categorize transactions as MOTO
- Adyen Docs, Mail order and telephone order: API request
- Cybersource Developer Center, commerceIndicator field reference
- EBA Single Rulebook Q&A 2019_4788 (final, March 12, 2021)
TagadaPay
Move phone customers to a checkout they can authenticate on
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors