
What Is a Marketplace in Payments?
What a marketplace is in payments: Visa's definition and rules, seller payouts on Stripe and Adyen, marketplace vs payfac, merchant of record, tax.

Article summary
TL;DR
A marketplace is a website or app that brings buyers and many retailers together, takes the card payments for those retailers and receives the settlement in their place. Visa uses exactly that definition. The marketplace then pays each seller its sales minus refunds, disputes and its fees, and it carries the disputes toward the card network.
- Visa defines a marketplace as an entity that brings cardholders and retailers together online, processes transactions and receives settlement on their behalf.
- To qualify, its brand must be more prominent than the sellers', and it must be financially liable for disputes and settle them itself.
- The buyer pays the marketplace. The marketplace pays each seller promptly, minus refunds, discounts, disputes and agreed fees.
- On Stripe, the charge type decides where funds land and who pays refunds and disputes. On Adyen, split instructions divide each payment.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
In payments, "marketplace" is not just a business model. Visa has a defined category for it, with its own rules, and it changes who gets paid, who refunds and who answers for disputes. By industry: selling on marketplaces for supplement brands, selling on marketplaces for skincare brands and Amazon vs. your own store for supplement brands.
What is a marketplace?
Visa defines a marketplace as "an entity that brings together Cardholders and retailers on an electronic commerce website or mobile application and processes Transactions and receives Settlement on behalf of those retailers."1Visa Core Rules and Visa Product and Service Rules, April 18, 2026
Visa first checks whether a business is a plain merchant: it sells the goods, uses its own name at checkout and gives the cardholder recourse. If not, it can be classified as a marketplace, a payment facilitator or a wallet operator (section 5.3.2.2). To be a marketplace, it must meet all of these (section 5.3.4.1):1Visa Core Rules and Visa Product and Service Rules, April 18, 2026
- Its name is shown more prominently than the sellers' names and is part of the app name or URL.
- It handles payments and refunds for its retailers and receives settlement for them.
- It is financially liable for disputes and resolves them with a binding decision or a money-back guarantee it funds.
- No foreign retailer exceeds both USD 10 million in yearly Visa volume through it and 10% of its Visa volume.
Travel agents, High-Integrity Risk Merchants and charities, crowdfunding included, can't be marketplaces or sell through one. For a seller, it's the opposite of running your own store, where you are the merchant of record.
How marketplace payments and seller payouts work
- The buyer pays the marketplace. One checkout, under the marketplace's brand.
- The acquirer settles to the marketplace. Visa lets an acquirer pay a marketplace directly. The marketplace may only deposit sales made through its own site or app.
- The marketplace splits the money. On Stripe Connect, a destination charge lands on the platform and part of it moves to one seller. Separate charges and transfers let one charge pay several sellers, for example a single cart from multiple shops. On Adyen for Platforms, split instructions send part of each payment to a seller's balance account and the commission to the platform's.
- Each seller gets paid out. Visa requires the marketplace to pay its retailer "promptly", the sales total minus refunds, discounts, disputes or other agreed fees.
Sources: Visa Core Rules April 2026 (section 1.5.6), Stripe and Adyen docs read October 14, 2026.
With both Stripe charge types, refunds and disputes are debited from the platform's balance; it can reverse the transfer to recover them.2Stripe Docs, Understand how charges work in a Connect integration (read October 14, 2026) On Adyen, without split instructions, the whole amount and fees go to the platform's liable balance account.3Adyen Docs, Split transactions in Adyen for Platforms (read October 14, 2026) The three platform models are compared on our embedded payments page, and payout timing on payout.
Inside Tagada
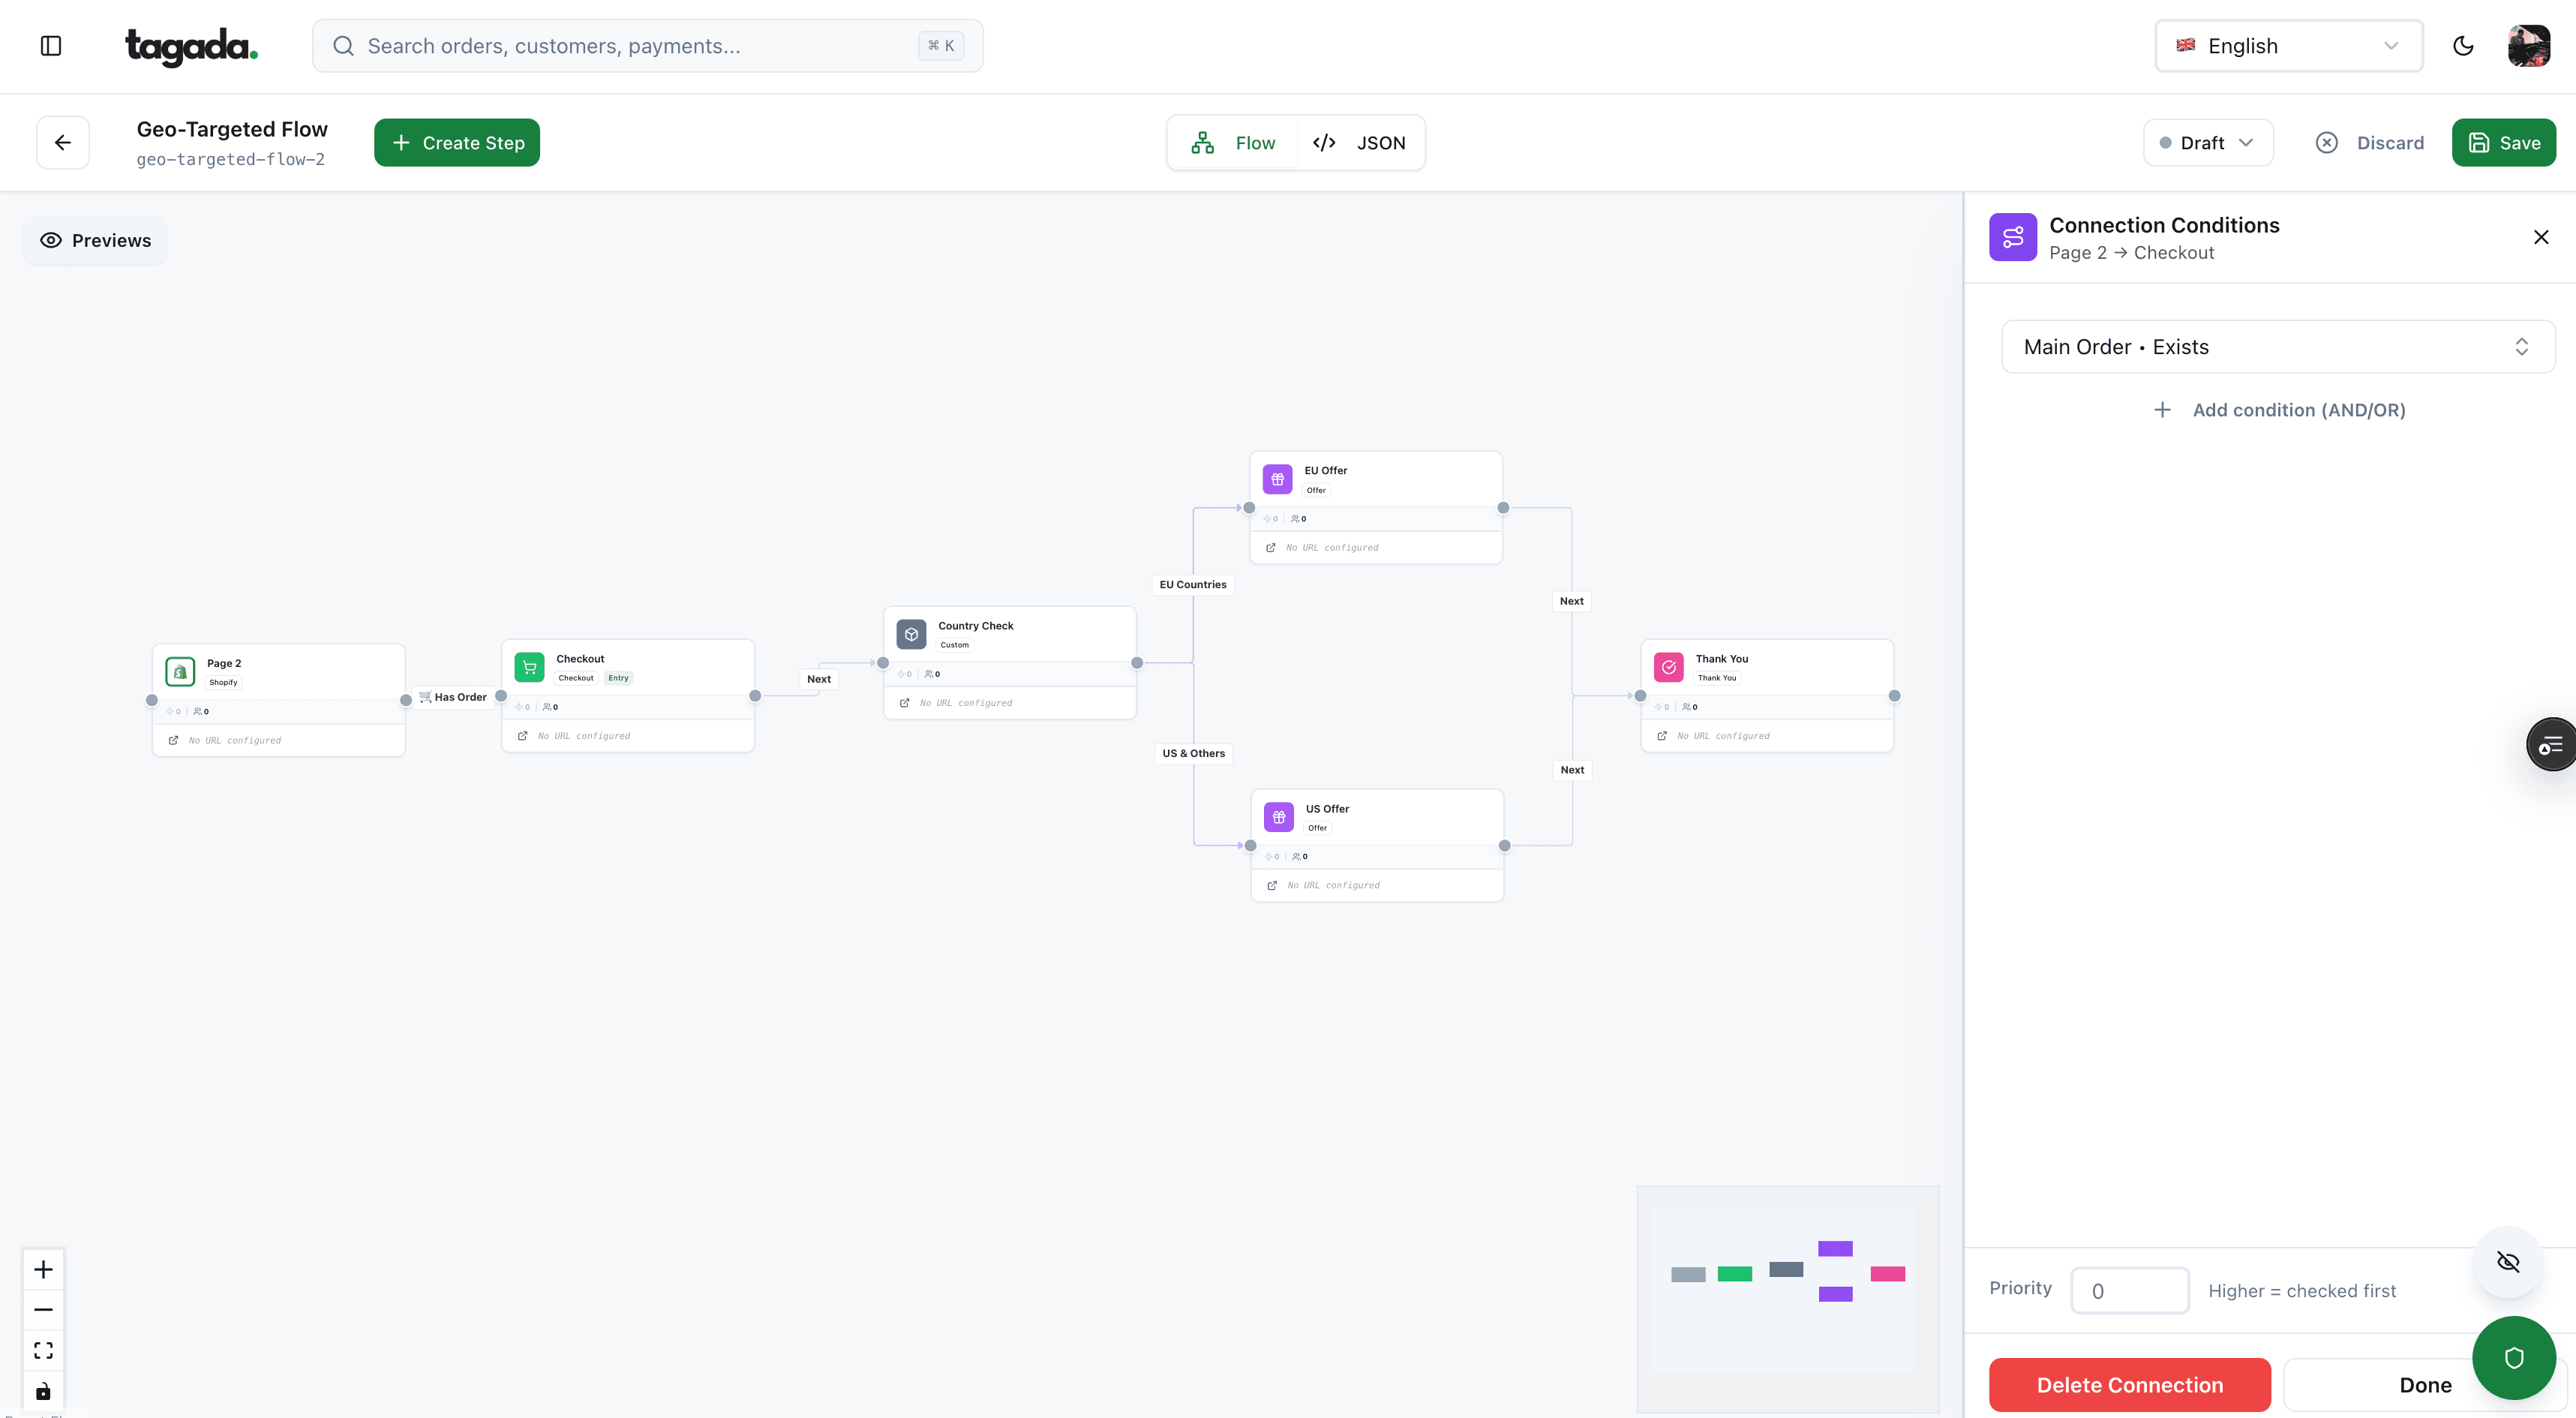
Build the funnel once, route every customer to the right offer
Checkout, upsells and subscriptions on one flow, with conditions per country, order or customer.
Marketplace vs payment facilitator
| Marketplace | Payment facilitator | |
|---|---|---|
| Who signs the seller | The marketplace, before depositing its sales | The payfac, under a merchant agreement |
| Brand at checkout | The marketplace's, above the sellers' | The merchant's, sometimes after the payfac's |
| Liable for disputes | The marketplace, which also resolves them | The payfac, toward its acquirer |
| Visa registration | Third Party Agent, with a marketplace identifier on every authorization and clearing record | Payment facilitator, confirmed by Visa |
The acquirer of a marketplace must also check its sellers and block illegal and counterfeit sales (section 5.3.4.4). A payfac may sign a marketplace only if the marketplace identifier travels with each transaction and at least 75% of its sellers are in its country (section 5.3.1.5).1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 More on this model on our aggregator merchant page.
What it means for an online merchant
If you sell on a marketplace, its terms set your payout schedule and how disputes reach you. Tax duties can move to the platform too: in the EU, marketplaces facilitating some sales of goods are "deemed" to have supplied them for VAT,4European Commission, VAT e-Commerce One Stop Shop (read October 14, 2026) and in the US they file Form 1099-K for sellers above the IRS threshold (see disbursement).5IRS, Understanding your Form 1099-K, updated June 28, 2026 EU payment providers also report cross-border payees under CESOP.
If you sell on your own store, you are not a marketplace, and Visa's marketplace rules don't apply to you.
How Tagada helps
Your own checkout, more than one processor
Tagada routes payments across Stripe, Adyen and our own TagadaPay processor with one logic, and cascades on decline. Each file is still underwritten, with enhanced review on regulated verticals. Tagada follows Visa and Mastercard rules and the laws that apply to payments.
Frequently asked questions
How does a marketplace payout work?
Who is the merchant of record on a marketplace?
Is a marketplace the same as a payment facilitator?
Do marketplaces report seller payments to tax authorities?
Sources
Checked October 15, 2026- Visa Core Rules and Visa Product and Service Rules, April 18, 2026
- Stripe Docs, Understand how charges work in a Connect integration (read October 14, 2026)
- Adyen Docs, Split transactions in Adyen for Platforms (read October 14, 2026)
- European Commission, VAT e-Commerce One Stop Shop (read October 14, 2026)
- IRS, Understanding your Form 1099-K, updated June 28, 2026
Tagada
Keep more than one processor behind your checkout
Funnels, one-click upsells, subscription billing and payment routing, on one customer record.
- 01Create your free account
- 02Connect your store or build a checkout
- 03Launch funnels, upsells and subscriptions