
What Is Payment Conversion Rate and How Do You Calculate It?
Payment conversion rate formula, how it differs from checkout conversion and authorization rate, where payments are lost, and a worked funnel example.

Article summary
TL;DR
Payment conversion rate is the percentage of payments that succeed out of those your customers start. Formula: successful payments ÷ payment attempts × 100, or successful payments ÷ checkout sessions that reached the payment step × 100. It is wider than authorization rate: it also counts failed 3D Secure, blocked payments and, in the session version, shoppers who quit the payment form.
- Payment conversion rate = successful payments ÷ payment attempts × 100. A wider version divides by checkout sessions that reached the payment step.
- It sits between checkout conversion (all checkouts started) and authorization rate (only attempts the issuer saw). Each has a different denominator.
- Losses happen in three places: the payment form, authentication (3D Secure) and the issuer's decline. Each one has a different fix and a different owner.
- Write down your definition: raw or deduplicated, with or without insufficient-funds declines. The same traffic can show very different rates.
- No card network or regulator publishes a benchmark. Compare your own rate by segment and over time.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
Payment conversion rate tells you how many of the people who try to pay actually pay. It is the payment step's own metric: narrower than your store conversion rate, wider than your authorization rate. This page gives the formulas, how it compares with the metrics it gets confused with, where each loss happens, and a worked example.
What is payment conversion rate?
Payment conversion rate is the percentage of payments started that end in a successful payment. dLocal, a payment provider, puts the question it answers simply: "Out of all payment attempts, how many became successful payments?"3dLocal Help Center, Understanding the Conversion Rate metric, May 25, 2026 Stripe calls the same idea payment success rate.1Stripe Docs, Acceptance analytics (read October 14, 2026)
Two formulas, two denominators
Attempt-based: successful payments ÷ payment attempts × 100
Session-based: successful payments ÷ checkout sessions that reached the payment step × 100
The attempt-based version starts when the customer clicks Pay. It counts failed 3D Secure, payments blocked by fraud rules and issuer declines. Stripe's version divides charges authorized by unique payment attempts and excludes only invalid API calls.1Stripe Docs, Acceptance analytics (read October 14, 2026) The session-based version starts earlier, when the payment form loads, so it also catches shoppers who saw the form and left.
Two choices change the number on the same traffic:
- Raw or deduplicated. A purchase that fails twice and then succeeds is 33.3% raw and 100% deduplicated in Stripe's example.1Stripe Docs, Acceptance analytics (read October 14, 2026)
- With or without insufficient funds. dLocal reports both: 880 approved out of 1,000 attempts is 88% raw, and about 94.6% once its 70 insufficient-funds declines leave the denominator.3dLocal Help Center, Understanding the Conversion Rate metric, May 25, 2026
Adyen warns that providers measure "at what point in the payment flow" they choose, and "the two figures can diverge significantly."5Adyen, Why your payment acceptance rate isn't the full story, July 13, 2026 Write your definition down before you compare anything.
Payment conversion vs checkout conversion vs authorization rate
Four metrics, four denominators. The numerator is the same: successful payments, or paid orders.
| Metric | Formula | Denominator starts at | What it catches |
|---|---|---|---|
| Store conversion rate | Orders ÷ sessions × 100 | Any visit | Traffic quality, product pages, price, checkout and payment together |
| Checkout conversion rate | Orders ÷ checkouts started × 100 | First checkout step | Shipping costs, forms, account creation, plus every payment loss |
| Payment conversion rate | Successful payments ÷ payment attempts (or sessions at the payment step) × 100 | Payment step | Payment form exits (session version), 3D Secure failures, fraud blocks, declines |
| Authorization rate | Approved ÷ attempts sent to the card network × 100 | Authorization request | The issuer's decision only |
Verdict
The later in the funnel the denominator starts, the higher the rate and the narrower the diagnosis.
Checkout conversion is the mirror of checkout abandonment, covered in our guide to checkout abandonment rate. Store conversion has its own playbook in how to increase ecommerce conversion rates. For the issuer side, see authorization rate.
Where payment conversion is lost
Between the payment form and a successful payment, buyers drop out at three points.
- Payment formThe shopper saw the form and never clicked Pay: missing method, too many fields, distrust, a page errorAnalytics: payment step reached vs payment submitted
- Authentication3D Secure challenge abandoned or failed, or the payment blocked by fraud rulesProcessor: challenge rate, challenge success rate, blocks
- Issuer decisionSoft decline (funds, limits) or hard decline (lost card, closed account)Processor: decline codes
Baymard Institute's survey of US online shoppers shows the first and last points from the buyer's side. Leaving out the 42% who were "just browsing", 17% abandoned because the "website had errors / crashed", 10% because "the credit card was declined" and 9% because "there weren't enough payment methods" (page last updated September 22, 2025).4Baymard Institute, Cart abandonment rate statistics (last updated September 22, 2025)
Authentication has its own metrics. Stripe reports a challenge rate (challenges out of all 3D Secure attempts) and a challenge success rate (completed challenges out of challenges). A failed challenge covers both a customer who abandoned and a bank that rejected.2Stripe Docs, Authentication analytics (read October 14, 2026) Wallet payments such as Apple Pay and Google Pay are left out of those reports because they authenticate on the device instead of through 3D Secure.2Stripe Docs, Authentication analytics (read October 14, 2026)
Inside Tagada
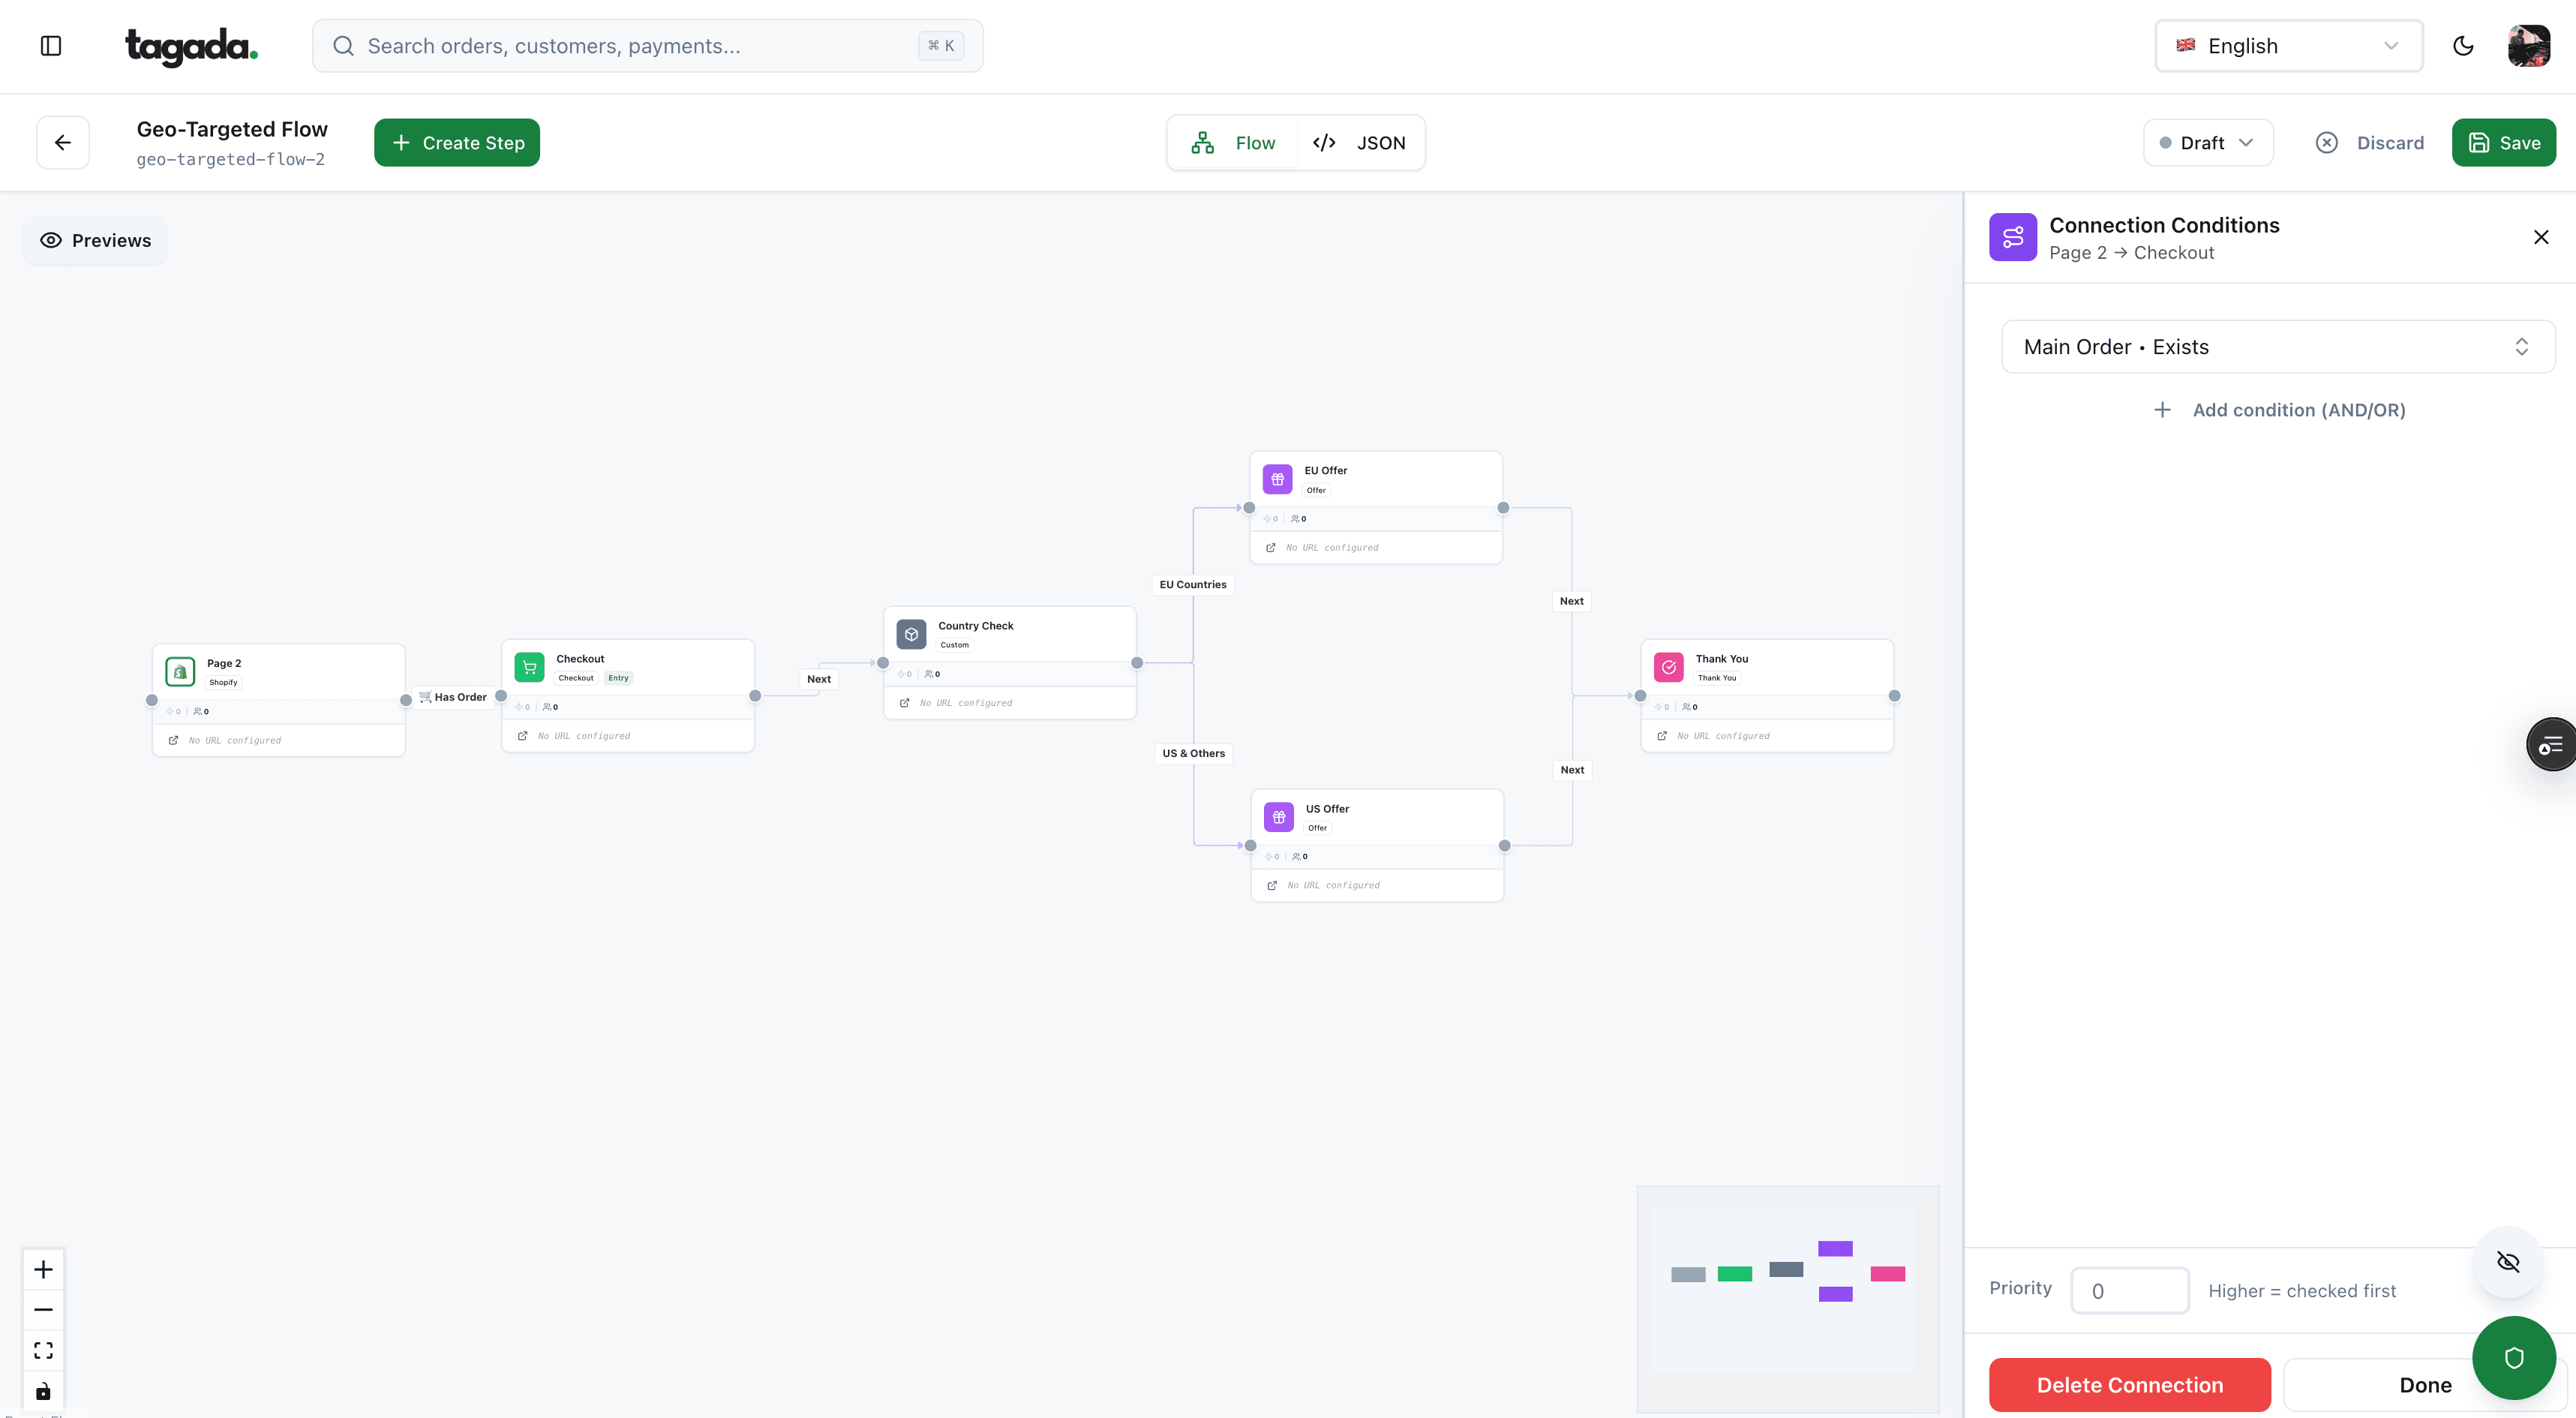
Build the funnel once, route every customer to the right offer
Checkout, upsells and subscriptions on one flow, with conditions per country, order or customer.
Worked example: one month, five rates
An illustrative store, one month, deduplicated attempts.
- 10,000 store sessions, of which 1,200 start checkout.
- 700 reach the payment step. The payment form loads.
- 620 click Pay. 80 leave the payment form without submitting.
- 570 reach the issuer. 20 are blocked by fraud rules and 30 abandon or fail 3D Secure.
- 520 succeed. The issuer declines 50.
Illustrative example. Retried purchases are grouped, so each buyer counts once.
The same 520 payments give five rates:
- Store conversion: 520 ÷ 10,000 = 5.2%
- Checkout conversion: 520 ÷ 1,200 = 43.3%
- Payment conversion, session-based: 520 ÷ 700 = 74.3%
- Payment conversion, attempt-based: 520 ÷ 620 = 83.9%
- Authorization rate: 520 ÷ 570 = 91.2%
Of the 180 buyers lost at the payment step, 80 never clicked Pay, 50 stopped at authentication or a fraud block, and 50 were declined. Each group has a different owner: product for the form, risk for blocks and 3D Secure, payments for declines. Stripe's own worked example shows the same gap between its two rates: 93% payment success rate against 94.9% authorization rate, the difference being 1,000 failed authentications and 1,000 blocked payments.1Stripe Docs, Acceptance analytics (read October 14, 2026)
Recent weeks look worse
If declined payments are still being retried, a deduplicated rate for the last month dips until the retries have run. Stripe flags this in its own reports.1Stripe Docs, Acceptance analytics (read October 14, 2026) Compare complete periods.
What is a good payment conversion rate?
No card network, regulator or processor publishes an official benchmark. The most quoted figure, Baymard's 70.22%, is an average of 50 cart abandonment studies, not a payment metric.4Baymard Institute, Cart abandonment rate statistics (last updated September 22, 2025) Vendor figures use their own definitions, raw or deduplicated, with or without blocks.
What processors do document is which segments usually succeed more. Stripe says domestic cards beat cross-border cards, credit beats debit, debit beats prepaid, and wallets beat typed cards because they are "tokenized and device-authenticated."1Stripe Docs, Acceptance analytics (read October 14, 2026) So segment first: by card country, card type, payment method, device and new versus returning customer. A drop in one segment tells you more than any industry average.
How to improve it
This page is the definition. The fixes live in our guides:
- For the payment form and checkout design, see ecommerce checkout optimization.
- For declines and retries, see payment acceptance rate, plus hard decline and smart retry.
- For authentication, see 3D Secure and our guide to payment authentication.
How Tagada helps
The payment step, in one place
Tagada's checkout supports one-click upsells, order bumps, A/B tests, and Apple Pay and Google Pay. TagadaPay runs native 3DS2, device intelligence and a rules engine. Payments route across TagadaPay and processors such as Stripe, NMI and Airwallex with one logic, with a cascade to another processor when one is down or times out.
Frequently asked questions
What is the payment conversion rate formula?
What is a good checkout conversion rate for ecommerce?
What is the difference between payment conversion rate and authorization rate?
What is the payment conversion index?
Why do some payment flows convert better than others?
How do you measure the impact of payment security on checkout conversion?
Sources
Checked October 15, 2026- Stripe Docs, Acceptance analytics (read October 14, 2026)
- Stripe Docs, Authentication analytics (read October 14, 2026)
- dLocal Help Center, Understanding the Conversion Rate metric, May 25, 2026
- Baymard Institute, Cart abandonment rate statistics (last updated September 22, 2025)
- Adyen, Why your payment acceptance rate isn't the full story, July 13, 2026
- PYMNTS, Checkout Conversion Index (read October 14, 2026)
Tagada
See every payment attempt, from checkout to the issuer
Funnels, one-click upsells, subscription billing and payment routing, on one customer record.
- 01Create your free account
- 02Connect your store or build a checkout
- 03Launch funnels, upsells and subscriptions