What Is Real-Time Gross Settlement (RTGS)?
RTGS meaning: banks settle each payment one by one, in real time. RTGS vs net settlement, Fedwire, T2, CHAPS and India's RTGS, plus benefits and risks.
Article summary
TL;DR
Real-time gross settlement (RTGS) is a way for banks to settle payments one at a time, as soon as each is accepted, for the full amount and without netting. Central banks run most RTGS systems, such as Fedwire in the US, T2 in the euro area, CHAPS in the UK and RTGS in India. Settled payments are final.
- RTGS stands for real-time gross settlement: each payment settles on its own (gross), as soon as it is accepted (real time).
- A settled RTGS payment is final and irrevocable. Fedwire calls its transfers immediate, final and irrevocable once processed.
- The trade-off is liquidity: banks must fund the full amount of every payment, while net settlement only needs the net balance.
- In India, RTGS has a ₹2 lakh minimum, no maximum, and has run 24x7 since December 14, 2020.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
What is real-time gross settlement?
The Committee on Payments and Market Infrastructures at the BIS, which sets the vocabulary central banks use, defines RTGS this way:
The real-time settlement of payments, transfer instructions or other obligations individually on a transaction-by-transaction basis.
"Real time" means no waiting for a batch. "Gross" means each payment settles for its full value, not netted against others. When a bank sends a payment, the system checks it and checks that the sender has enough funds or credit. If it does, the payment settles and is typically unconditional and irrevocable. If not, the payment is queued or rejected.2CPSS-IOSCO, Principles for financial market infrastructures, April 2012 (paragraph 3.8.7, Principle 17 and Annex D)
Most countries run one, usually at the central bank:
| System | Where | What the operator says |
|---|---|---|
| Fedwire Funds | United States | Transfers are "immediate, final, and irrevocable once processed." Open 9:00 p.m. ET the day before to 7:00 p.m. ET.3Federal Reserve Board, Fedwire Funds Services (read October 14, 2026) |
| T2 | Euro area | The Eurosystem's RTGS, launched in March 2023 to replace TARGET2. Settles in central bank money, Monday to Friday.4European Central Bank, T2 (read October 14, 2026) |
| CHAPS | United Kingdom | Run by the Bank of England on its RTGS. About 0.5% of UK payment volumes but 92% of sterling payment values.5Bank of England, A brief introduction to the Real-Time Gross Settlement system and CHAPS (read October 14, 2026) |
| RTGS | India | Run by the RBI. Minimum ₹2,00,000, no maximum, 24x7x365 since December 14, 2020.6Reserve Bank of India, FAQs: Real Time Gross Settlement (RTGS), updated October 31, 2022 (read October 14, 2026) |
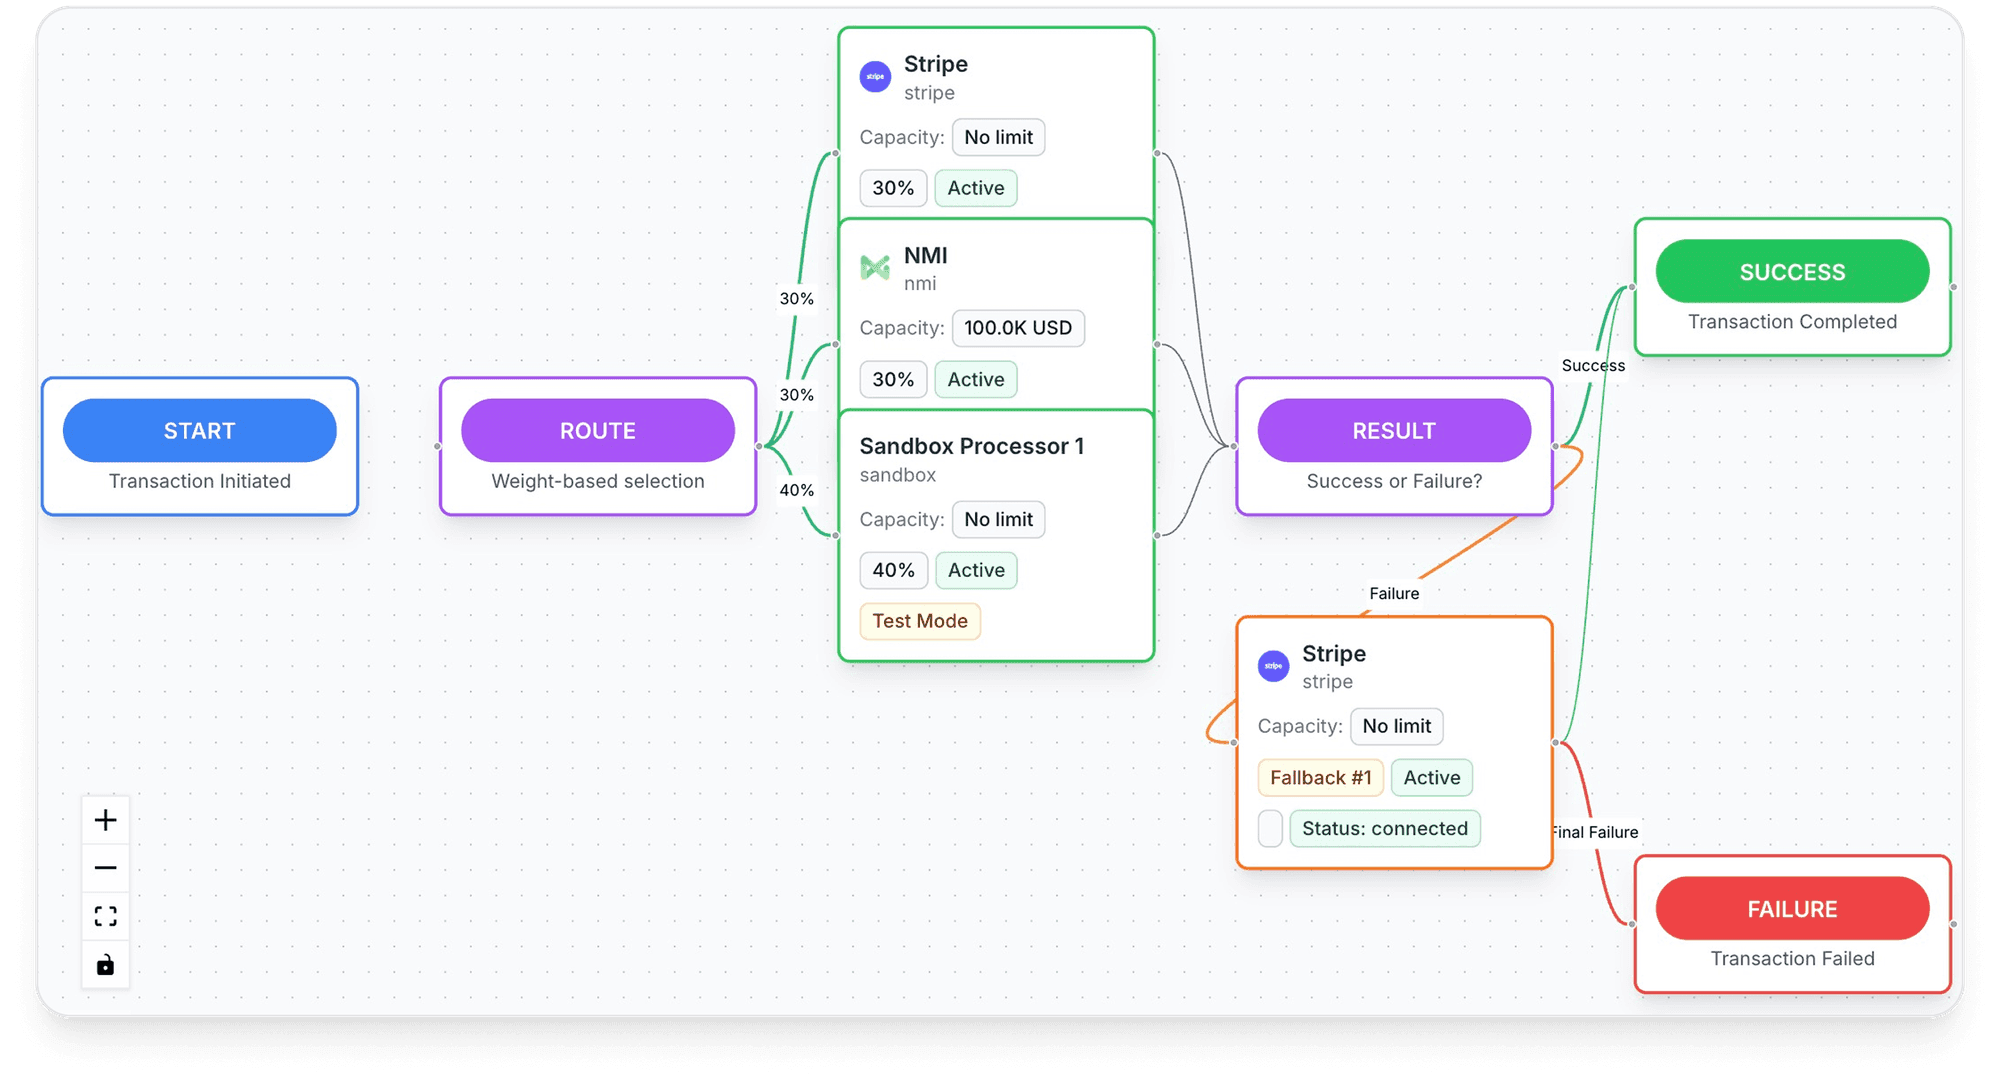
Inside Tagada
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
RTGS vs deferred net settlement
The CPMI defines deferred net settlement (DNS) as settlement "on a net basis at the end of a predefined settlement cycle."1Committee on Payments and Market Infrastructures (BIS), Glossary: real-time gross settlement (RTGS), deferred net settlement (DNS), hybrid system (read October 14, 2026) ACH-type batch systems work this way.
| RTGS | Deferred net settlement | |
|---|---|---|
| Settlement timing | Each payment, continuously during the day | Net balances, at the end of a cycle |
| Liquidity need | High: the full amount of every payment | Much lower: only net positions |
| Settlement risk | Final payment by payment, so little exposure between banks | Credit and liquidity risk until settlement; payments can be unwound if a bank fails |
Source: CPSS-IOSCO, Annex D.2CPSS-IOSCO, Principles for financial market infrastructures, April 2012 (paragraph 3.8.7, Principle 17 and Annex D)
The line is blurring. Many RTGS systems now queue payments and offset them against each other to save liquidity. The CPMI calls these "hybrid" systems.1Committee on Payments and Market Infrastructures (BIS), Glossary: real-time gross settlement (RTGS), deferred net settlement (DNS), hybrid system (read October 14, 2026) CHIPS is a private example of that design.
RTGS is also not only for large payments. The Federal Reserve described FedNow as "a new interbank 24x7x365 real-time gross settlement (RTGS) service with integrated clearing functionality."7Federal Reserve Financial Services, Fed360: Federal Reserve to develop real-time gross settlement service for faster payments, August 15, 2019 It went live on July 20, 2023, for instant payments.8Federal Reserve Board, FedNow Service (read October 14, 2026) For that category, see real-time payments.
Benefits and risks of RTGS
Benefits
- Each payment is final once settled, not at the end of the day
- Less credit and liquidity exposure between banks during the day
- Settlement in central bank money, not a claim on a commercial bank
Risks
- Liquidity risk: banks must fund the full amount of every payment
- Queues and delays when a bank waits for incoming funds
- Operational risk: one central system, so an outage stops payments
International standards say an RTGS system "can therefore require relatively large amounts of intraday liquidity." Banks draw it from central bank balances, incoming payments and intraday credit, and queues or other liquidity-saving tools reduce the need.2CPSS-IOSCO, Principles for financial market infrastructures, April 2012 (paragraph 3.8.7, Principle 17 and Annex D)
For operational risk, Principle 17 asks a payment system to resume critical IT systems "within two hours following disruptive events" and to finish settlement by the end of that day.2CPSS-IOSCO, Principles for financial market infrastructures, April 2012 (paragraph 3.8.7, Principle 17 and Annex D)
For a business, the practical point is finality. An RTGS payment cannot be pulled back like a card payment. In India, the RBI FAQ says the beneficiary bank must credit the account within 30 minutes, or return the funds within one hour if it cannot.6Reserve Bank of India, FAQs: Real Time Gross Settlement (RTGS), updated October 31, 2022 (read October 14, 2026) Check the account details before you send. For how processors move your funds to your bank, see bank payout. For the batch alternative in the US, see our guide to ACH payment processing.
Frequently asked questions
What are the risks associated with RTGS operations?
What is the minimum amount for RTGS in India, and what are the timings?
Is RTGS the same as an instant payment system?
Sources
Checked October 15, 2026- Committee on Payments and Market Infrastructures (BIS), Glossary: real-time gross settlement (RTGS), deferred net settlement (DNS), hybrid system (read October 14, 2026)
- CPSS-IOSCO, Principles for financial market infrastructures, April 2012 (paragraph 3.8.7, Principle 17 and Annex D)
- Federal Reserve Board, Fedwire Funds Services (read October 14, 2026)
- European Central Bank, T2 (read October 14, 2026)
- Bank of England, A brief introduction to the Real-Time Gross Settlement system and CHAPS (read October 14, 2026)
- Reserve Bank of India, FAQs: Real Time Gross Settlement (RTGS), updated October 31, 2022 (read October 14, 2026)
- Federal Reserve Financial Services, Fed360: Federal Reserve to develop real-time gross settlement service for faster payments, August 15, 2019
- Federal Reserve Board, FedNow Service (read October 14, 2026)
TagadaPay
One view of every payment, across every processor
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors