Local Payment Methods by Country, and What Each One Changes
Local payment methods by country: iDEAL, BLIK, Pix, OXXO, SEPA and more, with the refund, dispute and settlement rules from processor docs.
Article summary
TL;DR
Local payment methods are the ways people pay in one country or region: iDEAL | Wero in the Netherlands, Bancontact in Belgium, Cartes Bancaires in France, BLIK and Przelewy24 in Poland, Pix and Boleto in Brazil, OXXO in Mexico, Konbini in Japan, UPI in India, SEPA and ACH debits. Each has its own refund, dispute and settlement rules.
- Pick local methods from your own orders: where customers ship to, and where they leave at the payment step.
- Bank redirects like iDEAL | Wero and Bancontact confirm right away and have no chargebacks at Stripe. Bank debits like SEPA and ACH take days to confirm and have final disputes.
- Vouchers (OXXO, Boleto, Konbini) are paid in cash after checkout. Hold the order until the payment confirms, and plan refunds outside the method.
- Many local methods can't charge a subscription again. Check recurring support before you build a subscription offer around one.
- Each method has its own list of prohibited businesses, on top of your processor's. Read it before you plan a market.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
A local payment method is the way people pay in a given country: iDEAL | Wero in the Netherlands, BLIK in Poland, Pix in Brazil, a cash voucher at an OXXO store in Mexico. Adding one is rarely just another logo at checkout. Each method comes with its own rules on when you know you're paid, how you refund, and whether the customer can claw the money back. This guide goes country by country, with the rules taken from processor documentation, then covers how to choose and what changes in your operations.
What are local payment methods?
Local payment methods are the payment options people use in their own country or region, as opposed to the global card networks. Processors group them into a few families, and the family tells you most of what to expect.1Stripe Docs, Supported payment methods
Local card networks
A domestic card scheme, like Cartes Bancaires in France. Works like a card, with its own dispute rules.
Bank redirects
The customer is sent to their bank or banking app to approve the payment: iDEAL | Wero, Bancontact, BLIK, Przelewy24.
Real-time payments
Account-to-account transfers approved in the bank app, often by QR code: Pix in Brazil, UPI in India.
Bank debits
You pull the money from the customer's account under a mandate: SEPA Direct Debit in the euro area, ACH Direct Debit in the US.
Vouchers
The customer gets a reference and pays in cash or at the bank later: OXXO, Boleto, Konbini, Multibanco.
Buy now, pay later and wallets
Klarna and similar pay you upfront and collect in installments. Wallets like Apple Pay store a card or a balance.
Local methods overlap with alternative payment methods, the wider set of everything that isn't a card. The difference is geography: a local method is tied to a country, and most of its users are there.
Local payment methods by country
The table lists the methods most often asked about, with the rules Stripe publishes for each one. Other processors offer many of the same methods, sometimes with different limits, so check your own provider's page before you plan.
| Country | Method | Family | You know you're paid | Refunds at Stripe | Customer disputes at Stripe |
|---|---|---|---|---|---|
| Netherlands | iDEAL | Wero | Bank redirect | Immediately3Stripe Docs, iDEAL | Wero payments | Up to 180 days | None with the bank |
| Belgium | Bancontact | Bank redirect | Immediately4Stripe Docs, Bancontact payments | Up to 730 days | None through the bank |
| France | Cartes Bancaires | Local card network | Like a card5Stripe Docs, Cartes Bancaires | Full and partial | Can't be contested, 0 EUR fee |
| Poland | BLIK | Bank redirect | Once approved in the bank app6Stripe Docs, BLIK payments | Full and partial | Claims, 12 days to answer |
| Poland | Przelewy24 | Bank redirect | Immediately7Stripe Docs, Przelewy24 payments | Up to 180 days | None through the bank |
| Euro area | SEPA Direct Debit | Bank debit | After about 6 business days8Stripe Docs, SEPA Direct Debit payments | Up to 180 days | 8 weeks no questions asked, final |
| Brazil | Pix | Real-time payment | In real time9Stripe Docs, Pix payments | Up to 90 days | Limited, can't be contested |
| Brazil | Boleto | Voucher | Usually next business day10Stripe Docs, Boleto payments | Not supported | None through the bank |
| Mexico | OXXO | Voucher | By the next business day11Stripe Docs, OXXO payments | Not supported | None through the bank |
| United States | ACH Direct Debit | Bank debit | Up to 4 business days12Stripe Docs, ACH Direct Debit payments | Full only, up to 180 days | 60 days for consumers, final |
| Japan | Konbini | Voucher | When the customer pays13Stripe Docs, Konbini payments | Needs the customer's account details | Generally none |
| India | UPI | Real-time payment | In real time14Stripe Docs, UPI payments | Up to 60 days | Can't be contested |
| Europe, US, Oceania | Klarna | Buy now, pay later | On acceptance, in full15Stripe Docs, Klarna payments | Up to 180 days | Dispute process |
Verdict
The family predicts the behavior. Bank redirects pay fast and rarely come back. Bank debits pay slowly and can come back for weeks. Vouchers pay late, often not at all, and can't be refunded the normal way.
Europe
Netherlands: iDEAL | Wero. iDEAL sends the customer to their own bank to approve the payment, and you know right away whether it went through. All major Dutch banks are members of Currence, which runs it. Customers can't dispute an iDEAL | Wero payment with their bank, so problems come to you directly. The brand is changing: Wero acquired iDEAL, Stripe asked merchants to rebrand to "iDEAL | Wero" in the first quarter of 2026 and to switch to Wero during 2026 and 2027. If you're based in the Netherlands, the scheme rules require your Chamber of Commerce (KVK) number on your website.3Stripe Docs, iDEAL | Wero payments
Belgium: Bancontact. Customers pay with a Bancontact card or the app linked to a Belgian bank account. Because the bank authenticates the payment, Stripe says you won't get disputes that turn into chargebacks. Refunds are possible up to 730 days after the payment. Bancontact doesn't support recurring payments at Stripe.4Stripe Docs, Bancontact payments
France: Cartes Bancaires (CB). France's local card network. Stripe says more than 95% of CB cards are co-badged with Visa or Mastercard, so the same card can go through either network, and businesses in the European Economic Area must let the customer choose the network at checkout. Disputes are where CB differs most: there are fewer reasons a cardholder can dispute, you can't contest a CB dispute, and the dispute fee is 0 EUR at Stripe.5Stripe Docs, Cartes Bancaires
Because Cartes Bancaires dispute rules are more stringent, there are fewer reasons that a cardholder can dispute a charge, which on average leads to a lower dispute rate compared to Visa and Mastercard. Businesses can't contest Cartes Bancaires disputes.
Poland: BLIK and Przelewy24. With BLIK, the customer gets a six-digit code in their banking app, types it at checkout, and approves a push notification. The code is valid for 2 minutes, and the customer has 60 seconds to approve. BLIK has a claims process for fraud, double payments or a wrong amount: you have 12 calendar days to send evidence.6Stripe Docs, BLIK payments Przelewy24 is an aggregator: the customer picks their bank and approves within one hour. Its refunds are always a separate credit to the customer's bank account, never a reversal, and take up to 3 business days.7Stripe Docs, Przelewy24 payments
Euro area: SEPA Direct Debit. You collect the customer's name and IBAN and a mandate, then debit the account. It's the main way to charge euro bank accounts again and again. The trade-off is time: Stripe says to wait at least 6 business days before treating a payment as successful, and customers can dispute any debit for 8 weeks, no questions asked.8Stripe Docs, SEPA Direct Debit payments The timeline is detailed below.
Americas
Brazil: Pix. Stripe describes Pix as a real-time payment system developed by the Central Bank of Brazil. The customer scans a QR code or copies a Pix string into their banking app. A single Pix must be between 0.50 BRL and 3,000 USD. Brazilian customers paying a business based outside Brazil pay a 3.5% IOF tax, which you can pass on or absorb.9Stripe Docs, Pix payments
Brazil: Boleto. A voucher regulated by the Central Bank of Brazil, paid at a bank, ATM, authorized agency or online bank portal. At Stripe, only accounts based in Brazil can accept it. The voucher expires after 3 days by default (configurable up to 60), and payment is confirmed typically on the next business day.10Stripe Docs, Boleto payments
Mexico: OXXO. The customer gets a voucher with a reference number and pays cash at an OXXO convenience store. Vouchers expire after 5 days by default (1 to 7), the amount must be between 10 and 10,000 MXN, and payments can't be refunded through the method.11Stripe Docs, OXXO payments
3 days
Default Boleto voucher expiry, up to 60
5 days
Default OXXO voucher expiry, 1 to 7
3,000 USD
Maximum for a single Pix
10,000 MXN
Maximum for an OXXO payment
United States: ACH Direct Debit. A reusable bank debit that takes up to 4 business days to confirm. Consumers can dispute for up to 60 calendar days, and those disputes are final. More detail in our guide to ACH payment processing.12Stripe Docs, ACH Direct Debit payments
Asia
Japan: Konbini. Customers pay cash at FamilyMart, Lawson, Ministop and Seicomart stores. Amounts run from 120 to 300,000 JPY, only Stripe accounts based in Japan can accept it, and funds are available for payout after 4 business days. Konbini has its own onboarding checks, including a complete disclosure under Japan's Specified Commercial Transactions Act on your site.13Stripe Docs, Konbini payments
India: UPI. A real-time payment system developed by the National Payments Corporation of India, per Stripe. On desktop the customer scans a QR code; on mobile they're sent to their UPI app. Payments run from 1 to 100,000 INR, and recurring payments through UPI AutoPay are capped at 15,000 INR.14Stripe Docs, UPI payments
Across regions: Klarna and other BNPL
Klarna shows the customer options based on their country, currency and the amount: pay in full, pay in 30 days, pay in 3 or 4, or financing. You receive the full amount minus fees upfront, and Klarna carries the loss if the customer doesn't repay. The options and limits change by country: in France, for example, "pay later" runs up to 500 EUR at Stripe.15Stripe Docs, Klarna payments
Refunds and disputes: where local methods differ most
With cards, the rules are familiar: you refund to the card, and a chargeback goes through the card network (the full comparison is in chargeback vs refund). Local methods break that pattern in both directions.
- An OXXO or Boleto customer wants their money backStripe lists no refund support for eitherSet up a separate refund process, such as a bank transfer, and say so in your returns policy
- A Konbini refund doesn't go out right awayThe customer must give account details first; Stripe emails themTell the customer to watch for that email
- You refunded a SEPA or ACH debit, then a bank dispute arrivesA refund doesn't stop a debit dispute: the customer can be credited twiceConfirm the refund with the customer before they go to their bank
- A Pix or UPI dispute is accepted by the bankYou can't contest it; the funds are removed from your balanceKeep delivery proof for your own records and talk to the customer
- A Cartes Bancaires dispute arrivesYou can't contest it, but there's no dispute fee at StripeCheck whether the claim holds and fix the cause
- An iDEAL | Wero, Bancontact or Przelewy24 customer complainsNo bank chargeback: the customer has to come to youMake support easy to reach and refund when they're right
Two details catch teams off guard. First, bank refunds don't look like refunds: Przelewy24, SEPA and ACH refunds appear as a credit referencing your statement descriptor, not as a labeled refund, so tell the customer it's coming.7Stripe Docs, Przelewy24 payments8Stripe Docs, SEPA Direct Debit payments Second, a dispute on a bank debit can switch off the mandate. After an ACH dispute, the mandate is invalid and you need a new one before charging again; after a SEPA dispute, a multi-use mandate may be deactivated.12Stripe Docs, ACH Direct Debit payments8Stripe Docs, SEPA Direct Debit payments
Dispute support also depends on who processes the method, not only on the method. Braintree, for example, states that disputes aren't supported for its local payment methods and that customers must deal with their bank directly.16PayPal Braintree, Local Payment Methods
Inside Tagada
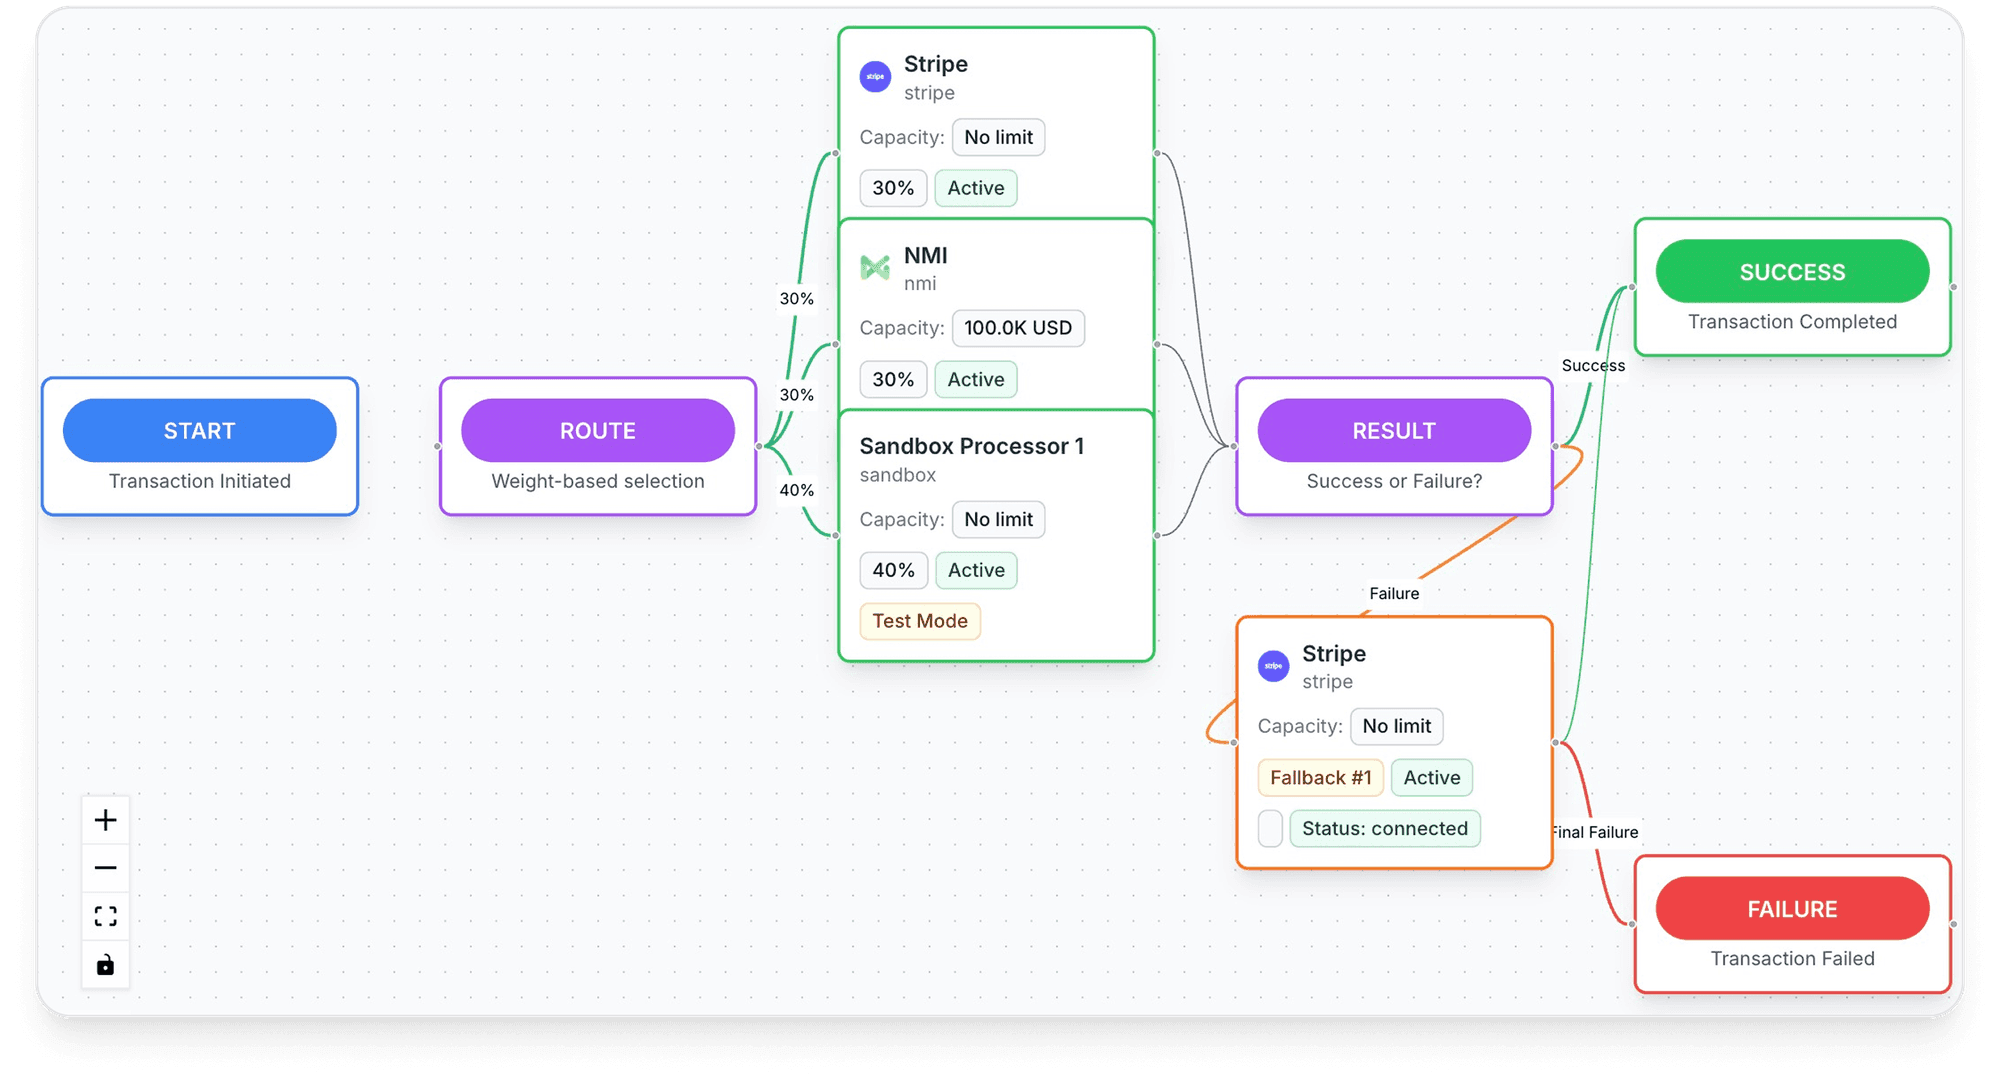
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
Delayed notification: what changes in your operations
Card payments tell you right away whether they worked. Many local methods don't. Stripe's rule is simple: a method with delayed notification can't guarantee payment during the delay, the payment stays in a processing state, and businesses usually hold the order as pending until the success notification arrives.2Stripe Docs, Payment Methods API (immediate or delayed notification)
Fig. 1A SEPA Direct Debit, from checkout to final
- CheckoutIBAN and mandate collected
- SubmissionSame day before 10:30 CET, else next business day
- Refusal window5 business days: most failures happen here
- SuccessT+6: funds available
- Dispute window8 weeks no questions asked, 13 months if unauthorized
Wait 6 business days before shipping on it
Vouchers add a second delay: the customer may never pay. A Boleto voucher expires after 3 days by default, an OXXO voucher after 5.10Stripe Docs, Boleto payments11Stripe Docs, OXXO payments That changes three things in practice:
- Listen for the result. Set up webhooks for the success and failure events instead of reading the checkout redirect. Stripe recommends them for any method that needs a customer action or confirms late.2Stripe Docs, Payment Methods API (immediate or delayed notification)
- Hold the order. Reserve stock and send a "waiting for payment" email with the voucher or the expected date. Ship only on success.
- Plan for silence. Decide what happens when a voucher expires unpaid: release the stock, send one reminder with a new voucher, then cancel.
- Reconcile on settlement, not on order. OXXO payments settle up to 4 business days after the cash payment, SEPA after 6.11Stripe Docs, OXXO payments8Stripe Docs, SEPA Direct Debit payments
The same checklist covers ACH, SEPA, Boleto, OXXO and Konbini.
Which local payment methods work for subscriptions?
A method that works for a one-time order may not be able to charge again. For subscription offers, check recurring support first.
| Method | Can charge again at Stripe | How |
|---|---|---|
| SEPA Direct Debit | Yes | Mandate, debit notice before each payment8Stripe Docs, SEPA Direct Debit payments |
| ACH Direct Debit | Yes | Mandate; 7 days' notice if the debit timing changes12Stripe Docs, ACH Direct Debit payments |
| Cartes Bancaires | Yes | Like any saved card5Stripe Docs, Cartes Bancaires |
| BLIK | Yes | Saved BLIK for off-session payments6Stripe Docs, BLIK payments |
| Pix | Yes | Pix Automático mandate, within the amount the customer approved9Stripe Docs, Pix payments |
| UPI | Yes | UPI AutoPay mandate, up to 15,000 INR14Stripe Docs, UPI payments |
| iDEAL | Wero | Conditional | Renewals run on SEPA Direct Debit set up from the first payment3Stripe Docs, iDEAL | Wero payments |
| Konbini | Conditional | Invoices the customer pays each time, no automatic charge13Stripe Docs, Konbini payments |
| Bancontact | No | One-time only4Stripe Docs, Bancontact payments |
| Przelewy24 | No | One-time only7Stripe Docs, Przelewy24 payments |
| OXXO | No | One-time only11Stripe Docs, OXXO payments |
Bank debits also fail differently from cards on renewal: the failure arrives days later, and Stripe retries a failed SEPA debit at most twice within 30 days, an ACH debit twice within 40 days.8Stripe Docs, SEPA Direct Debit payments12Stripe Docs, ACH Direct Debit payments The details are in our guide to subscription payment failures.
Check eligibility before you plan a market
Your processor's list of restricted businesses is only the first filter. Many local methods add their own, and they often hit the categories that DTC brands sell in.
Method-level restrictions at Stripe
Przelewy24 prohibits dropshipping businesses and several merchant category codes, including 5968 (subscription direct marketing) and 5912 (drug stores).7Stripe Docs, Przelewy24 payments OXXO prohibits 5968, 5122 and 5912.11Stripe Docs, OXXO payments Pix isn't available to telehealth or medicine vendors.9Stripe Docs, Pix payments Konbini excludes sole proprietors with less than 3 years of trading, among others.13Stripe Docs, Konbini payments
Website requirements matter too. Przelewy24 asks for your business address, tax ID, registration number, return policy, privacy policy and terms on the site; iDEAL | Wero asks for your company registration number.7Stripe Docs, Przelewy24 payments3Stripe Docs, iDEAL | Wero payments If you don't know which category code your account carries, our guide to high-risk MCC codes explains how they're assigned.
How to choose which local payment methods to add
There's no universal list. The right methods are the ones your customers use, that your processor offers to your account, and that your operations can handle.
Fig. 2From your orders to a short list
- Your ordersShip-to countries, payment-step exits
- filterProcessor coverageOffered to your account country?
- filterEligibilityMethod's own restricted list
- filterBusiness modelOne-time or subscription, refunds
- testShort listOne or two methods per marketApproved
Start from where your customers are. Look at ship-to countries in your orders and, in your analytics, the countries where shoppers reach the payment step and leave. A market with traffic but weak payment completion is the first candidate.
Check coverage for your account, not just the country. Account location matters: at Stripe, Boleto and Konbini are only open to accounts in Brazil and Japan, while a European or US account can accept Pix or UPI.10Stripe Docs, Boleto payments13Stripe Docs, Konbini payments9Stripe Docs, Pix payments14Stripe Docs, UPI payments
Weigh the trade-offs against your model. A subscription brand gets little from OXXO or Przelewy24, which can't charge again. A brand with frequent returns should think twice before a voucher method it can't refund. Amount limits count too: a 3,000 USD cap on Pix or 10,000 MXN on OXXO is no issue for most carts, but rules out high-ticket orders.9Stripe Docs, Pix payments11Stripe Docs, OXXO payments
Show the right methods to the right people. Methods should appear based on the customer's country and currency, not as a long list for everyone. Stripe, for example, shows Klarna only when the shipping or IP country is supported.15Stripe Docs, Klarna payments Presenting in the local currency also matters: some methods only accept one currency, such as PLN for BLIK or BRL for Pix.6Stripe Docs, BLIK payments9Stripe Docs, Pix payments
Launch one market, then measure. Track for each method: how often it's selected, how many started payments succeed, how many vouchers expire unpaid, refunds and support tickets. Keep what pays, drop what only adds work. Our guide to payment acceptance rate covers how to read success rates.
How Tagada helps
One checkout, several processors
Tagada runs the checkout, with one-click upsells, order bumps, A/B tests, Apple Pay and Google Pay. Payments route across TagadaPay and processors such as Stripe, NMI and Airwallex, with one logic and a cascade to another processor when one is down or times out, and 3D Secure 2 is native. Subscriptions handle trials, billing cycles, dunning and automatic retries. It runs standalone or with Shopify, WooCommerce or a headless store. Pricing is on the pricing page. Tagada follows Visa and Mastercard rules and the laws that apply to payments.
Whatever stack you use, the method is the same: pick local methods from your own order data, read each method's refund, dispute and eligibility rules before you switch it on, and build the pending state into your order flow before the first voucher goes out.
Frequently asked questions
What are local payment methods for global e-commerce?
What's the difference between local and alternative payment methods?
Can customers file a chargeback on a local payment method?
Can you refund an OXXO or Boleto payment?
Which local payment methods work for subscriptions?
How do I know which local payment methods to offer?
Sources
Checked October 14, 2026- Stripe Docs, Supported payment methods
- Stripe Docs, Payment Methods API (immediate or delayed notification)
- Stripe Docs, iDEAL | Wero payments
- Stripe Docs, Bancontact payments
- Stripe Docs, Cartes Bancaires
- Stripe Docs, BLIK payments
- Stripe Docs, Przelewy24 payments
- Stripe Docs, SEPA Direct Debit payments
- Stripe Docs, Pix payments
- Stripe Docs, Boleto payments
- Stripe Docs, OXXO payments
- Stripe Docs, ACH Direct Debit payments
- Stripe Docs, Konbini payments
- Stripe Docs, UPI payments
- Stripe Docs, Klarna payments
- PayPal Braintree, Local Payment Methods
TagadaPay
Selling in several countries? Keep payments in one place
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors