Payment Processor Comparison: Stripe, Adyen, PayPal and More, Side by Side
Stripe, Adyen, PayPal, Braintree, Square, Shopify, Checkout.com and Authorize.net compared on fees, payouts, disputes and risk, from official pages.
Article summary
TL;DR
To compare payment processors, check eight things: pricing model, whether they'll accept your business, payout timing and reserves, dispute fees, payment methods, countries, integrations and support. On a domestic US card, Stripe, Shopify Payments and Braintree all list rates near 2.9% + 30¢. The real differences show up in risk policy, payouts and cross-border fees.
- Headline rates for a domestic US card sit close together. Foreign cards, currency conversion, disputes and payouts make the difference.
- Whether a processor will keep your business matters more than its rate. Read its restricted business list before you apply.
- Payout timing ranges from the next business day at Square to 7 to 14 days for a new Stripe account's first payout.
- Adyen and Checkout.com price on interchange++ or custom terms; Stripe, Square, PayPal and Shopify publish flat rates.
- No public leaderboard ranks processors on fit. Compare them on your own card mix, countries and risk profile.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
A payment processor comparison usually stops at the rate. The rate is the easy part: on a domestic US card, most processors land near 2.9% + 30¢. What separates them is whether they'll accept your business, how fast they pay you, what a dispute costs and how they handle foreign customers. Here are the criteria, then eight processors side by side, built only from their own pages as of October 2026. By industry: fees and reserves for supplement brands, fees and reserves for skincare brands, fees and reserves for online pharmacies, fees and reserves for telehealth companies, fees and reserves for fitness brands and fees and reserves for info product businesses.
How to compare payment processors: 8 criteria
Ask every processor the same eight questions. Most of the answers are on public pages; the rest belong in your sales call.
| Criterion | What to ask | Where to find it |
|---|---|---|
| Pricing model | Flat-rate, interchange-plus or custom? What does a foreign card or a currency conversion add? | Pricing page |
| Approval and risk appetite | Is my product on the restricted list? Will they underwrite a business like mine? | RestrictedOr acceptable use policy |
| Payouts and reserves | How many days from sale to bank? Can they hold a reserve, and on what basis? | Payout docs, reserve FAQ, terms |
| Disputes | Fee per chargeback, fee to respond, returned if you win? | Fee page, dispute docs |
| Payment methods | Apple Pay, Google Pay, PayPal, bank debits, buy now pay later, local methods? | Payment methods page |
| Countries and currencies | Can a business in my country sign up? Which currencies can I charge and settle in? | Global availability page |
| Integrations | Plugin for my store platform? Extra fee if I don't use the platform's own processor? | Integration docs, platform pricing |
| Support and exit | Who answers during an account review? Can I export saved cards if I leave? | Terms, sales call |
The last row is the one most comparisons skip. If your saved cards can't leave with you, switching processors later means asking every subscriber for their card again. How card portability works is covered in what is payment orchestration.
Pricing models: flat-rate, interchange-plus, custom
Processors package the cost of a card payment in one of three ways. The layers underneath (interchange for the customer's bank, network fees, the processor's markup) are explained in what is a transaction fee.
Flat-rate
One published price for every domestic card. Stripe lists 2.9% + 30¢, Square 3.3% + 30¢ online on its free plan, Shopify Payments 2.9% + 30¢ on Basic. Easy to forecast, but a cheap debit card costs you as much as a premium rewards card.
Interchange++
The real interchange and network fees, passed through, plus a markup. Adyen lists Visa and Mastercard at $0.13 + interchange++ + 0.60%. Cheaper when your customers use low-cost cards, dearer on premium cards.
Custom or quoted
No public rate. Checkout.com prices "based on your business profile and risk category" on flat-rate or interchange++ terms. Stripe, PayPal and Braintree also offer custom pricing for larger volumes.
Sources: Stripe, Square, Shopify, Adyen, Checkout.com and Braintree pricing pages.1Stripe, Pricing (United States), October 20268Square, Pricing (US), October 202611Shopify, Pricing (US), October 20265Adyen, Pricing14Checkout.com, Pricing7PayPal Braintree, Fees (US), last updated May 7, 2026 Glossary: flat-rate pricing, interchange-plus pricing. How interchange itself varies by card type is in interchange fees.
Fees compared: 8 processors side by side
Standard US online rates for a card payment, as published by each processor in October 2026. Large merchants negotiate below these.
| Processor | Online card payment | International card | Currency conversion | Monthly fee |
|---|---|---|---|---|
 Stripe | 2.9% + 30¢ | +1.5% | +1% | None listed |
 Adyen | $0.13 + interchange++ + 0.60% (Visa, Mastercard) | Included in interchange | Not listed | None, but a minimum invoice by industry |
 PayPal | 2.99% + 49¢ (standard card payments); 3.49% + 49¢ (PayPal Checkout) | +1.5% | 3% spread | None listed |
| Braintree | 2.89% + 29¢ (cards and digital wallets) | +1% | +1% | None listed |
| Square | 3.3% + 30¢ (free plan, online checkout) | Not listed | Not listed | Free plan; paid plans lower the online rate to 2.9% + 30¢ |
 Shopify Payments | 2.9% + 30¢ (Basic) down to 2.25% + 30¢ (Plus) | +1% | 1.5% for US stores | Your Shopify plan |
 Checkout.com | Quoted (flat-rate or interchange++) | Quoted | Quoted | "No account maintenance fees" |
| Authorize.net | 2.9% + 30¢ (all-in-one plan) or 10¢ + 10¢ daily batch (gateway only) | Not listed | Not listed | $25 |
Verdict
On a domestic card, published rates sit within a few tenths of a point of each other. Foreign cards, currency conversion, a monthly fee or a minimum invoice change the total more than the headline rate does. Price every offer on your own transactions.
Stripe's figures are its standard US pricing.1Stripe, Pricing (United States), October 2026 Adyen's are indicative, with no monthly, setup or closure fees, but a minimum invoice that depends on industry.5Adyen, Pricing PayPal's come from its US fee page, last updated October 1, 2026.6PayPal, Merchant and business fees (US), updated October 1, 2026 Braintree's from the PayPal Braintree fee page, last updated May 7, 2026; it adds that custom flat rates and interchange-plus are available to established businesses.7PayPal Braintree, Fees (US), last updated May 7, 2026 Square's are for its free plan.8Square, Pricing (US), October 2026 Shopify Payments rates depend on your Shopify plan, and premium cards cost 3.5% + 30¢ on Basic.11Shopify, Pricing (US), October 2026 Checkout.com publishes no rates.14Checkout.com, Pricing Authorize.net's all-in-one rate is "subject to eligibility"; its gateway-only plan connects to a merchant account you already have, which charges its own rate.15Authorize.net, Pricing
Payouts and reserves: when you get your money
A cheap rate paid out late can cost more than a higher rate paid out fast, especially if you buy inventory or ads on credit. Two things decide it: the payout schedule, and whether the processor holds part of your balance.
Fig. 1From sale to bank account
- Next business daySquare, for payments taken before 5 PM PT
- 2 business daysStripe's listed settlement timing for the US
- 7 to 14 daysStripe's first payout after your first live payment
- Your choiceAdyen: you choose when, and in which currency, to settle
the first payout is the slowest
Square sends payments taken before 5 PM PT to your bank the next business day; instant and same-day transfers cost 1.95% per transfer.9Square Support Center (US), Transfer limits and processing times Stripe schedules a new account's first payout within 7 to 14 days, "depending on your industry, country of operation, and risk level," then pays daily, weekly or monthly.2Stripe Docs, Payouts Adyen lets you link bank accounts in several currencies, so you don't always have to convert before settling.5Adyen, Pricing Shopify Payments sets payout timing by country and account; check the payout schedule in your admin.
Reserves are the bigger risk. A processor that sees more risk in your business keeps part of your balance to cover future refunds and disputes. Stripe says it weighs industry conditions, payment activity, dispute rate, refund rate and financial stability when it sizes a reserve.16Stripe Support, Reserves FAQ Ask every processor, before you sign, under which conditions it can apply one. How reserves work and how to plan cash for them is in payment risk management and the glossary entry for rolling reserve.
Dispute fees and tools
Every chargeback takes the order amount from your balance. On top of that, most processors charge a fee.
- Stripe$15 when the dispute arrives, plus $15 if you respondThe response fee is returned if you win; the first fee isn't, except in Mexico
- Shopify Payments$15Returned if you win
- Braintree$15 per card chargeback$5 for an ACH dispute filed as unauthorized
- PayPal$20 per card chargebackPayPal's own disputes: $15 standard, $30 for high dispute volume
- SquareNo fee for dispute managementDisputed funds are held right away; processing fees aren't returned if you lose
- Authorize.net$0 on its gateway fee scheduleOn the gateway-only plan, your merchant account provider sets its own fee
Sources: Stripe, Shopify, PayPal, Braintree, Square and Authorize.net, October 2026.4Stripe Support, June 2025 pricing updates for disputes12Shopify Help Center, Overview of the chargeback and inquiry process6PayPal, Merchant and business fees (US), updated October 1, 20267PayPal Braintree, Fees (US), last updated May 7, 202610Square Support Center (US), How payment disputes work15Authorize.net, Pricing Adyen and Checkout.com don't list a dispute fee on their pricing pages; ask for it in writing. The full breakdown by country is in chargeback fees.
Fees are only half of it. Compare the tools too: dispute alerts that let you refund before a chargeback is filed, evidence submission from the dashboard, and how the processor reports your dispute ratio against the Visa and Mastercard thresholds. Those thresholds, and how to stay under them, are in chargeback prevention.
Approval and risk appetite: will they keep your business?
A processor that closes your account three months in is the most expensive one on the list. Each processor publishes what it won't accept: Stripe in its Prohibited and Restricted Businesses list,17Stripe, Prohibited and Restricted Businesses PayPal in its Acceptable Use Policy, Shopify Payments in its terms. The lists differ, and some categories are allowed only with prior approval.
- Read the restricted list against your catalog. Not only your main product: one add-on in a restricted category can be enough for a review.
- Check how they underwrite. Instant sign-up on a shared account, or a review of your business before you can process? Ask what documents they want.
- Ask about reserves and payout holds. In which situations, what percentage, for how long.
- Ask what happens in a review. Who contacts you, how long payouts can be paused, how you can export your data.
- Find your MCC. It decides how card networks and acquirers see you. See high-risk MCC codes and how to find your MCC code.
Do this for each processor before you apply. Your MCC, the code that classifies your business, follows you into every application.
Instant sign-up and long-term acceptance are different things. Providers that sign you on an aggregated account, like Stripe, let you start quickly and review you as you process. A dedicated merchant account takes longer to open but gives you your own terms. The difference is explained in payment service provider and in the glossary entry for underwriting.
Inside Tagada
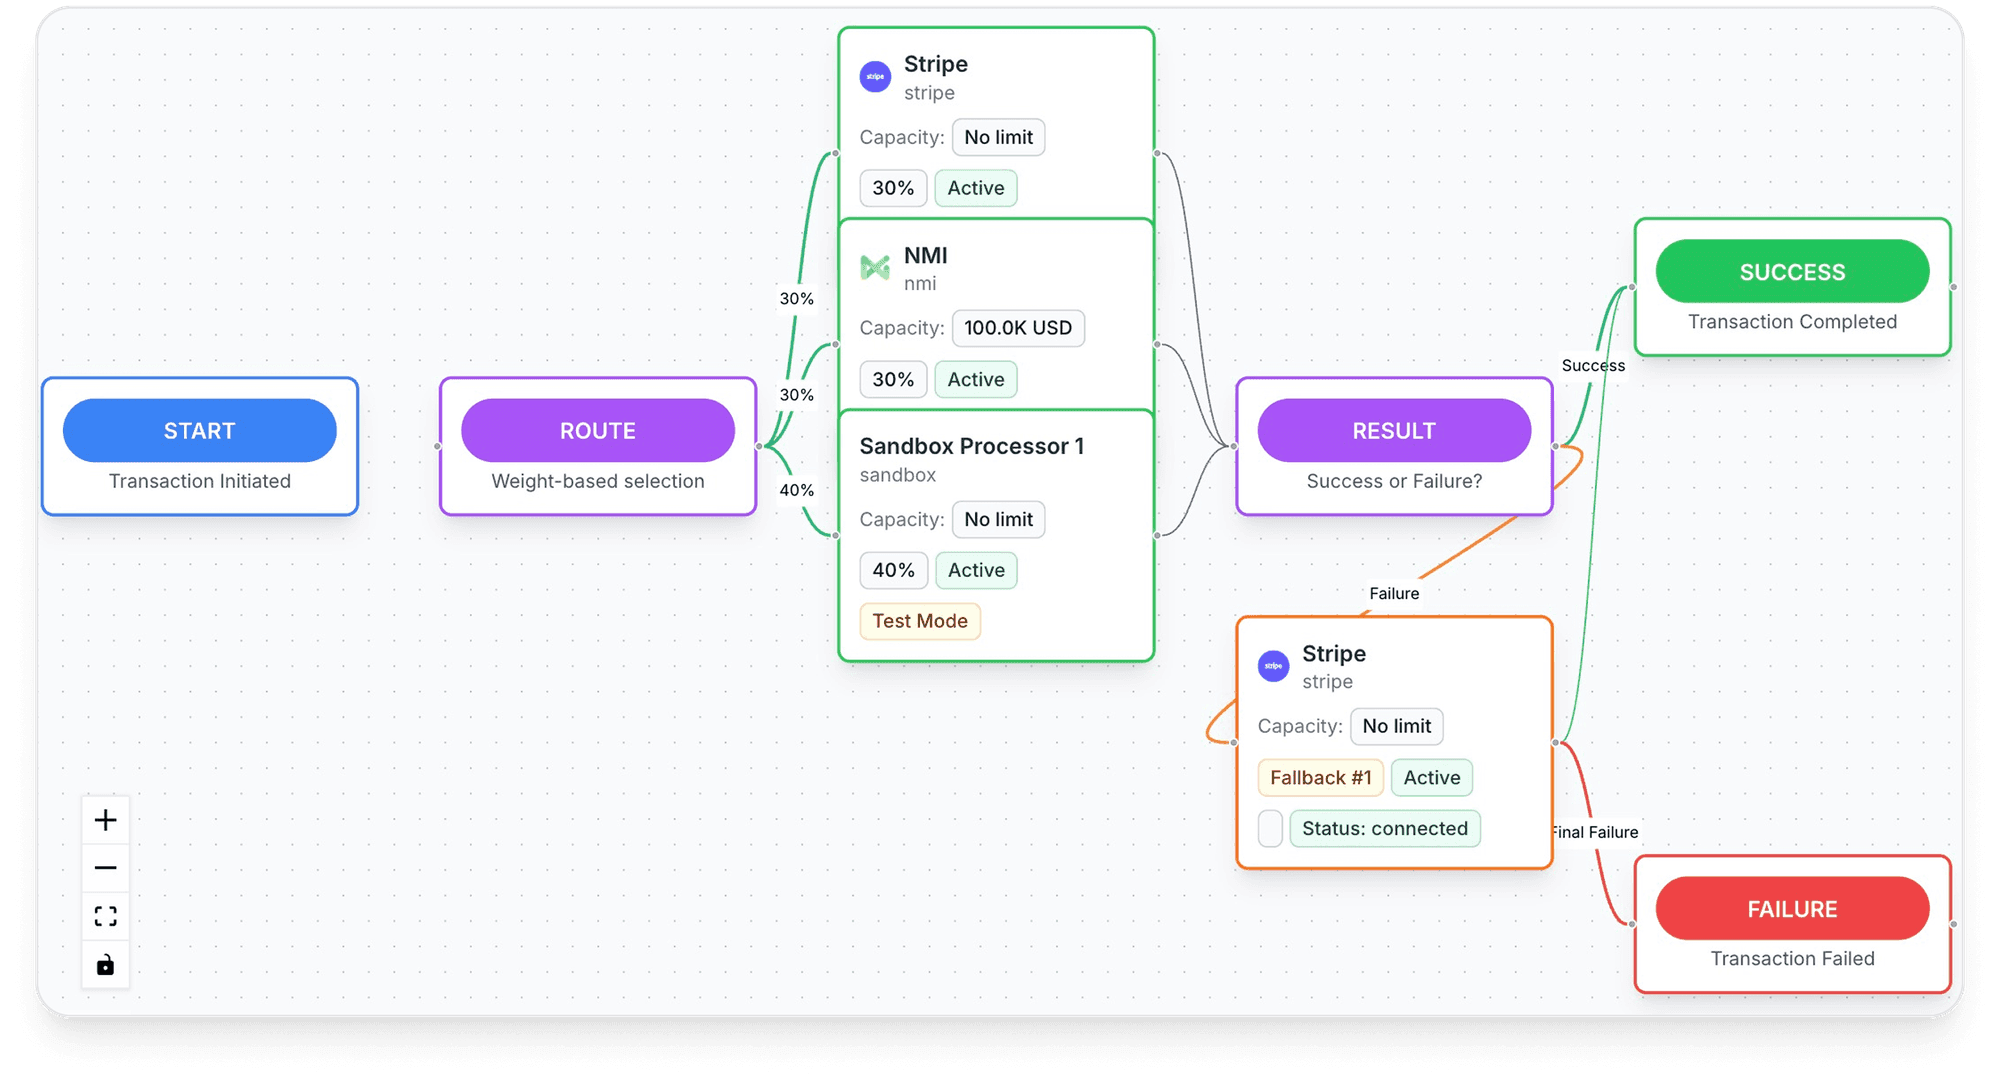
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
Payment methods, countries and mobile checkout
The processor you choose limits what your customers can pay with and where you can sell.
125+
Payment methods Stripe says you can access
44
Countries where a business can sign up to Stripe directly, out of 51 listed
41
Countries where a business can use Shopify Payments
Stripe's global page lists 51 countries and regions; India and Indonesia are in preview through sales, and five African countries go through Paystack.3Stripe, Global availability Shopify Payments is available to businesses in 41 countries, from Australia to the United States.13Shopify Help Center, Supported countries for Shopify Payments Adyen and Checkout.com don't publish a count on their pricing pages; ask for coverage in your target markets, including local acquiring.
On mobile, payment methods matter more than the processor's name. Typing a 16-digit card number on a phone is where many checkouts are lost. When you compare processors for mobile conversion, check:
- Wallets on your checkout: Apple Pay and Google Pay let customers pay without typing a card. Confirm the processor supports them on your store platform, not only in its own hosted page. See digital wallet.
- Saved cards and one-click repeat purchases: whether returning customers can pay without re-entering details. See saved payment methods.
- Local methods: bank debits and regional wallets in the countries you sell to. See local payment methods.
- Authentication flow: with 3D Secure 2, the customer's bank can approve many payments without showing a challenge screen. Check how the processor handles it on mobile. See payment authentication.
Checkout design itself (fields, steps, page speed) is in ecommerce checkout optimization.
Integrations: which processor fits your store
| You sell on | What to know | Where it bites |
|---|---|---|
| Shopify | Shopify Payments is built in. Using another provider adds a Shopify fee of 2% (Basic) down to 0.2% (Plus) on top of that provider's rate | A cheaper external processor can end up costing more |
| WooCommerce or another open platform | Most processors offer an official or partner plugin; check who maintains it | You keep the plugin updated |
| Headless or custom checkout | Every processor here has an API | Development time, and PCI scope if card data touches your servers |
| Several stores or brands | Each processor signs each business on its own terms and MCC | Separate accounts, dashboards and payouts to reconcile |
Source for the Shopify fee: Shopify pricing.11Shopify, Pricing (US), October 2026 Gateway or processor, and which one you actually need, is explained in payment gateway vs payment processor.
Which processor fits which business
There's no single winner. Each processor's own pages say who it's built for. Here is how they line up by situation, without a ranking. For a fuller pick by use case, see our guide to the best payment processors for ecommerce.
Published flat rates, fast start
- Stripe: online-first, wide method and country coverage, API and no-code options
- Square: in-person and online on one account, next-business-day payouts
- Shopify Payments: built into Shopify, no extra Shopify fee
- PayPal and Braintree: PayPal and Venmo for buyers who prefer them
Quoted terms, more setup
- Adyen: interchange++ pricing with a minimum invoice, multi-currency settlement
- Checkout.com: custom pricing by business profile and risk category
- Authorize.net: a gateway that connects to your own merchant account
- Any of them, on custom pricing once your volume justifies it
The column you land in depends on your volume and how much payments work you can take on. A store doing its first sales gains little from negotiating interchange++. A brand selling in ten countries gains little from a processor that can't settle in local currencies.
Is there a payment processing leaderboard?
Not one that ranks processors on what matters to you. Published rankings usually measure size, like payment volume, or come from vendors and review sites with their own scoring. Size says nothing about whether a processor will accept your category, how fast it pays out or how many of your customers' cards it approves.
Compare on approved payments, not attempted ones
A lower rate on a declined payment saves nothing. Run the same month of transactions through each offer, and compare the cost per approved payment. If you already use two processors, compare their acceptance rates on comparable traffic: same countries, same card types, same order sizes.
One processor or several?
Most stores start with one processor. It's simpler, and it's the right call until one account carries most of your revenue. Then a single review, reserve or outage stops checkout and subscription renewals at the same time.
Fig. 2Same failed payment, two setups
One processor
- CheckoutCustomer pays
- sends toProcessor ATimeout, or account under reviewDeclined
The order is lost, or the customer tries another card
Two processors with routing
- CheckoutCustomer pays
- sends toProcessor ATimeout, or account under reviewDeclined
- falls through toProcessor BApprovedApproved
A processor failure goes to the second processor
the second processor is insurance and a lever
A second processor adds its own underwriting, fees and dispute handling. It pays off when an account review would stop most of your sales, when you sell in several countries, or when subscriptions are a large share of revenue. Which declines you're allowed to retry, and where, is in dynamic payment routing. The layer that connects several processors to one checkout is described in what is payment orchestration.
What is TagadaPay?
TagadaPay is Tagada's own payment processor. It is one of the processors you can route to from Tagada, next to processors such as Stripe, NMI and Airwallex, and each business that applies is underwritten.
How Tagada helps
TagadaPay and Tagada's routing, in short
Tagada routes payments across TagadaPay and processors such as Stripe, NMI and Airwallex, with one logic, and cascades to another processor when one is down or times out. Its card vault lets you switch processors without re-onboarding customers, so running subscriptions keep charging. 3D Secure 2 is native, with device intelligence and a rules engine. It works standalone or with Shopify, WooCommerce or a headless store. TagadaPay still underwrites each business. Pricing is on the pricing page; payments are presented on the payments page. Tagada follows Visa and Mastercard rules and the laws that apply to payments.
Reviews. As with any processor, read recent reviews from businesses like yours, then read the terms and the restricted list before you apply.
A TagadaPay charge on your card. TagadaPay processes payments for online stores. If you see a charge that mentions it, look for an order confirmation from a store you bought from around that date and contact the store first. If you don't recognize the purchase, contact the bank that issued your card.
Frequently asked questions
How do I compare payment processors?
Which payment processor has the lowest fees?
Is there a payment processing leaderboard?
What is TagadaPay?
Where can I read Tagada Pay reviews?
I see a TagadaPay charge on my card statement. What is it?
Sources
Checked October 14, 2026- Stripe, Pricing (United States), October 2026
- Stripe Docs, Payouts
- Stripe, Global availability
- Stripe Support, June 2025 pricing updates for disputes
- Adyen, Pricing
- PayPal, Merchant and business fees (US), updated October 1, 2026
- PayPal Braintree, Fees (US), last updated May 7, 2026
- Square, Pricing (US), October 2026
- Square Support Center (US), Transfer limits and processing times
- Square Support Center (US), How payment disputes work
- Shopify, Pricing (US), October 2026
- Shopify Help Center, Overview of the chargeback and inquiry process
- Shopify Help Center, Supported countries for Shopify Payments
- Checkout.com, Pricing
- Authorize.net, Pricing
- Stripe Support, Reserves FAQ
- Stripe, Prohibited and Restricted Businesses
TagadaPay
Comparing processors? Keep more than one, and route between them
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors