What Is an Acquirer in Payments?
Acquirer meaning: Visa's definition, acquirer vs issuer, what an acquiring bank does for a merchant, who pays unpaid chargebacks, and acquirer aggregation.
Article summary
TL;DR
An acquirer is the bank or licensed payment institution on the merchant's side of a card payment. It signs the merchant, sends its transactions through Visa or Mastercard to the cardholder's bank and pays the merchant. The issuer is the other side: the bank that gave the shopper the card. The acquirer answers to the network for its merchants.
- Visa defines an acquirer as a member that signs a merchant or payment facilitator and enters transactions into interchange.
- The issuer serves the cardholder; the acquirer serves the merchant. The card network sits between them.
- Each step, from underwriting to settlement and disputes, sits with the acquirer, even when a processor does the technical work.
- If a merchant cannot pay its chargebacks, the acquiring bank must pay the issuer, according to the OCC.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
Every card payment has two banks behind it: one for the shopper, one for the store. The acquirer is the store's side. This page defines it, compares it with the issuer, and points to the pages that explain each part of its job.
What is an acquirer?
Visa's rulebook gives the definition. Outside Europe, an acquirer is:1Visa Core Rules and Visa Product and Service Rules, April 18, 2026
A Member that signs a Merchant or Payment Facilitator, provides a Cash Disbursement to a Cardholder, or loads funds to a Prepaid Card, and directly or indirectly enters a Transaction into Interchange.
A "Member" is a client of Visa that meets its membership requirements, usually a bank. In Europe, the definition centers on the agreement with the merchant to accept Visa. In practice, the acquirer is also called the acquiring bank or merchant acquirer.
| Acquirer | Issuer | |
|---|---|---|
| Works for | The merchant | The cardholder |
| Visa definition | Signs a merchant and enters its transactions into interchange | "enters into a contractual relationship with a Cardholder for the issuance of one or more Card products" |
| In a payment | Sends the request, receives funds, pays the merchant | Approves or declines, debits or bills the cardholder |
| In a dispute | Passes the chargeback to the merchant | Raises the chargeback for the cardholder |
Source: Visa Core Rules, April 2026, Glossary.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026
Inside Tagada
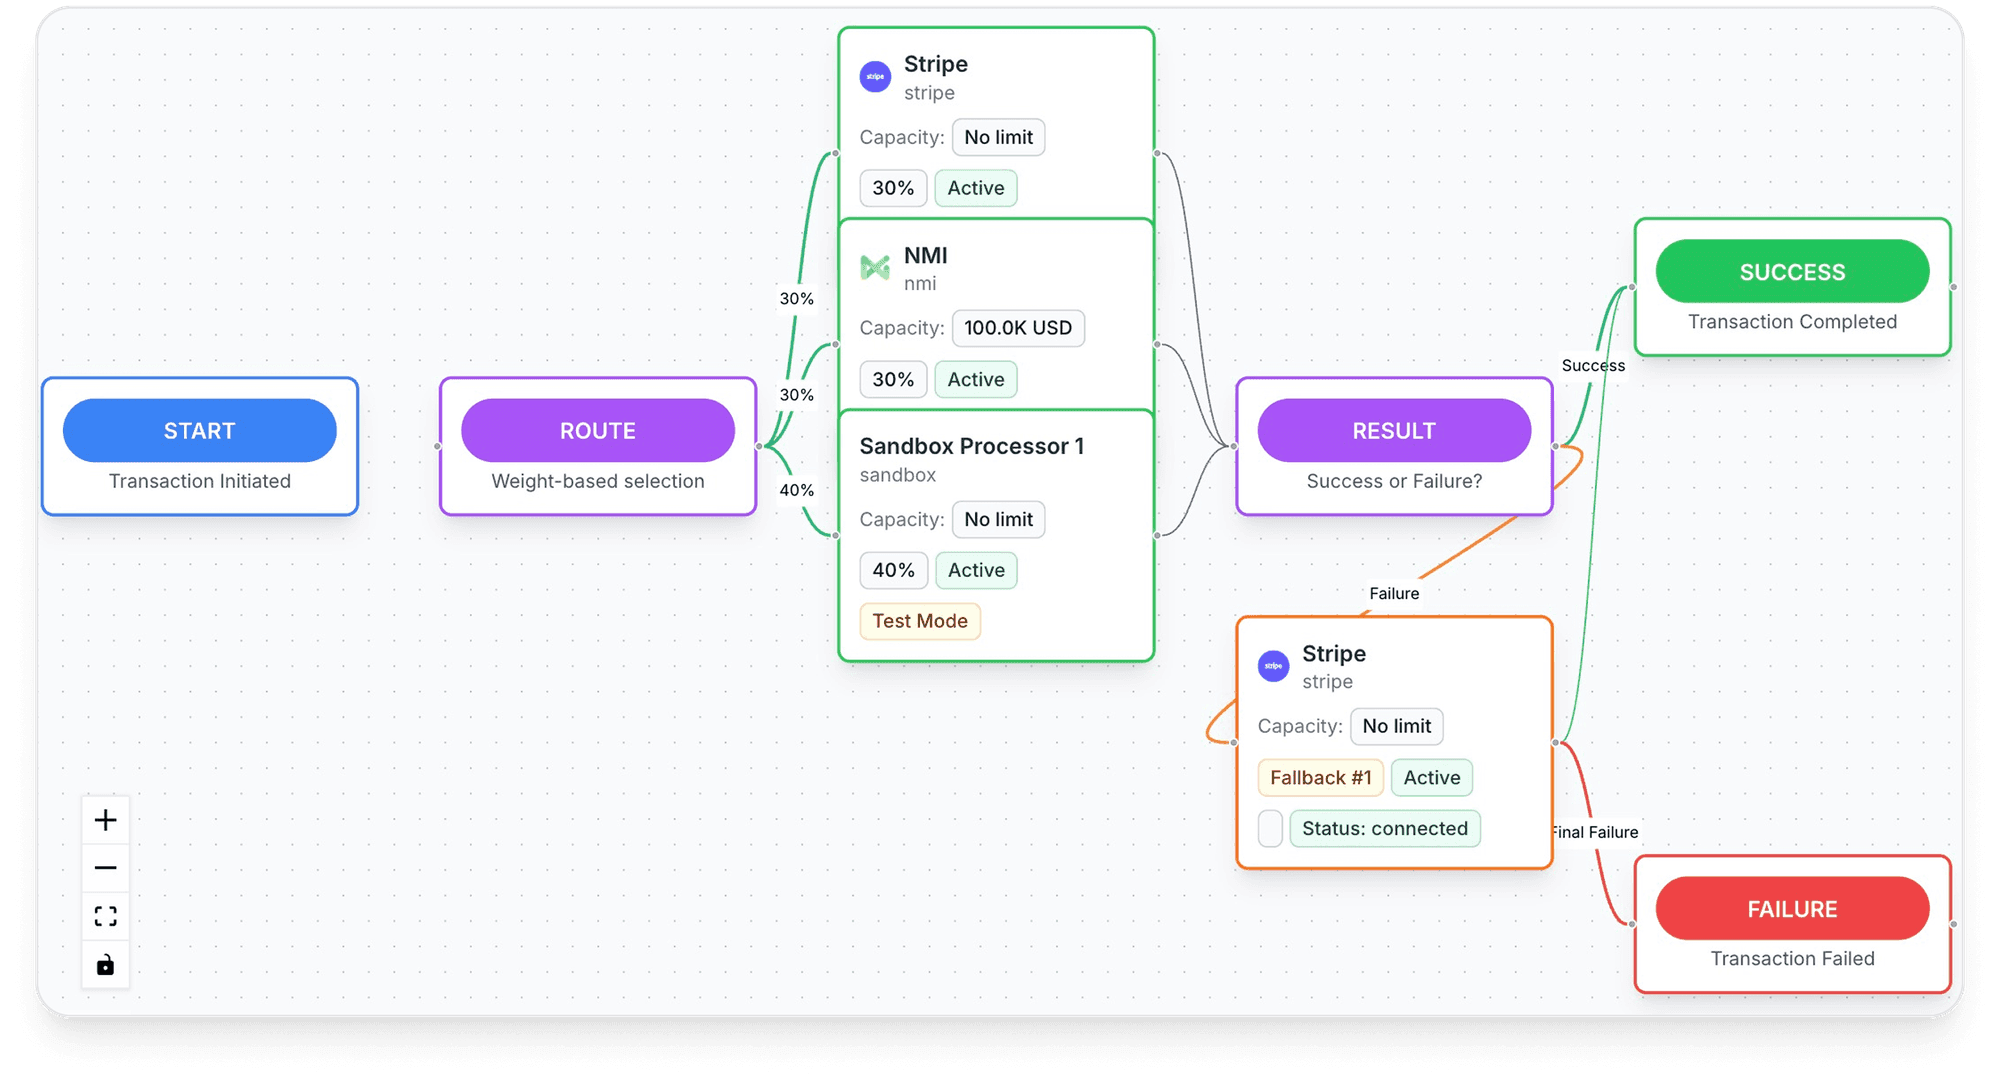
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
What an acquirer does for a merchant
- Signs and vets the merchant. This is underwriting, and it opens a merchant account.
- Sends authorizations and clearing records to the network, itself or through a processor. See acquirer processing.
- Settles funds and pays the merchant. The full flow, with the EU and US rules, is in card acquiring.
- Tracks each payment with an acquirer reference number, useful for refunds and disputes.
- Handles chargebacks raised by the issuer.
An acquirer in the shopper's own country is a local acquirer.
Acquirer liability for chargebacks
The acquirer cannot hand its risk to the merchant or the processor. Visa section 1.1.8.1 says each member "is solely responsible for its issuance of Visa products and acquiring of Merchants", including settlement.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 The US bank regulator, the OCC, spells out the money side: "If a merchant or ISO/MSP cannot honor its charge-backs, the acquiring bank must pay the card-issuing bank" (page 14).2OCC, Comptroller's Handbook, Merchant Processing, Version 1.0, August 2014 (read October 14, 2026)
That is why acquirers underwrite carefully and watch dispute levels. How that work is split with processors is covered in acquirer processing. For working with several acquirers at once, see our guide to payment orchestration.
How Tagada helps
Several acquirers, one checkout
Route across TagadaPay and processors such as Stripe, NMI and Airwallex with one logic. Cascade to another processor when one is down or times out. Each file is still underwritten, with enhanced review on regulated verticals. Tagada follows Visa and Mastercard rules and the laws that apply to payments.
Frequently asked questions
What is acquirer aggregation?
Is an acquirer the same as a payment processor?
Can a merchant use more than one acquirer?
Sources
Checked October 15, 2026TagadaPay
Route payments across several acquirers
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors