What Is Concentration Risk?
Concentration risk meaning from the OCC, its 6 types (credit, sector, deposit, supplier, merchant), and how it hits acquirers and online merchants.
Article summary
TL;DR
Concentration risk is the risk of a large loss because too much of your exposure depends on one source: one borrower, one industry, one supplier or one payment processor. The US bank regulator OCC treats a credit concentration as obligations above 25% of a bank's tier 1 capital plus its credit loss allowance. In payments, it hits acquirers and merchants.
- The OCC defines a concentration as direct, indirect or contingent obligations above 25% of tier 1 capital plus the allowance for credit losses.
- The risk comes from exposures that perform alike: one borrower, one industry, one region, one funding source or one supplier.
- Acquiring banks track merchant concentration: the share of their sales volume coming from high-risk merchants, one industry or a few large merchants.
- For an online store, the same risk is one processor carrying all sales. A review, a payout hold or an outage stops checkout and renewals at once.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
Concentration risk is a banking term that now applies to any business. This page gives the regulator's definition, the main types, and what it means on both sides of a card payment: the acquiring bank and the online merchant.
What is concentration risk?
Concentration risk is the risk of a large loss because many exposures depend on the same thing. The OCC, which supervises US national banks, gives a precise test: "A concentration is defined as the sum of direct, indirect, or contingent obligations exceeding 25 percent of a bank's tier 1 capital plus the allowance for credit losses (ACL)."1OCC, Comptroller's Handbook: Concentrations of Credit, Version 3.0, September 2026 (read October 14, 2026)
The danger is not one bad loan. The OCC explains that large groups of transactions that perform similarly can hurt a bank "even when each transaction within a pool is soundly underwritten."1OCC, Comptroller's Handbook: Concentrations of Credit, Version 3.0, September 2026 (read October 14, 2026) It also names non-credit concentrations, such as "liquidity risk due to funding concentrations."1OCC, Comptroller's Handbook: Concentrations of Credit, Version 3.0, September 2026 (read October 14, 2026)
Deposit concentration has a depositor side too: FDIC insurance covers "$250,000 per depositor, per FDIC-insured bank, for each account ownership category."3FDIC, Understanding Deposit Insurance (read October 14, 2026) Money above that at one bank is uninsured.
Supplier concentration is written into EU law for financial firms. DORA defines ICT concentration risk as exposure to one or several related critical technology providers whose failure could endanger the firm's critical functions (Article 3(29)). Before signing, firms must check whether they would rely on a provider "not easily substitutable" (Article 29).4Regulation (EU) 2022/2554 on digital operational resilience for the financial sector (DORA), Articles 3(29) and 29
Inside Tagada
See every payment's route, processor by processor
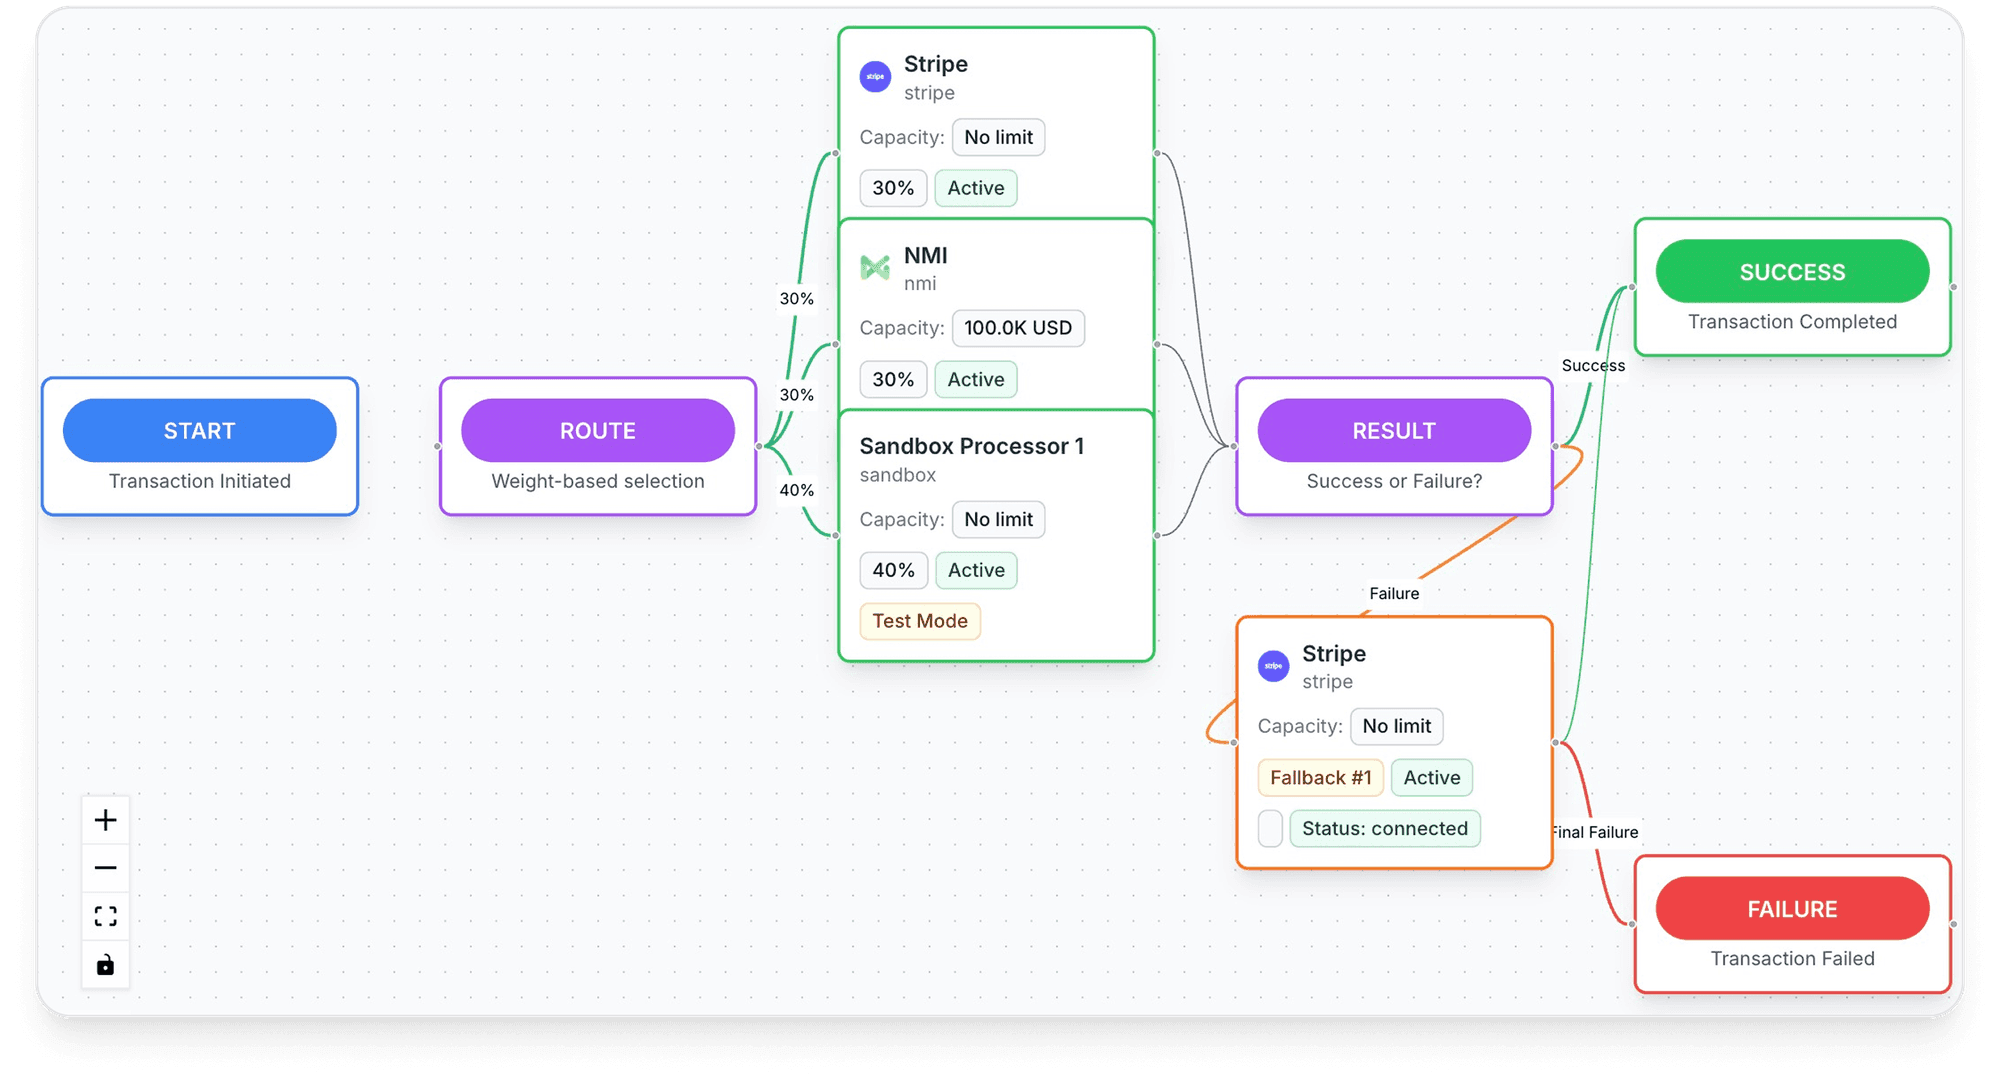
Set the order your processors are tried in, per store, per country or per product.
Merchant concentration: the acquirer's side
An acquiring bank carries the loss if a merchant can't cover its chargebacks, so it watches where its volume comes from. The OCC's Merchant Processing handbook says card networks have rules limiting "concentrations of high-risk merchants," and gives the measure: the "proportion of aggregate merchant sales volume comprising merchants in high-risk merchant activities." The bank may set its own target maximum for it.2OCC, Comptroller's Handbook: Merchant Processing, Version 1.0 (August 2014, updated March 20, 2025)
Examiners check whether a portfolio has "concentration risk by industry, merchant segment, or individual merchant," and whether the board has approved limits "by industry and large merchants in relation to capital, earnings, and sales volumes."2OCC, Comptroller's Handbook: Merchant Processing, Version 1.0 (August 2014, updated March 20, 2025) So a bank near its limit for one industry has less room for new merchants in it. This is one reason underwriting varies between acquirers. For who does what on that side, see acquirer processing.
Processor concentration: the merchant's side
For an online store, concentration risk usually means one processor carrying all sales. Each event below then hits everything at once:
| Event | One processor | Several processors, one checkout |
|---|---|---|
| Account review or closure | Checkout and renewals stop | Traffic moves to another account |
| Payout hold | All incoming money is held | Only one account's balance is held |
| Outage or decline spike | Every order is exposed | Declined payments can retry elsewhere |
Holds can be long. When Stripe stops working with an account under its Unacceptable Risk Policy, it "will typically restrict or pause payouts to the User's bank account for 120 days."5Stripe, Unacceptable Risk Policy (read October 14, 2026)
The fix is a second processor that is live before you need it, plus rules that decide where each payment goes. That is the job of payment orchestration, and cascading payments send a payment the first processor couldn't complete to another one. For the full guide, see payment risk management.
How Tagada helps
One checkout, more than one processor
Tagada routes payments across TagadaPay and processors such as Stripe, NMI and Airwallex with one logic, and cascades to another processor when one is down or times out. Each file is still underwritten, with enhanced review on regulated verticals.
Frequently asked questions
What is concentration risk in business?
What is supplier or vendor concentration risk?
What is deposit concentration risk?
What is merchant concentration?
Sources
Checked October 15, 2026- OCC, Comptroller's Handbook: Concentrations of Credit, Version 3.0, September 2026 (read October 14, 2026)
- OCC, Comptroller's Handbook: Merchant Processing, Version 1.0 (August 2014, updated March 20, 2025)
- FDIC, Understanding Deposit Insurance (read October 14, 2026)
- Regulation (EU) 2022/2554 on digital operational resilience for the financial sector (DORA), Articles 3(29) and 29
- Stripe, Unacceptable Risk Policy (read October 14, 2026)
TagadaPay
Don't let one processor carry all your sales
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors