What Is Pass-Through Pricing in Card Payments?
Pass-through costs explained, then pass-through card pricing: IC+ and IC++ vs flat and tiered, a worked example on Visa's 2026 rates, and EU rules.
Article summary
TL;DR
Pass-through pricing is a way of billing card payments where your processor charges you the real interchange and card network fees of each transaction, at cost, then adds its own fixed markup. It's also called interchange-plus (IC+), interchange++ or cost plus. A flat or blended rate charges the same fee whatever each card really costs.
- A pass-through cost is one a business pays to a third party and bills on at cost, without setting the amount itself.
- In card payments, pass-through pricing bills interchange and scheme fees at cost, plus a fixed markup from your processor.
- On Visa's April 2026 US table, a $100 online sale costs $1.99 of interchange on a basic credit card and $2.14 on a rewards card. Pass-through shows you that gap; a blended rate hides it.
- In the EU, acquirers must offer fees itemized by card category and brand, unless you ask in writing for a blended rate.
- Network costs can be adjusted after the sale, so a pass-through statement can carry late lines.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
"Pass-through" means a cost that one party collects and forwards to another, without setting it or marking it up. In card payments, it names a pricing model: your processor forwards what the card issuer and the network charge, and adds its own fee.
What are pass-through costs?
A pass-through cost is a cost a business pays to a third party and bills on to its customer at cost. The business doesn't set the amount. It earns its money from a separate fee. Three common examples:
- Energy bills. Electric Ireland says its pass-through costs "are set by ESB Networks / EirGrid / SEMO," and approved by the energy regulator. They cover the networks, the wholesale market operator and a government levy.6Electric Ireland, What are pass through costs?
- Agencies and contractors. Travel, subcontractor work or shipping paid for a client and billed back. In US federal contracts, FAR 52.215-23 limits "excessive pass-through charges": overhead or profit billed on a subcontractor's work by a contractor whose own effort adds "no or negligible value."7FAR 52.215-23, Limitations on Pass-Through Charges (Jun 2020)
- Card payments. Interchange and network fees, billed to the merchant by its processor. The rest of this page covers this case.
How pass-through pricing works for card payments
Every card sale carries three costs: interchange for the card issuer, scheme fees for the network, and your processor's markup. Visa puts it this way: "Merchants do not pay interchange reimbursement fees; merchants pay 'merchant discount' to their financial institution."3Visa, Visa USA Interchange Reimbursement Fees, April 18, 2026 The pricing model decides how that merchant discount rate is built.
Under pass-through pricing, the first two costs are billed at cost, transaction by transaction. Stripe's pricing policy describes it: "Under an IC+ pricing model, Stripe attributes underlying Network Costs to you and adds a Stripe fee (markup)." Network costs means "interchange and scheme fees, for payment cards."1Stripe, Pricing Policy (last modified October 12, 2026)
- The customer pays. The card type, how the payment was taken and your merchant category decide which interchange program applies.
- The network sets the cost. Interchange comes from the network's rate table. Scheme fees come from the network itself.
- Your processor passes them through. Each cost is billed at the amount it was, on that transaction.
- The markup is added. A percentage, a fixed amount, or both, as set in your contract.
- Some lines arrive later. Stripe says it "may retroactively adjust the Network Cost charged" when it learns more from its partners.
Sources: Stripe Pricing Policy, October 12, 2026; Visa USA Interchange Reimbursement Fees, April 18, 2026.
IC+, IC++, cost plus: one model, several names
Stripe says an IC+ model "may also be referred to as interchange++; cost plus or cost+; or network cost+."1Stripe, Pricing Policy (last modified October 12, 2026) In common use, the second plus means scheme fees are passed through as their own line too. Adyen describes its Interchange++ as a model that "accurately tracks Interchange rates and scheme fees," and lists Visa and Mastercard at "$0.13 + Interchange++ + 0.60%," with fees it calls indicative and a minimum invoice that depends on your industry.2Adyen, Pricing (read October 14, 2026) Check your contract for which fees are passed through.
Worked example: three online sales on IC++
This example is illustrative. It takes three $100 online sales on Visa cards, Visa's US interchange table effective April 18, 2026,3Visa, Visa USA Interchange Reimbursement Fees, April 18, 2026 and Adyen's published indicative markup of $0.13 + 0.60%.2Adyen, Pricing (read October 14, 2026) Scheme fees are left out: they depend on your acquirer (see assessment fee for a published schedule).
| Card used for a $100 online sale | Visa interchange | Interchange | Markup | Total before scheme fees |
|---|---|---|---|---|
| Debit from a large US bank | 0.05% + $0.21 (regulated) | $0.26, plus $0.01 if the issuer qualifies | $0.73 | $0.99 to $1.00 |
| Basic consumer credit | Product 1, All Other Products: 1.89% + $0.10 | $1.99 | $0.73 | $2.72 |
| Rewards credit | Product 1, Traditional Rewards: 2.04% + $0.10 | $2.14 | $0.73 | $2.87 |
Verdict
On pass-through, the debit sale costs about a dollar and the rewards sale nearly three. On a blended rate, all three pay the same agreed fee, whatever the card.
The debit figure is a legal ceiling. Under the Federal Reserve's Regulation II, a covered issuer "may not receive, for any electronic debit transaction, an interchange fee that exceeds $0.21 plus 0.05 percent multiplied by the value of the transaction, plus a $0.01 fraud-prevention adjustment, if eligible."5Federal Reserve, Average Debit Card Interchange Fee by Payment Card Network (updated December 19, 2025) Only pass-through pricing hands that low cost on to you. For every Visa program and how to qualify for the cheaper ones, see credit card interchange fees.
Inside Tagada
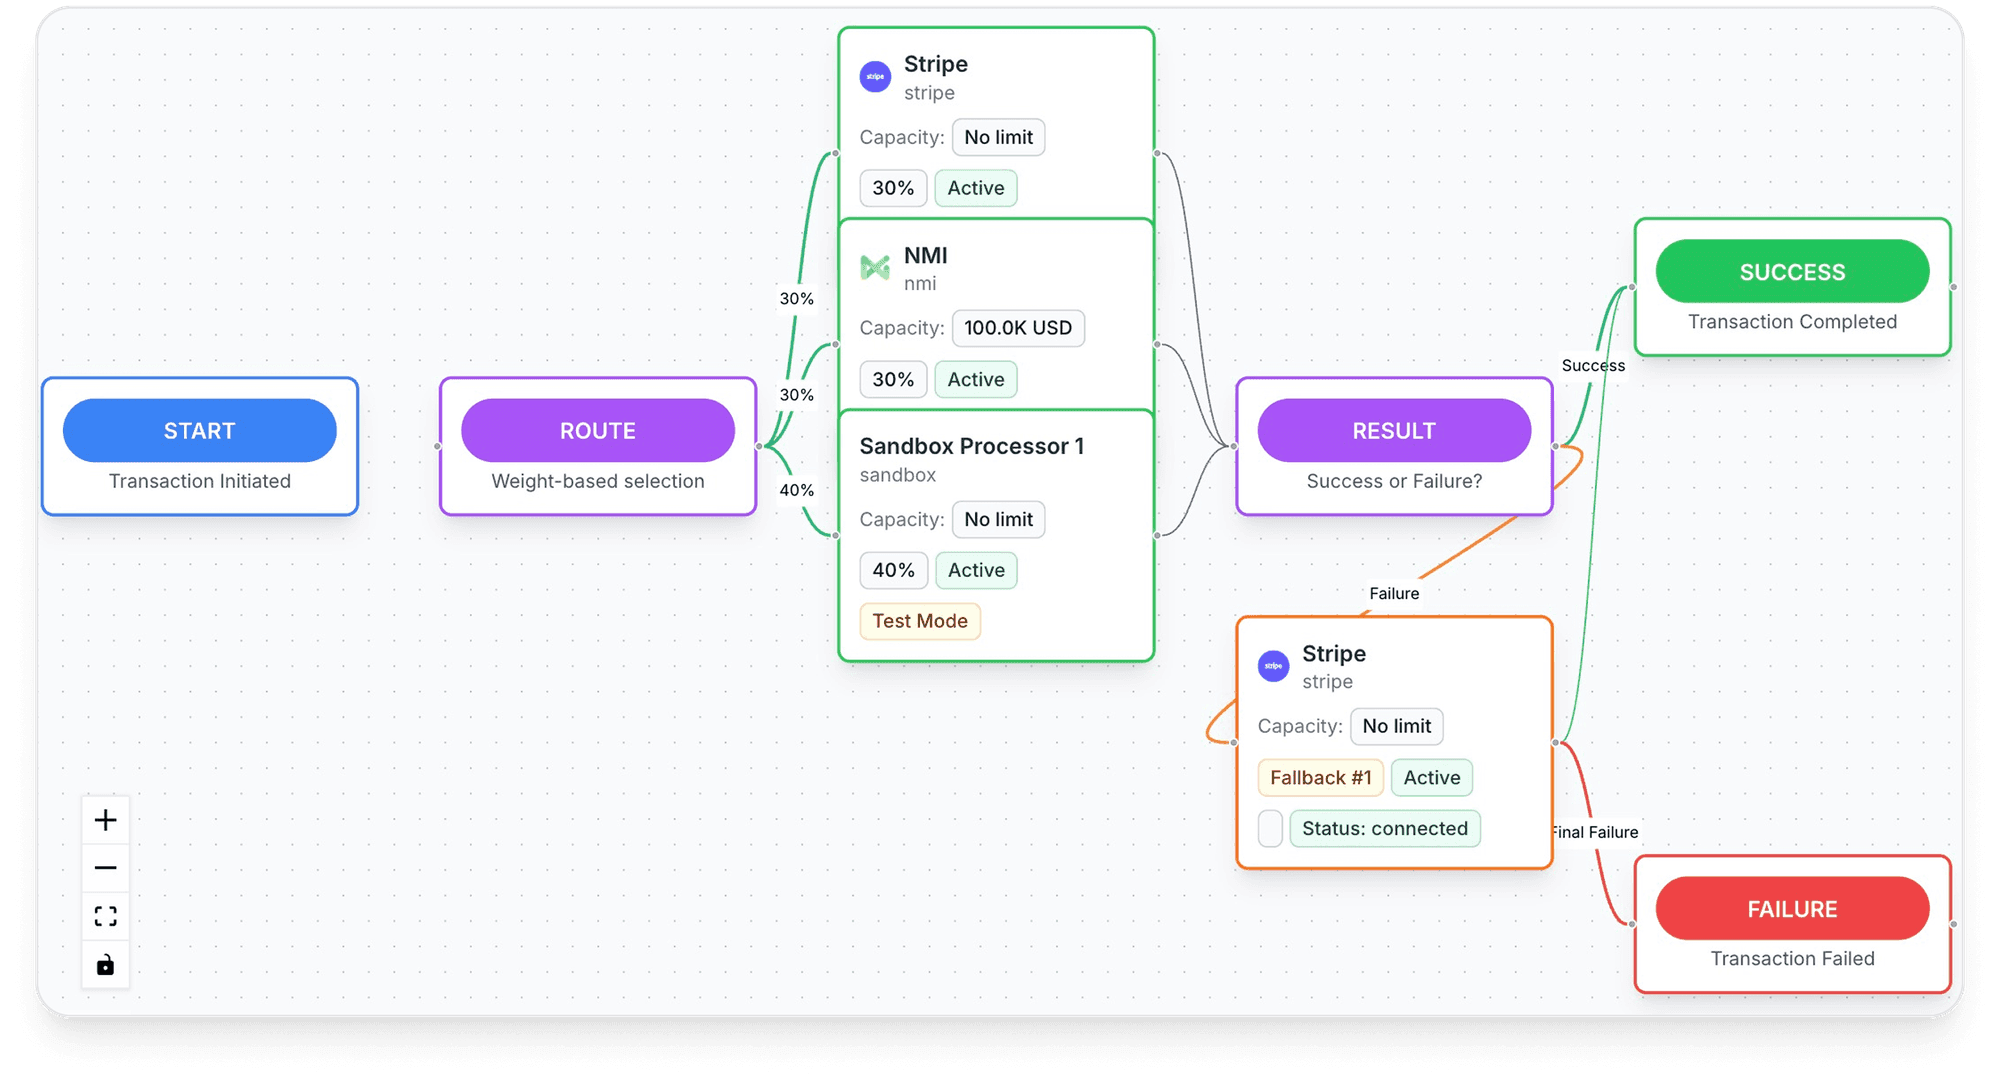
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
Pass-through vs flat-rate vs tiered pricing
| Pass-through (IC+, IC++) | Flat-rate or blended | Tiered | |
|---|---|---|---|
| What you pay | Interchange and scheme fees at cost, plus a fixed markup | One agreed fee per transaction | One rate per bucket, often called qualified, mid-qualified and non-qualified |
| Cheap card, like regulated debit | You pay less | Same fee | Depends on the bucket |
| Premium or business card | You pay more | Same fee | Often the most expensive bucket |
| What you see | Each fee, per transaction | The total only | A few rates |
| Who sets the split | The network's tables and your contract | The agreed rate | The processor sorts each sale |
| Best for | Steady volume, mixed card base | Small or new stores that want a fixed cost | Hard to audit against network tables |
Stripe defines the blended model as paying an agreed fee "regardless of the underlying differences in Network Costs."1Stripe, Pricing Policy (last modified October 12, 2026) See blended rate for that model. For each processor's 2026 rates side by side, see what a transaction fee is.
The EU and US rules behind the numbers
In the EU, the law makes itemized pricing the default. Regulation 2015/751, article 9: "Each acquirer shall offer and charge its payee merchant service charges individually specified for different categories and different brands of payment cards with different interchange fee levels unless payees request the acquirer, in writing, to charge blended merchant service charges." Agreements must also list interchange and scheme fees for each card category and brand. After each payment, article 12 requires the merchant's provider to show "the merchant service charge and the amount of the interchange fee" separately.4Regulation (EU) 2015/751 on interchange fees for card-based payment transactions
The same regulation caps consumer card interchange: 0.2% of the transaction for debit cards (article 3) and 0.3% for credit cards (article 4).4Regulation (EU) 2015/751 on interchange fees for card-based payment transactions In the US, Regulation II caps debit from large banks, as above, and limits debit routing restrictions. It says nothing about how acquirers itemize fees, so the breakdown you get depends on your contract.
What pass-through pricing means for an online store
- Negotiate the markup. Interchange comes from the network's tables and every acquirer pays it. The markup is set by your contract.
- Check interchange against the table. Visa publishes its US rates. If a line on your statement doesn't match a program, ask why.
- Expect late lines. Network costs can be adjusted after the sale, so a month's statement can carry costs from earlier payments.
- Know your card mix. Mostly debit customers make pass-through cheaper. Mostly premium and business cards can make it costlier than a flat rate.
To check each line of your own bill, see how to read a merchant statement.
How Tagada helps
One checkout, several processors
Tagada follows Visa and Mastercard rules and the laws that apply to payments. Payments route across TagadaPay and processors such as Stripe, NMI and Airwallex with one logic, with a cascade to another processor when one is down or times out.
Frequently asked questions
What are pass-through costs?
What is an example of a pass-through cost?
Is pass-through pricing the same as interchange-plus?
Is pass-through pricing cheaper than a flat rate?
What does at-cost pass-through billing mean?
Sources
Checked October 15, 2026- Stripe, Pricing Policy (last modified October 12, 2026)
- Adyen, Pricing (read October 14, 2026)
- Visa, Visa USA Interchange Reimbursement Fees, April 18, 2026
- Regulation (EU) 2015/751 on interchange fees for card-based payment transactions
- Federal Reserve, Average Debit Card Interchange Fee by Payment Card Network (updated December 19, 2025)
- Electric Ireland, What are pass through costs?
- FAR 52.215-23, Limitations on Pass-Through Charges (Jun 2020)
TagadaPay
Running several processors? Route them from one checkout
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors