
What Is Payment Analytics? KPIs, Data and Gateway Reports
Payment analytics explained: KPIs and formulas, the data sources and IDs that join them, what Stripe, Adyen and PayPal report, and a sample dashboard.

Article summary
TL;DR
Payment analytics is the practice of collecting and measuring payment data, from the first checkout attempt to the bank payout, to see how many payments succeed, why the others fail, what they cost and which turn into disputes. It joins processor reports, bank statements and store orders, then splits results by card, country, issuer and processor.
- Payment analytics covers the whole payment: attempt, authentication, authorization, capture, refund, dispute, payout. Each step has its own metric and its own page.
- No single report holds everything. Processor data, bank deposits and store orders meet only through shared IDs: order ID, payment ID, ARN and payout ID.
- A blended rate hides the cause. Split by card brand, card country, issuer, payment method, processor, 3DS outcome and decline code.
- Stripe, Adyen and PayPal all report natively, but each counts its own way, and Stripe can't compute an authorization rate for payments on another processor.
- Keep full card numbers out of your analytics (PCI DSS 3.5.1) and collect only the personal data you need (GDPR article 5(1)(c)).
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
Payment analytics answers four questions about your payments: how many succeed, why the others fail, what they cost, and whether the money arrived. It's narrower than ecommerce analytics, which also covers traffic, acquisition and retention.
What is payment analytics?
Payment analytics is the measurement of everything that happens to a payment: the attempt, 3D Secure, authorization, capture, refund, dispute and payout. Payment gateway analytics is the slice your gateway shows you. Stripe's Payments analytics page, for example, groups reports on acceptance, authentication, disputes and payment methods.1Stripe Docs, Payments analytics (read October 14, 2026)
Online stores, subscription brands, finance teams and payment teams use it. Each needs a different view of the same data.
The core payment KPIs
Each metric below has its own page with the full formula, an example and the traps. This table is the map.
| Metric | Formula in one line | Full definition |
|---|---|---|
| Payment success rate | Successful payments ÷ payment attempts × 100 | Payment conversion rate |
| Authorization rate | Issuer approvals ÷ attempts sent to the card network × 100 | Authorization rate |
| 3DS authentication success rate | Completed 3DS ÷ 3DS attempts × 100 (Stripe's definition)3Stripe Docs, Authentication analytics (read October 14, 2026) | 3D Secure |
| Fraud block rate | Payments blocked by fraud rules ÷ attempts × 100 | Fraud scoring |
| Chargeback rate | Chargebacks in a month ÷ transactions; each network sets its own formula | Chargeback rate |
| Effective rate | Total processing fees ÷ total card sales × 100 | Effective rate |
| Gross payment volume | Value of payments processed in a period, before fees | Gross payment volume |
| Average order value | Revenue ÷ orders | Average order value |
| Cart abandonment rate | (Carts created − purchases) ÷ carts created × 100 | Cart abandonment |
| Unmatched payouts | Payouts not yet matched to a bank deposit and its orders | Reconciliation |
Write down how you count retries before you compare anything. Stripe offers a "raw" rate that counts every attempt and a "deduplicated" rate that keeps only the final outcome of each purchase.2Stripe Docs, Acceptance analytics (read October 14, 2026) Adyen calls them gross and net, and suggests asking any provider: "Are you reporting gross or net?"7Adyen Knowledge Hub, Why your payment acceptance rate isn't the full story, July 13, 2026
Where the data comes from
| Source | What it holds | How it arrives |
|---|---|---|
| Gateway and processor | Attempts, decline codes, 3DS results, fees, refunds, disputes | API, webhooks, dashboard reports |
| Card networks, through your acquirer | Dispute reasons, the ARN that traces a payment between banks | Processor dispute and settlement reports |
| Bank statements | The deposits that actually landed | Bank export or feed |
| Store or CRM orders | Order ID, products, customer, discounts | Your platform's database or export |
These sources only join through shared IDs. The step-by-step matching belongs to reconciliation; for analytics, make sure each ID is stored on both sides.
Fig. 1One order, followed across sources
- Order ID
- #10482, sent as metadata (Stripe) or Merchant Reference (Adyen)
- Payment ID
- PaymentIntent ID (Stripe) or Psp Reference (Adyen)
- ARN
- Optional column in Adyen's report, traces refunds and disputes
- Payout ID
- Payout ID (Stripe) or Batch Number (Adyen)
- Bank deposit
- Stripe's trace ID, the reference your bank uses
Illustrative record.
store the order ID on the payment, or nothing joins
Stripe's itemized payout report can include your own metadata keys, so the order ID travels with each payment.4Stripe Docs, Payout reconciliation report (read October 14, 2026) Adyen's settlement details report carries Merchant Reference, Psp Reference and Batch Number by default, with ARN and Issuer Country as optional columns.6Adyen Docs, Settlement details report (read October 14, 2026)
Watch the clock too. Stripe processes acceptance data daily in UTC,2Stripe Docs, Acceptance analytics (read October 14, 2026) and groups payouts by estimated arrival date, not the date your bank posts the deposit.4Stripe Docs, Payout reconciliation report (read October 14, 2026) Your store may report in local time, so day totals can differ for that reason alone.
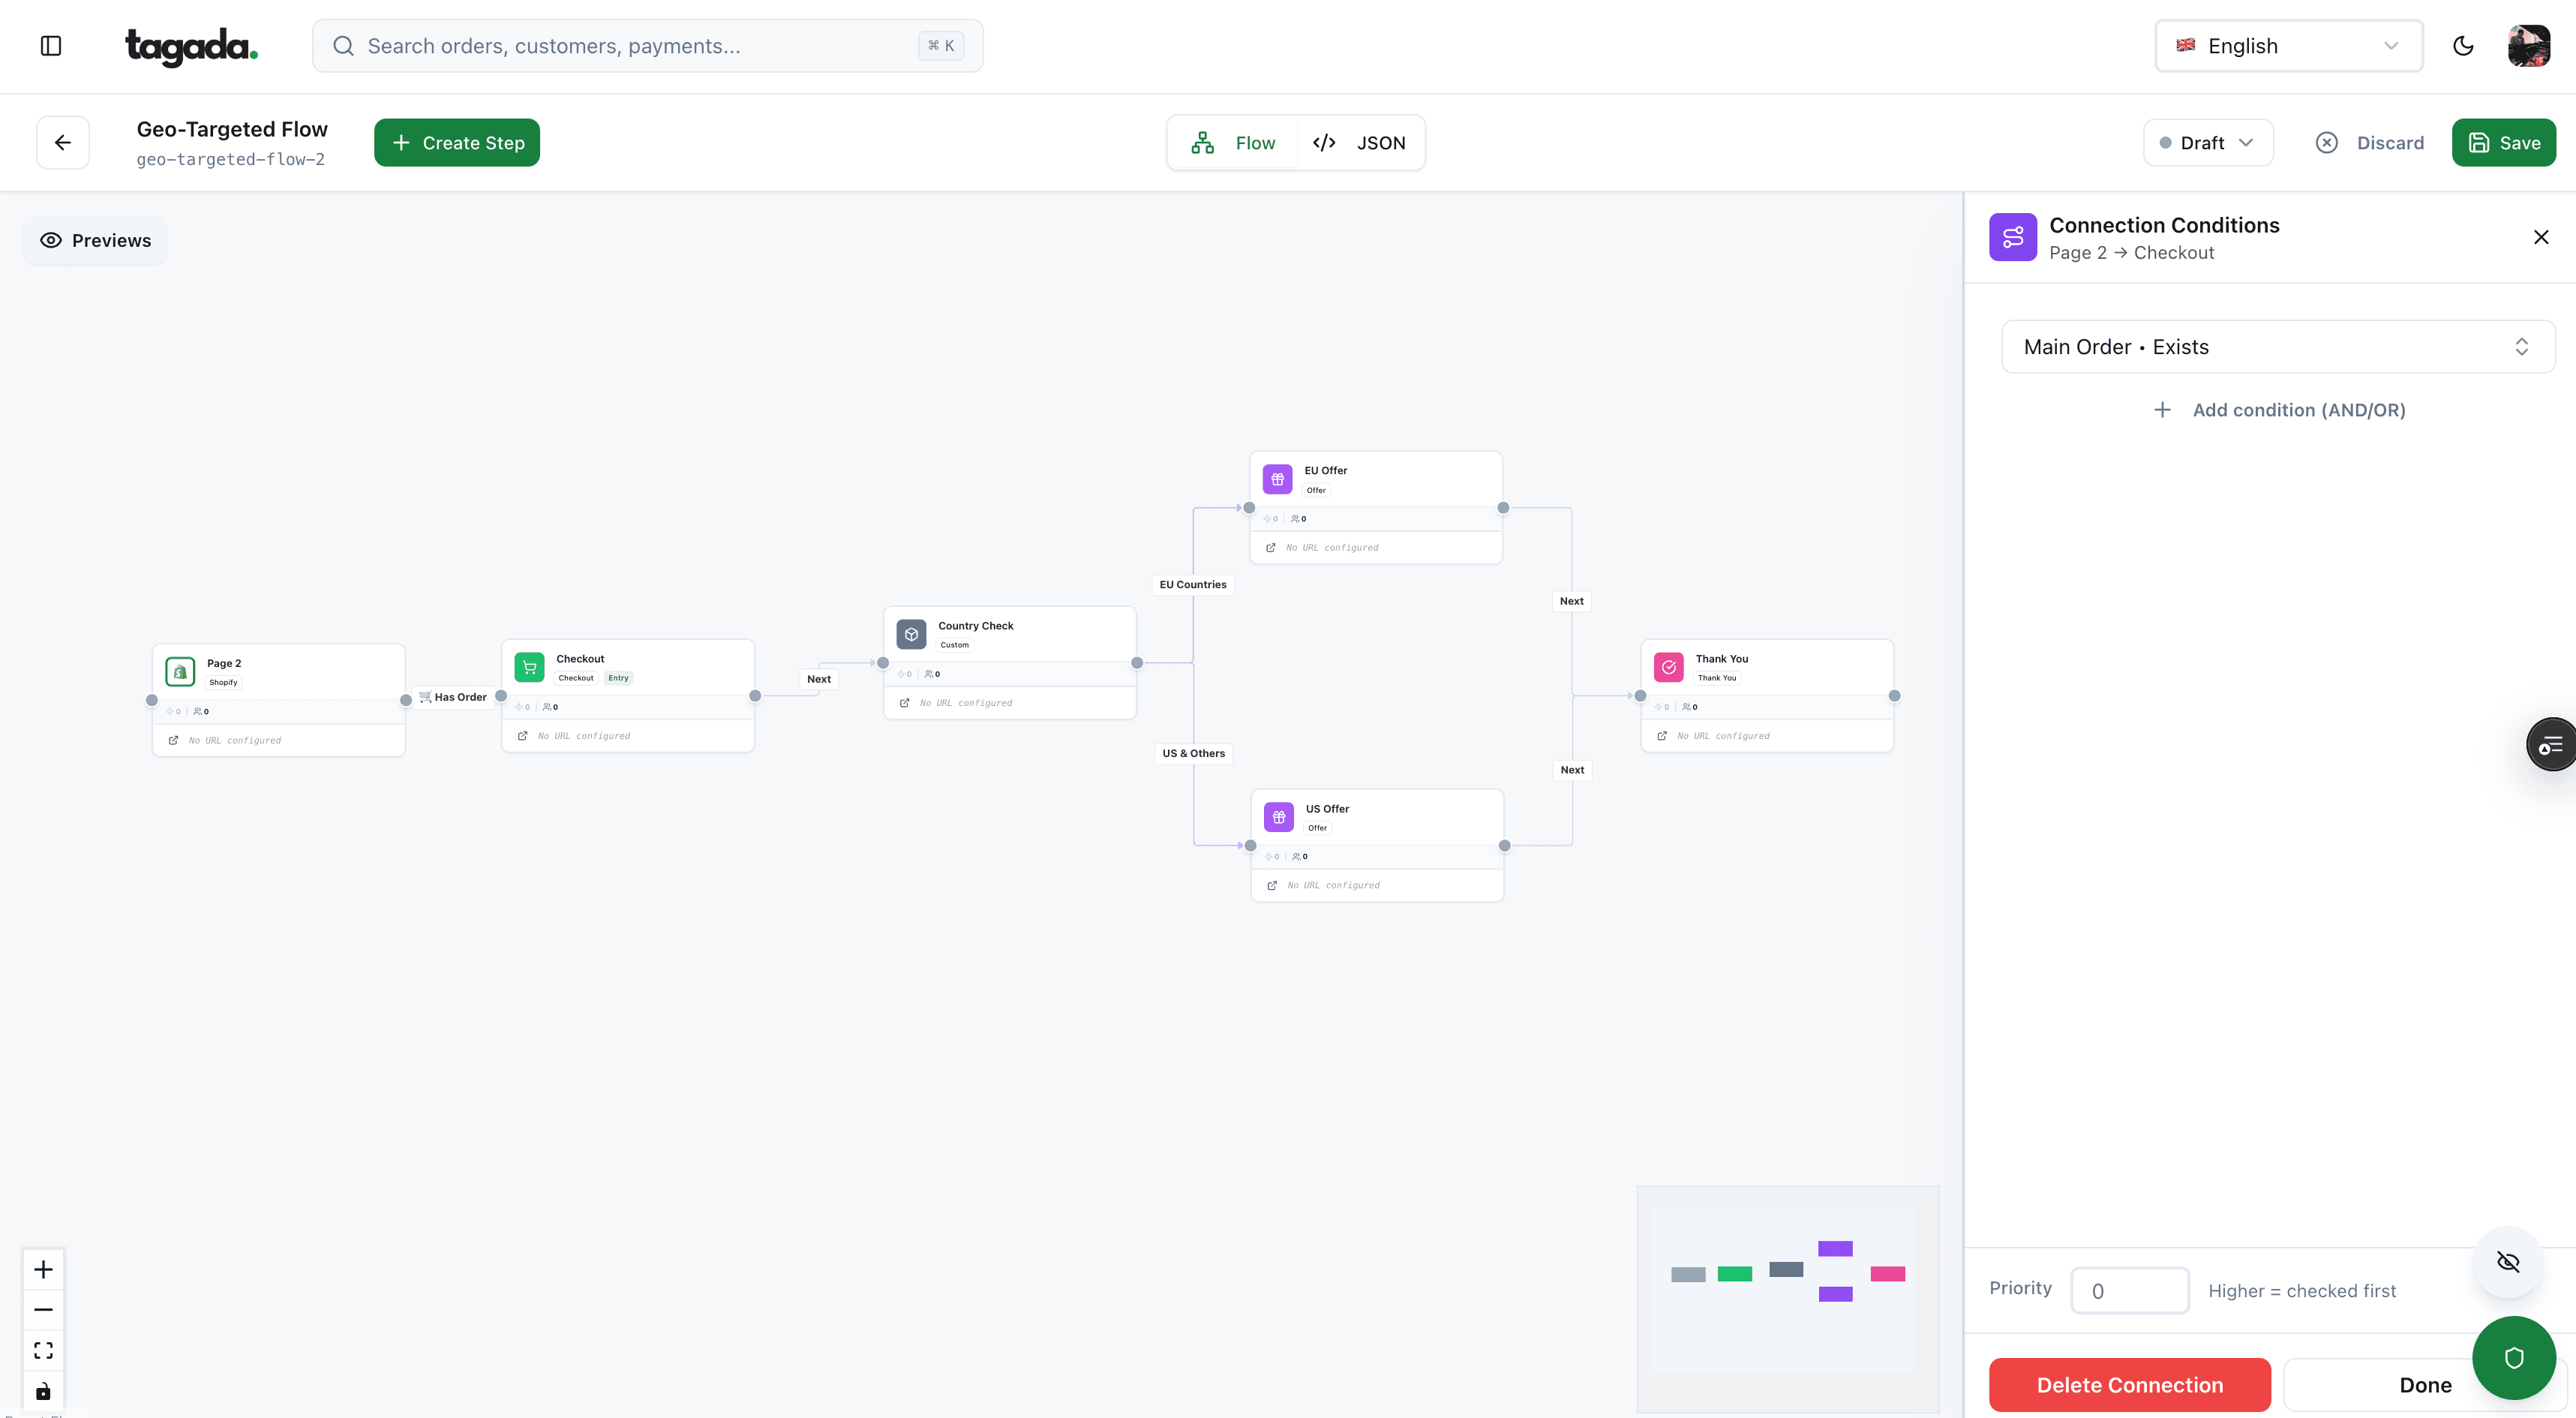
Inside Tagada
Build the funnel once, route every customer to the right offer
Checkout, upsells and subscriptions on one flow, with conditions per country, order or customer.
Segment before you conclude
A blended rate tells you something changed, not where. Split every KPI by these dimensions:
Card brand and type
Visa, Mastercard, Amex; credit, debit, prepaid. Stripe says credit succeeds more often than debit, and debit more than prepaid.
BIN country and issuer
The first digits of the card identify the issuer and its country. Stripe's card country is the issuer's country, not where the shopper stands, and domestic payments succeed more often on average.
Payment method and processor
Cards, wallets, local methods; one line per processor. Stripe notes wallets like Apple Pay tend to succeed more often because they're tokenized and device-authenticated.
3DS outcome and decline code
Frictionless, challenged, failed, not attempted. Then the issuer's reason: insufficient funds, incorrect details, generic "do not honor".
The patterns in these cards come from Stripe's acceptance documentation.2Stripe Docs, Acceptance analytics (read October 14, 2026) Your own data may differ: that's the point of segmenting. For what to do about declines once you've found them, see our guide to payment acceptance rate.
What processors show natively
Read on October 14, 2026. Menus change, so check your own account.
| Processor | Where | What you get | Limit to know |
|---|---|---|---|
| Stripe | Payments analytics page | Acceptance (success rate, authorization rate, failed and blocked payment reports), authentication (3DS rates, challenge rate), disputes, payment methods1Stripe Docs, Payments analytics (read October 14, 2026)2Stripe Docs, Acceptance analytics (read October 14, 2026) | Can't show an authorization rate for a non-Stripe processor: "Stripe doesn't have access to non-Stripe data."2Stripe Docs, Acceptance analytics (read October 14, 2026) |
| Adyen | Customer Area, Insights | Payment lifecycle tabs: authentication and drop-off, authorized and refused with refusal reasons, purchases and refunds, chargebacks and fraud notices, settlements and fees5Adyen Help, How can I monitor my specific payment method performance? (read October 14, 2026) | Needs the Merchant Report or Merchant View Shopper Insights role5Adyen Help, How can I monitor my specific payment method performance? (read October 14, 2026) |
| PayPal | Reporting Dashboard, SFTP | Attempts and Declines report, Balance Reconciliation Report, Fee Transaction report, Case Report for disputes8PayPal Developer, Reports overview (read October 14, 2026) | Files, not ready-made rates: you compute the KPIs |
Each tool counts only its own traffic, in its own way. If you run several processors, the comparison has to happen where all attempts meet: your own data or a payment orchestration layer.
An illustrative dashboard layout
Fig. 2A payments dashboard on one screen
- Row 1 · Today
- Payment success rate, authorization rate, attempts per hour, compared with the same day last week
- Row 2 · Failures
- Top decline codes, fraud blocks, failed 3DS, split by processor
- Row 3 · Money
- Gross payment volume, refunds, effective rate, unmatched payouts
- Row 4 · Risk
- Disputes opened this month, chargeback rate, dispute reasons
Illustrative layout.
top row answers 'is something broken right now?'
Row 1 is for daily checks. Rows 3 and 4 are for the monthly review, and they need complete periods: Stripe warns that deduplicated rates dip for recent weeks while retries are still running.2Stripe Docs, Acceptance analytics (read October 14, 2026)
Keep card data and personal data out
Two rules for any payment analytics table
PCI DSS requirement 3.5.1: the full card number must be "rendered unreadable anywhere it is stored", and 3.4.1 caps what's displayed at the BIN and last four digits.10PCI Security Standards Council, PCI DSS v4.0 SAQ D for Merchants, requirements 3.4.1 and 3.5.1 GDPR article 5(1)(c): personal data must be "limited to what is necessary" for the purpose.11Regulation (EU) 2016/679 (GDPR), Article 5(1)(c)
This matters because exports carry personal data. Adyen's 3D Secure Conversion report includes shopper name, email and IP address;9Adyen Docs, 3D Secure Conversion report (read October 14, 2026) Stripe's payout report can add customer name and email.4Stripe Docs, Payout reconciliation report (read October 14, 2026) Leave those columns out of your analytics unless a use needs them.
How Tagada helps
Compare processors behind one checkout
Tagada routes payments across TagadaPay and processors such as Stripe, NMI and Airwallex, with one logic and a cascade to another processor when one is down or times out, so the processors you compare sit behind the same checkout. Its checkout also sends conversion tracking server side to Meta, Google and TikTok. Tagada follows Visa and Mastercard rules and the laws that apply to payments.
Frequently asked questions
What is payment data analytics?
What is payment gateway analytics?
What does payment analytics and reporting include?
Do I need a payment analytics solution, or are processor dashboards enough?
What is payment operations analytics?
How is analytics used in the payment industry?
Sources
Checked October 15, 2026- Stripe Docs, Payments analytics (read October 14, 2026)
- Stripe Docs, Acceptance analytics (read October 14, 2026)
- Stripe Docs, Authentication analytics (read October 14, 2026)
- Stripe Docs, Payout reconciliation report (read October 14, 2026)
- Adyen Help, How can I monitor my specific payment method performance? (read October 14, 2026)
- Adyen Docs, Settlement details report (read October 14, 2026)
- Adyen Knowledge Hub, Why your payment acceptance rate isn't the full story, July 13, 2026
- PayPal Developer, Reports overview (read October 14, 2026)
- Adyen Docs, 3D Secure Conversion report (read October 14, 2026)
- PCI Security Standards Council, PCI DSS v4.0 SAQ D for Merchants, requirements 3.4.1 and 3.5.1
- Regulation (EU) 2016/679 (GDPR), Article 5(1)(c)
Tagada
Route across TagadaPay and processors such as Stripe, NMI and Airwallex from one checkout
Funnels, one-click upsells, subscription billing and payment routing, on one customer record.
- 01Create your free account
- 02Connect your store or build a checkout
- 03Launch funnels, upsells and subscriptions