Best Payment Processors for Ecommerce: The Right One for Each Use Case
The best payment processor for global DTC brands, Shopify stores, subscriptions, marketplaces and enterprise, picked from official pages, with no scores.



Article summary
TL;DR
The best payment processor depends on what you sell and where. Global DTC brands look at Stripe or Adyen, Shopify stores at Shopify Payments, marketplaces at Stripe Connect or Adyen for Platforms, wallet-heavy checkouts at PayPal and Braintree. Businesses that processors review closely need one that underwrites them, and a second one behind it.
- No processor is best for everyone. Pick by use case: countries, store platform, subscriptions, marketplace payouts, risk profile.
- On a domestic US card, published rates sit near 2.9% + 30¢. Foreign cards, currency conversion and platform fees decide the total.
- On Shopify, a processor other than Shopify Payments adds a Shopify fee of 2% down to 0.2% depending on the plan.
- For subscriptions, what matters is card updates, retries and whether you can export your saved cards.
- If your category is reviewed closely, read the restricted list first and plan for a second processor before you need it.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
There is no single best payment processor. There is a best fit for what you sell, where you sell it and how. This list goes use case by use case, from global DTC brands to marketplaces, and names the processors whose own pages, read in October 2026, match each one. No scores, no paid ranking. By industry: Stripe rules for supplement brands, Stripe rules for skincare brands, Stripe rules for online pharmacies, Stripe rules for telehealth companies, Stripe rules for fitness brands and Stripe rules for info product businesses.
Best payment processors by use case, at a glance
| Your situation | Processors to look at | Why, from their own pages | Check before you sign |
|---|---|---|---|
| Global DTC brand | Stripe, Adyen | Stripe: direct sign-up in 44 countries, 125+ payment methods. Adyen: settle in several currencies | Foreign card and currency conversion fees |
| Shopify store | Shopify Payments | NoExtra Shopify fee, automatic card updates for subscriptions | Payout timing in your admin, the restricted list |
| Subscriptions | Stripe (with Billing), Shopify Payments, Braintree | Recurring billing, retries, card updates | Whether you can export saved cards |
| Marketplace | Stripe Connect, Adyen for Platforms | Seller onboarding and verification, split payments, payouts | Who carries seller fraud and disputes |
| Wallet-heavy checkout | PayPal, Braintree | PayPal and Venmo next to cards | Wallet rates are higher than card rates |
| Online and in person | Square | One account, next-business-day payouts | Online rate on the free plan |
| Enterprise volume | Adyen, Checkout.com | Interchange++ or custom pricing, multi-currency settlement | Minimum invoice, dispute fees in writing |
| Categories reviewed closely | Processors that underwrite each business | A review up front instead of a closure later | RestrictedList, reserves, your MCC |
| Several processors in one checkout | An orchestration layer, such as Tagada with TagadaPay | Routing and fallback between processors | Card vault portability |
Verdict
The rate is rarely what separates these processors. Whether they accept your business, pay you on time and handle foreign customers does. Shortlist two from your row, then price both on last month's transactions.
Fees, payouts and dispute costs for each of these processors, side by side, are in our payment processor comparison.
What is TagadaPay?
TagadaPay is the payment processor run by Tagada (tagada.io), an ecommerce platform for checkout, funnels and subscriptions. Tagada routes payments across TagadaPay and processors such as Stripe, NMI and Airwallex, with one logic, and cascades to another processor when one is down or times out. Each business that applies is underwritten. It appears once in this list, under several processors in one checkout, as one option among others. A fuller description, and how to judge it like any processor, is in the TagadaPay section of our comparison.
Seeing a TagadaPay charge on your card?
TagadaPay processes payments for online stores, so the charge most likely comes from a store you bought from. Look for an order confirmation dated around the charge and contact that store first. If you don't recognize the purchase, contact the bank that issued your card.
How we chose
Every processor here is placed by what its own pricing pages, help centers and developer docs say, read on October 14, 2026. We didn't score them, because no public data measures how well a processor fits your business.
- Start from the use case. A Shopify store, a marketplace and a subscription brand don't need the same thing.
- Keep only what the processor publishes. Rates, countries, payment methods, payout timing, recurring tools, marketplace features.
- Name what to check. Each entry ends with the question to ask before signing, because the public page never tells the whole story.
- Date everything. Prices change. Each figure is cited to its source, with the date we read it.
Tagada runs its own processor, TagadaPay. It is described with the facts on Tagada's site only, in one entry, and isn't ranked above anyone.
Best payment processor for global DTC brands: Stripe or Adyen
If you sell to customers in many countries, three things matter: whether the processor can sign up your business where it's registered, which local payment methods it offers, and what a foreign card or a currency conversion adds.
44
Countries where a business can sign up to Stripe directly, out of 51 listed
125+
Payment methods Stripe says you can access
+1.5%
Stripe's fee on an international card, plus 1% if currency is converted
Stripe publishes its rate: 2.9% + 30¢ for a domestic US card, 1.5% more for an international card and 1% more when currency is converted.1Stripe, Pricing (United States), October 2026 Its global page lists 51 countries and regions, 44 of them with direct sign-up.2Stripe, Global availability It suits a brand that wants to start fast and add markets one by one.
Adyen prices Visa and Mastercard at $0.13 + interchange++ + 0.60%, with no monthly, setup or closure fee, but a minimum invoice that depends on your industry. You can link bank accounts in several currencies and settle without converting first.7Adyen, Pricing It suits brands with enough volume to justify interchange++ and the integration work.
Check before you sign: where your customers' cards are issued, and in which currencies you want to be paid. Ask each processor whether it can process locally, in the customer's own country, in your top markets. See local acquiring, local payment methods and multi-currency support.
Best payment processor for Shopify stores: Shopify Payments
On Shopify, the platform's own processor has an edge no rate comparison shows: Shopify charges an extra fee when you use another provider.
Fig. 1Shopify's extra fee when you use another payment provider
on top of that provider's own rate
Shopify Payments costs 2.9% + 30¢ on Basic, down to 2.25% + 30¢ on Plus, with premium cards at 3.5% + 30¢ on Basic.9Shopify, Pricing (US), October 2026 It's available to businesses in 41 countries.10Shopify Help Center, Supported countries for Shopify Payments For subscriptions, automatic card updates are a Shopify Payments feature; on other gateways, customers may have to update their card themselves.11Shopify Help Center, Subscriptions: considerations and payment gateways, read October 14, 2026
Check before you sign: Shopify Payments sets payout timing by country and account, so check the schedule in your admin. If Shopify Payments isn't available for your business, a third-party provider on the Basic plan costs you 2% more per order before its own fees. That's when moving up a plan, or comparing the total cost of the outside provider, matters.
Best payment processor for subscriptions
For a subscription business, the first payment is easy. Renewals are where processors differ: card updates when a card is reissued, retries after a decline, and whether your saved cards can leave with you.
- Stripe with BillingSubscriptions, invoices, Smart Retries and a customer portal, for 0.7% of billing volume on top of payment feesPayments on other processors get no Smart Retries or Stripe recovery emails
- Shopify PaymentsWorks with Shopify Subscriptions and third-party subscription apps, with automatic card updatesOn other gateways, Shopify subscription apps are limited to a short list
- BraintreeRecurring billing that charges customers automatically in monthly increments, from cards stored in its VaultWhich payment methods can be charged on renewal in your countries
- Any processorRecurring billing is standardCan you export saved cards to another vault if you leave?
Sources: Stripe Billing pricing and docs, Shopify Help Center, Braintree docs.4Stripe, Billing pricing, read October 14, 202619Stripe Docs, Integrate with third-party payment processors11Shopify Help Center, Subscriptions: considerations and payment gateways, read October 14, 202620Braintree Docs, Recurring billing overview On Shopify, third-party subscription apps work only with Shopify Payments, PayPal Express, Authorize.net, Adyen or Stripe, and Stripe only for select merchants.11Shopify Help Center, Subscriptions: considerations and payment gateways, read October 14, 2026
The billing software and the processor are two layers; choosing the first is covered in recurring billing software. How renewals work at the card network level, and which questions to ask a processor, are in subscription payment processing. What to do when renewals fail is in subscription payment failures.
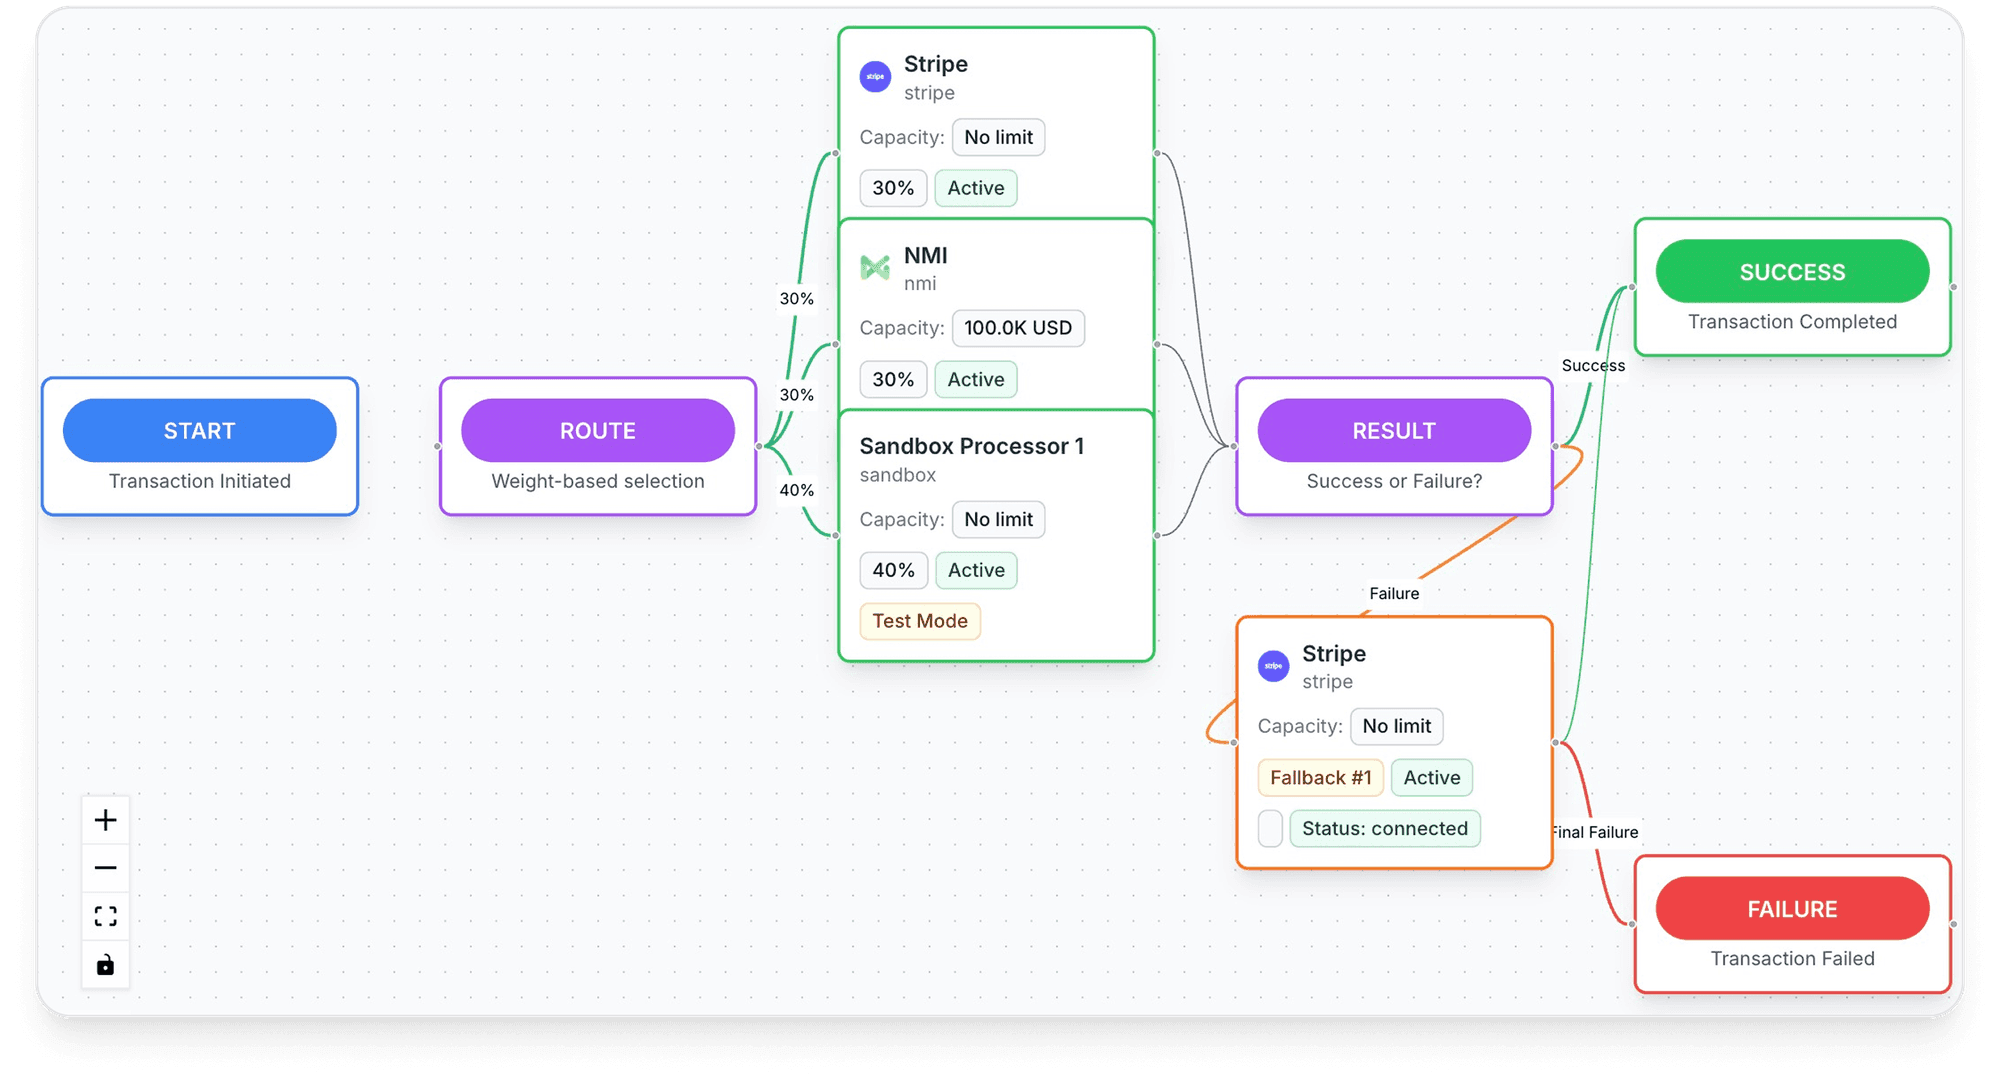
Inside Tagada
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
Best payment processor for marketplaces: Stripe Connect or Adyen for Platforms
A marketplace takes payments from buyers and pays sellers. It needs to onboard and verify each seller, split each payment and schedule payouts. A plain merchant account doesn't do that.
Fig. 2What a marketplace needs from its processor
- Onboard and verify sellersStripe: collect verification information for each connected account. Adyen: verify sellers before paying out
- Split the paymentStripe: split payments between the platform and sellers. Adyen: split between users, deduct costs, hold funds
- Pay sellers outStripe: payouts to connected accounts. Adyen: managed payouts or custom timing
three jobs a store doesn't have
Stripe Connect is built for "a platform, marketplace, fintech, or other business that requires you to model multiple accounts and move money between parties."5Stripe Docs, Connect Adyen for Platforms lets a marketplace "onboard sellers, service providers, or contractors" and have Adyen verify them before paying out, split payments, and choose managed or custom payouts.8Adyen Docs, Marketplaces (Adyen for Platforms)
Check before you sign: who is liable when a seller commits fraud or gets disputes, and which MCC each seller account receives. See split payments and payment facilitator.
Best for wallet-heavy checkouts: PayPal and Braintree
Some customers would rather not type a card at all. If your buyers already use PayPal or Venmo, offering them changes conversion more than a few basis points of rate.
PayPal charges 3.49% + 49¢ for PayPal Checkout payments and 2.99% + 49¢ for standard card payments in the US.12PayPal, Merchant and business fees (US), updated October 1, 2026 Braintree, PayPal's processor for larger merchants, charges 2.89% + 29¢ for cards and digital wallets and 3.49% + 49¢ for Venmo, with custom flat rates and interchange-plus for established businesses.13PayPal Braintree, Fees (US), last updated May 7, 2026
Check before you sign: your wallet share. PayPal and Venmo payments cost more per order than card payments on these fee pages, so the gain has to come from orders you'd otherwise lose. Apple Pay and Google Pay are offered by most processors on this list; see digital wallet.
Best for online and in-person sales: Square
If you sell at markets, pop-ups or a shop as well as online, one account for both keeps reporting and payouts in one place.
Square charges 3.3% + 30¢ for online checkout on its free plan; paid plans lower that to 2.9% + 30¢.14Square, Pricing (US), October 2026 Payments taken before 5 PM PT reach your bank the next business day, and instant or same-day transfers cost 1.95% per transfer.15Square Support Center (US), Transfer limits and processing times
Check before you sign: whether the online rate on your plan, rather than the in-person rate, drives your total. For an online-only brand, Square's strength in person adds little.
Best for enterprise volume: Adyen and Checkout.com
At high volume, a published flat rate is usually the most expensive option. Enterprise processors price on interchange++ or quote you directly.
Adyen
$0.13 + interchange++ + 0.60% on Visa and Mastercard. No monthly, setup or closure fee, but a minimum invoice by industry. Settlement in the currency and at the time you choose.
Checkout.com
No published rate. Flat-rate or interchange++ pricing "based on your business profile and risk category", with no setup or account maintenance fees.
Stripe, PayPal, Braintree
Published flat rates, but each also offers custom pricing once your volume justifies it.
Sources: Adyen, Checkout.com and Braintree pricing pages.7Adyen, Pricing16Checkout.com, Pricing13PayPal Braintree, Fees (US), last updated May 7, 2026 Neither Adyen nor Checkout.com lists a dispute fee on its pricing page; get it in writing. How interchange++ compares with flat-rate pricing is in what is a transaction fee and the glossary entry for interchange-plus pricing.
Already have a bank merchant account? A gateway like Authorize.net connects to it for $25 a month plus 10¢ per transaction and a 10¢ daily batch fee; its all-in-one plan is 2.9% + 30¢, "subject to eligibility."17Authorize.net, Pricing
Categories processors review more closely
Some businesses get approved in minutes and closed three months later. It happens most often in categories card networks and processors treat as higher risk.
Visa's April 2026 Merchant Data Standards Manual lists the codes it treats as high-risk for card-not-present sales, including 5122 (drugs and druggist sundries), 5966 and 5967 (direct marketing) and 7995 (betting), plus, depending on how you sell, 5968 (direct marketing continuity and subscription merchants). A high-risk activity must have its own MCC, separate from the rest of the business.18Visa, Merchant Data Standards Manual, April 2026 Processors add their own lists: Stripe's names, among others, membership clubs that bill until cancellation and discounted trials with hidden or unclear charges.6Stripe, Prohibited and Restricted Businesses
- Read each restricted list against your whole catalog, not only your main product.
- Find your MCC. It follows you into every application. See high-risk MCC codes and MCC 5968.
- Prefer a processor that underwrites you up front. Checkout.com prices "based on your business profile and risk category"; others review you only after you start processing.
- Ask about reserves in writing: when they apply, what share, for how long. See rolling reserve.
- Plan the second processor now. If one account is reviewed, the other keeps checkout open. How to set that up is in our guide to the high-risk payment gateway.
The best processor for a category reviewed closely is one that knows your business before you process, and a second one ready behind it.
Several processors in one checkout: Tagada and TagadaPay
Most of the processors above are a single account with a single set of rules. For a brand that can't afford checkout stopping during a review, an outage or a processor's risk block, the use case is different: several processors behind one checkout, and a layer that decides where each payment goes.
Fig. 3One checkout, two processors
approved declined or closed routing step
- CheckoutCustomer pays
- routes toProcessor ATimeout or outageDeclined
- falls through toProcessor BApprovedApproved
a processor failure gets a second chance, a bank decline doesn't
How Tagada helps
Tagada with TagadaPay: best for brands that route between processors
Tagada routes payments across TagadaPay and processors such as Stripe, NMI and Airwallex, with one logic, and cascades to another processor when one is down or times out. Its card vault lets you switch processors without re-onboarding customers, so running subscriptions keep charging. Subscriptions come with trials, billing cycles, dunning and automatic retries; the checkout with one-click upsells, order bumps, A/B tests, Apple Pay and Google Pay. 3D Secure 2 is native, with device intelligence and a rules engine. It runs standalone or with Shopify, WooCommerce or a headless store. Each TagadaPay business is underwritten, with enhanced review on regulated verticals. Pricing is on the pricing page; payments on the payments page. Tagada follows Visa and Mastercard rules and the laws that apply to payments.
Check before you sign, with Tagada or any orchestration provider: which processors it connects to today, who holds the card vault, and whether you can export your cards. A second processor also brings its own underwriting, fees and dispute handling. What an orchestration layer does, and when you don't need one, is in what is payment orchestration; retry rules are in dynamic payment routing.
How to pick yours
Start from your row in the table at the top, then:
- Price two offers on real data. Last month's orders: card countries, card types, currencies, refunds. Compare the cost per approved payment, not the headline rate. See payment acceptance rate.
- Ask about payouts and reserves. A new Stripe account's first payout comes 7 to 14 days after the first live payment, depending on industry, country and risk level.3Stripe Docs, Payouts
- Ask how you leave. If your saved cards can't follow you, switching later means asking every subscriber for their card again.
- Read the restricted list before you build, not after the first payout hold.
Gateway, processor or PSP, and which one you actually need, is explained in payment gateway vs payment processor and payment service provider.
Frequently asked questions
What is the best payment processor for global DTC brands?
What is the best payment processor for ecommerce?
What is TagadaPay?
Which payment processor is fastest to set up?
Can I use more than one payment processor?
Which payment processors accept subscription businesses?
Sources
Checked October 14, 2026- Stripe, Pricing (United States), October 2026
- Stripe, Global availability
- Stripe Docs, Payouts
- Stripe, Billing pricing, read October 14, 2026
- Stripe Docs, Connect
- Stripe, Prohibited and Restricted Businesses
- Adyen, Pricing
- Adyen Docs, Marketplaces (Adyen for Platforms)
- Shopify, Pricing (US), October 2026
- Shopify Help Center, Supported countries for Shopify Payments
- Shopify Help Center, Subscriptions: considerations and payment gateways, read October 14, 2026
- PayPal, Merchant and business fees (US), updated October 1, 2026
- PayPal Braintree, Fees (US), last updated May 7, 2026
- Square, Pricing (US), October 2026
- Square Support Center (US), Transfer limits and processing times
- Checkout.com, Pricing
- Authorize.net, Pricing
- Visa, Merchant Data Standards Manual, April 2026
- Stripe Docs, Integrate with third-party payment processors
- Braintree Docs, Recurring billing overview
TagadaPay
One processor isn't enough? Route between several
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors