How to Prevent Chargebacks: 18 Ways That Work
18 ways to prevent chargebacks in ecommerce: before the order, at checkout, after delivery and on subscriptions, plus the alerts that stop disputes early.
Article summary
TL;DR
Most chargebacks come from three places: real fraud, customers who don't recognize or regret a charge, and merchant mistakes. Three habits prevent most of them: be clear before the purchase, refund faster than the bank would, and keep proof of every order. Pre-dispute alerts from Visa and Mastercard catch part of the rest.
- Start from your own reason codes: each dispute category points to a different fix.
- A recognizable statement descriptor and a support contact customers can find stop many disputes before they start.
- Capture the payment when you ship, not when the order is placed: an uncaptured authorization can't be disputed.
- On subscriptions, Visa requires terms shown separately at sign-up, a reminder at least 7 days before a trial ends, and online cancellation.
- Disputes resolved through Verifi RDR or Ethoca Alerts don't count in your dispute rate, and Visa leaves pre-dispute resolutions out of its VAMP ratio.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
You can't stop every chargeback. You can stop most of the ones that come from confusion, slow refunds and missing proof, and those are the ones that push your dispute rate up. Start by finding where yours come from, then work through the 18 fixes below, in the order a customer meets your store. For the merchant's side, step by step: chargeback alerts compared.
Why chargebacks happen
Every chargeback falls into one of three families. The fixes are different for each. For supplement and skincare brands: chargebacks for supplement brands and chargebacks for skincare brands.
Real fraud
A stolen card is used on your store. The cardholder never saw the order. Fraud rules, 3-D Secure and delivery checks are what stop it.
Friendly fraud
The cardholder did buy, but disputes anyway: they don't recognize the charge, forgot the subscription or regret the purchase. Clarity stops most of it. More in our guide to friendly fraud.
Merchant error
The order arrived late, broken or not at all, a promised refund never came, or the customer was charged twice. Fast support, refunds and clean billing stop it.
Find your own causes first
Before changing anything, pull your last three months of disputes and group them by reason. Every processor shows the reason with each dispute, and each reason points to a different fix.6Stripe Docs, Dispute reason code categories
| Dispute reason | What usually caused it | First fix to look at |
|---|---|---|
| Fraudulent | A stolen card, or a cardholder who doesn't recognize the charge | Fraud screening, 3-D Secure, a recognizable descriptor |
| Unrecognized | The name on the statement doesn't match your store | Statement descriptor and receipts |
| Product not received | NoTracking, a late delivery, or a parcel lost in transit | Tracking, realistic delivery times |
| Product unacceptable | The product didn't match its page, or arrived damaged | Product pages, packaging, returns |
| Subscription canceled | The customer tried to cancel, or forgot they subscribed | Renewal reminders, online cancellation |
| Credit not processed | A refund was promised and not issued, or issued late | Refund process |
| Duplicate | The customer was charged twice | Billing checks |
Practical rule
Fix the reason that brings the most disputes first, then the next one. One cause fixed properly does more than small changes everywhere.
18 ways to prevent chargebacks
Before the order
- Use a statement descriptor customers recognize. Your store name or domain, not your company's legal name. Stripe limits it to 5 to 22 characters.1Stripe Docs, Best practices for preventing fraud Visa also requires the name to make sense next to your category: if it doesn't, add a word that explains what you sell.7Visa, Merchant Data Standards Manual, April 2026
- Describe products exactly. Photos, sizes, materials, quantities and what's in the box, matching what ships. "Not as described" disputes start on the product page.
- Give real delivery times and prices. Show delivery times you can meet, and for international orders, prices in the customer's currency and the countries you ship to.
- Make support easy to reach. A contact link on every page and in every email. A customer who can reach you writes to you, not to their bank.
- Write a return policy people can follow. Timeframes, the condition items must be in, the steps to send them back and when the refund lands. Vague policies leave room for disputes.
Source: Stripe, Best practices for preventing fraud; Visa Merchant Data Standards Manual.
At checkout
- Show your refund and cancellation terms in full, and require agreement. A link alone may not be enough proof that the customer saw them.1Stripe Docs, Best practices for preventing fraud
- Turn on 3-D Secure for risky payments. Authenticated payments shift liability for most fraud disputes to the issuer.1Stripe Docs, Best practices for preventing fraud
- Screen orders before you ship. Check that the IP location matches the addresses, that the email domain is real, that one person isn't behind several accounts or cards, and treat rush shipping on expensive items with care. The full method is in our guide to ecommerce fraud prevention.
- Collect the evidence now. IP address, email, full product description and delivery address on every payment. You'll need them to win a dispute, or to block one before it's filed.
- Capture the payment when you ship. Authorize at checkout, capture when the order leaves. On Stripe, a card authorization can be captured up to 7 days later, and an uncaptured authorization can't be disputed.1Stripe Docs, Best practices for preventing fraud
Stripe: if the checkbox only links to your policy, the issuer may reject it as evidence that the customer saw it.
After the order
- Send a receipt that matches the statement. Same name as the descriptor, the items, the amount and how to reach you.
- Ship with tracking and keep the customer posted. Send the tracking, flag delays before the customer notices them. Keep screenshots of delivery: issuers don't click links.1Stripe Docs, Best practices for preventing fraud
- Answer within a day and refund fast. If you're going to refund, do it before the customer calls the bank. A full refund can't be disputed. A partial one can, for the full amount.1Stripe Docs, Best practices for preventing fraud
- Refund orders you're sure are fraud. You save the dispute fee and keep the dispute off your rate, unless the payment is covered by 3-D Secure.1Stripe Docs, Best practices for preventing fraud
- Check your billing for errors. Double charges, renewals after a cancellation, wrong amounts. A billing bug creates disputes by the dozen.
Stripe suggests delaying physical shipments 24 to 48 hours on risky orders, to give cardholders time to report fraud.
For subscriptions
- Show the recurring terms on their own at sign-up. Amount, frequency, length of any trial and how to cancel, displayed when the customer consents and separately from your general terms.3Visa Core Rules and Visa Product and Service Rules, April 18, 2026
- Remind at least 7 days before a trial or promo ends. Visa requires the amount, the date of the next payments and a simple way to cancel online in that message.3Visa Core Rules and Visa Product and Service Rules, April 18, 2026
- Let customers cancel online. If they signed up online, Visa requires at least an online cancellation option. A customer who can't cancel disputes the next charge.3Visa Core Rules and Visa Product and Service Rules, April 18, 2026
Visa Core Rules and Product and Service Rules, April 2026, tables 5-20 and 5-21, card-absent sales.
Subscriptions: where most disputes start
Recurring billing turns one forgotten click into a dispute every month. Visa's rules lay out what the customer must see at each step.3Visa Core Rules and Visa Product and Service Rules, April 18, 2026
Fig. 1A trial that doesn't end in a dispute
- Sign-upRecurring terms shown separately, customer consents
- ConfirmationIn Europe, within 2 business days
- ReminderAt least 7 days before the trial ends, with amount, date and cancel link
- Recurring chargeOn the dates or intervals agreed
- Cancel onlineRequired when the order was placed online
Visa rules, card-absent
In Europe, Visa adds a reminder when more than 6 months have passed since the last payment, or when the terms change. And if you don't stick to the terms you showed, Visa's rule is to refund the full amount.3Visa Core Rules and Visa Product and Service Rules, April 18, 2026
Billing on a negative option, where customers pay until they cancel, also puts you on Visa's high-risk list: see high-risk MCC codes and our guide to negative option billing.
Inside Tagada
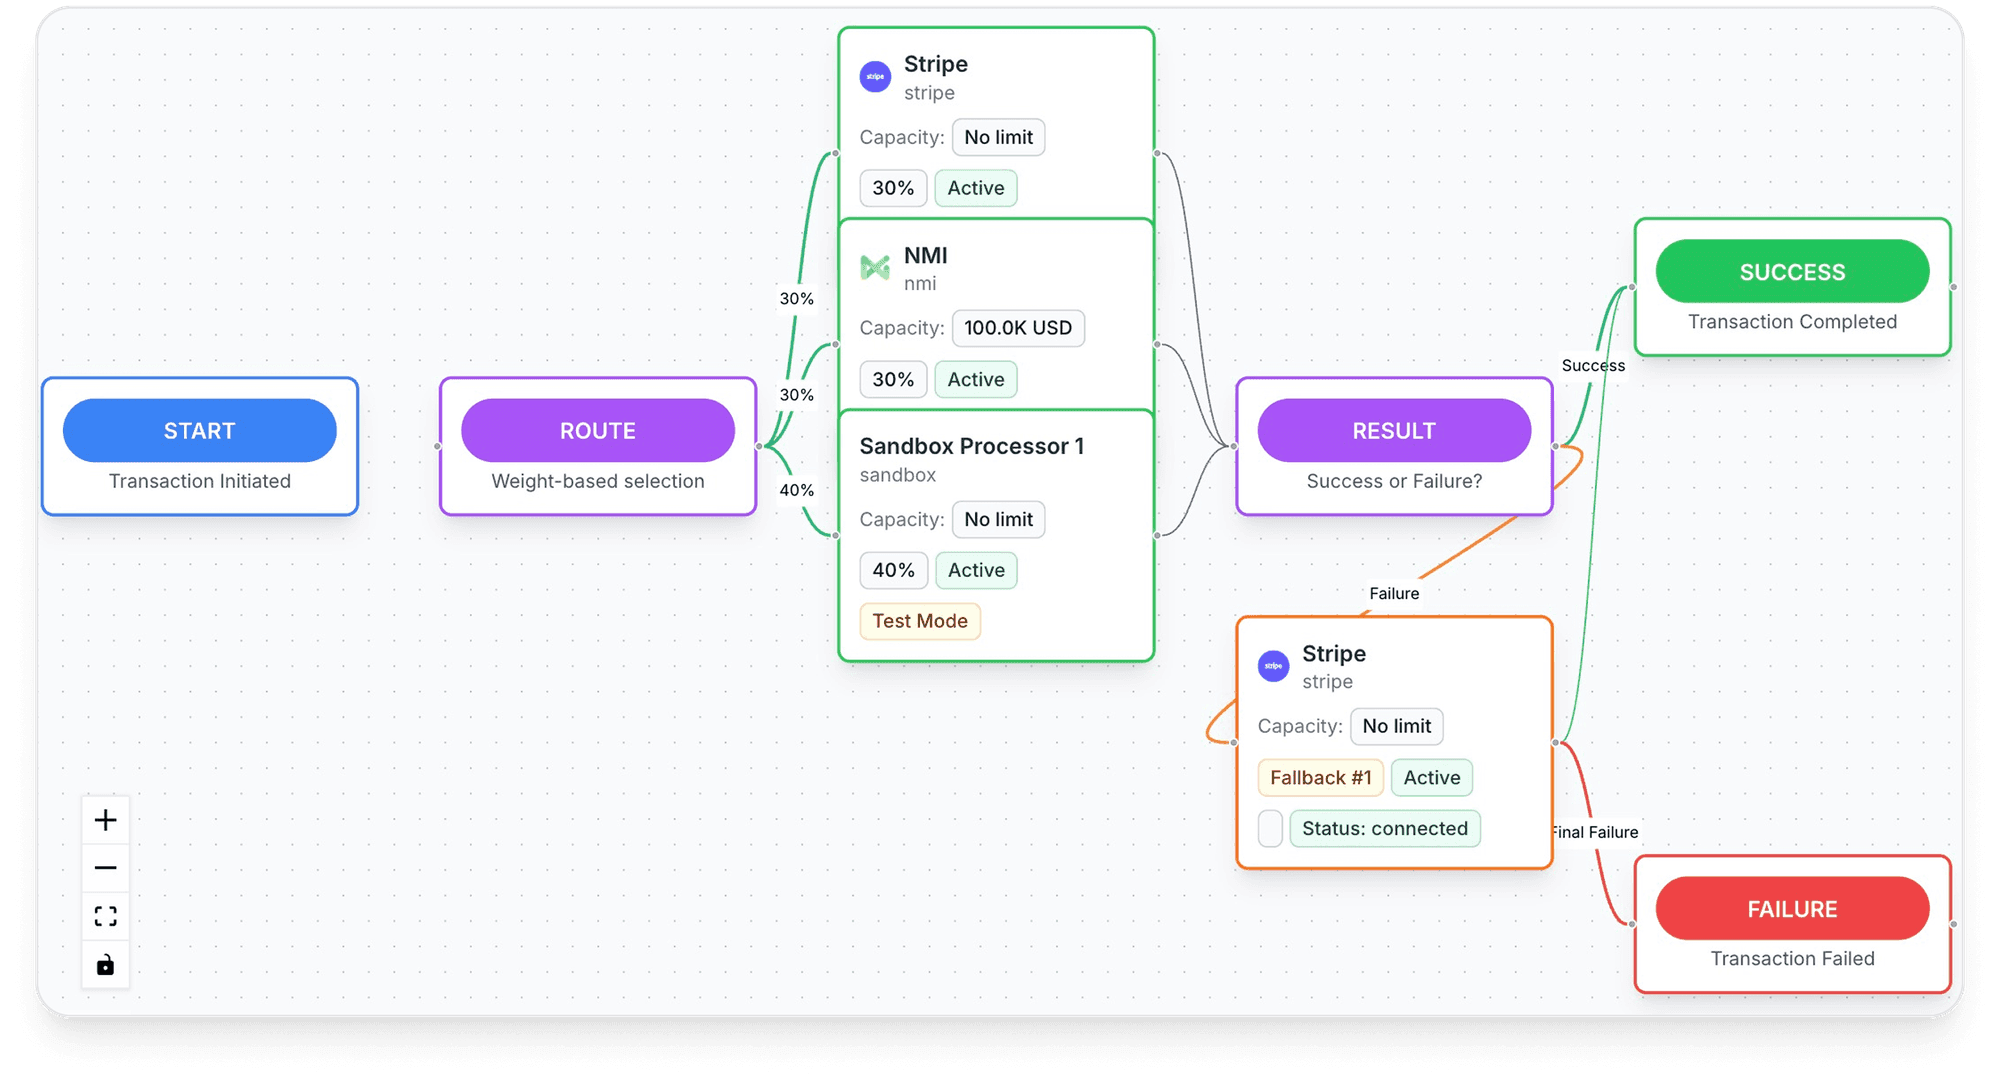
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
Alerts: stop a dispute before it counts
Visa and Mastercard each run tools that reach you between the customer's call to the bank and the chargeback. Stripe and other processors offer them as integrations.2Stripe Docs, How dispute prevention works (Verifi and Ethoca)
| Tool | Network | When it acts | What happens |
|---|---|---|---|
| Order Insight |  Visa (Verifi) | The customer asks the bank about a charge | The bank sees the order details; with Compelling Evidence 3.0, the dispute can be blocked |
| Consumer Clarity |  Mastercard (Ethoca) | The customer asks the bank about a charge | The bank sees the order details, the customer recognizes the charge |
| Rapid Dispute Resolution | Visa (Verifi) | A dispute is filed | Refunded automatically under your rules. Not counted in your dispute rate |
| Ethoca Alerts | Mastercard (Ethoca) | A dispute is filed | Resolved automatically under your rules. Not counted in your dispute rate |
Compelling Evidence 3.0
For a Visa fraud dispute, if you can show at least two earlier undisputed orders from the same cardholder, with matching IP address and a matching email or delivery address, the issuer must block the dispute. That's why step 9 matters.2Stripe Docs, How dispute prevention works (Verifi and Ethoca)
RDR has limits: it doesn't handle partial disputes or payments you've already refunded.2Stripe Docs, How dispute prevention works (Verifi and Ethoca) Set your rules on the disputes you'd refund anyway, such as small fraud claims, and keep the rest for evidence.
Chargeback management: the monthly routine
Prevention lowers the number of disputes. Management handles the ones that remain, and keeps you clear of the card networks' thresholds.
- Count by reason and by network. Visa and Mastercard watch you separately. A spike on one network is a signal on its own.
- Compare with last month. Look for the reason that grew, then for the product, country or traffic source behind it.
- Fix one cause. Change the product page, the descriptor, the reminder email or the fraud rule that the data points to.
- Decide what to fight. Respond when your evidence answers the reason code; accept when the claim holds. See chargeback fees to check whether a case is worth it.
- Answer on time. Usually 7 to 21 days at Stripe. Use our chargeback rebuttal letter template.
- Check your VAMP ratio. Fraud reports plus disputes, divided by settled card-absent transactions.
Once a month, separately for each card network.
When a chargeback still happens
Some will get through. The reason code tells you whether to fight.
- Fraud, card absentStolen card, or a customer who doesn't recognize the chargeRespond if you have 3-D Secure or earlier orders from the same customer
- Product not receivedTracking missing or delivery not confirmedRespond with delivery proof, screenshots included
- Not as describedThe product page promised more than you shippedAccept if the claim holds, fix the page
- Cancelled recurringThe customer tried to cancel, or forgotRespond with consent, reminder and cancellation logs
Once a chargeback is open you can't refund outside it: you accept or you respond.4Stripe Docs, How disputes work See how long a chargeback takes and the difference between a chargeback and a refund.
How to know it's working
Track three numbers every month, by card network.
| Metric | How it's computed | Why it matters |
|---|---|---|
| Dispute rate | Disputes ÷ payments in the period | What your processor watches |
| Visa VAMP ratio | (Fraud reports + disputes) ÷ settled card-absent transactions | What Visa watches. 1.5% is the "Excessive" merchant level in the US, Canada, EU and Asia-Pacific since April 2026 |
| Win rate | Disputes won ÷ disputes answered | Tells you if your evidence is good enough |
The VAMP ratio counts fraud reports as well as disputes, so a store with few chargebacks but many fraud reports can still get flagged. Visa only flags a merchant above 1,500 fraud reports and disputes a month in those regions, and leaves out disputes resolved through pre-dispute services and fraud covered by Compelling Evidence 3.0.5Visa, Visa Acquirer Monitoring Program fact sheet, 2025
How Tagada helps
Payments that follow the card network rules
Tagada follows Visa and Mastercard rules and the laws that apply to payments. TagadaPay runs native 3DS2, device intelligence and a rules engine, and payments route across TagadaPay and processors such as Stripe, NMI and Airwallex, with one logic. See pricing for plans.
Frequently asked questions
What causes chargebacks?
Can you prevent friendly fraud?
What is chargeback management?
Do chargeback alerts count against my dispute rate?
Does 3-D Secure stop chargebacks?
Should I refund instead of fighting a chargeback?
Sources
Checked October 14, 2026- Stripe Docs, Best practices for preventing fraud
- Stripe Docs, How dispute prevention works (Verifi and Ethoca)
- Visa Core Rules and Visa Product and Service Rules, April 18, 2026
- Stripe Docs, How disputes work
- Visa, Visa Acquirer Monitoring Program fact sheet, 2025
- Stripe Docs, Dispute reason code categories
- Visa, Merchant Data Standards Manual, April 2026
TagadaPay
Keep selling while you bring your dispute rate down
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors