Dynamic Currency Conversion Companies: Who Offers DCC, and the Rules
Which companies offer dynamic currency conversion in store and online, how DCC differs from multi-currency pricing, and the Visa and EU rules to follow.


Article summary
TL;DR
Dynamic currency conversion is offered by acquirers and specialists such as Adyen, Fiserv, Planet, Fexco and Worldline, mostly at the terminal, sometimes online. Stripe says it doesn't offer DCC: like Shopify and PayPal, it offers multi-currency pricing instead. Visa requires that DCC stays optional, never preselected, and expressly accepted by the cardholder.
- DCC converts a foreign card's payment into the cardholder's currency at checkout, and the merchant usually earns a share of the markup.
- Multi-currency pricing is different: you show local prices and the customer pays in that currency. Visa's definition says no DCC is conducted.
- DCC is mostly an in-person product. Adyen's DCC works on terminals; Fiserv, Planet and Fexco also list online checkout.
- Visa: DCC must be optional, never preselected, and expressly accepted. If not, the issuer can dispute the full amount under 'Incorrect Currency'.
- In the EU, the markup must be shown as a percentage over the ECB reference rate before the payment, under Regulation 2019/518.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
Dynamic currency conversion (DCC) lets a customer with a foreign card pay in their own currency instead of yours, at a rate set by the merchant's provider. The companies that offer it are mostly acquirers and conversion specialists, and most of them sell it for payment terminals first. Online stores are usually offered something else: multi-currency pricing. Here is who offers which, what it costs, and the rules both have to follow. For supplement and skincare brands: international payments for supplement brands and international payments for skincare brands.
What dynamic currency conversion is (and what it isn't)
With DCC, your price stays in your currency. When a foreign card is used, the terminal or checkout detects that the card's billing currency is different and offers the cardholder a choice: pay in your currency, or pay in theirs at a rate shown on the spot. If they accept, the conversion is done by your side of the transaction, not by their bank. You're still paid in your own currency, and you usually get a share of the conversion margin.5Adyen Docs, Dynamic Currency Conversion (in-person payments)
Multi-currency pricing works the other way round. You show prices in the customer's currency from the first page, and the payment is made in that currency. Visa's rules keep the two apart: a multi-currency pricing transaction is one where the merchant displays prices in a foreign currency and charges in it, and "No Dynamic Currency Conversion is conducted."1Visa Core Rules and Visa Product and Service Rules, April 18, 2026
Fig. 1Same €100 order, two ways to handle a US card
Dynamic currency conversion
- Price shown in EUR€100 on the product page
- Foreign card detectedBilling currency: USD
- Choice offeredPay €100, or the USD amount with rate and markup
The cardholder chooses USD at payment; the provider's markup is in the rate
Multi-currency pricing
- Price shown in USDBased on the customer's location
- Paid in USDCharged in the displayed currency
- Settled in EURYour provider converts for payout
The customer sees and pays a USD price; no choice at the card step
the difference is who converts, and when
The line between the two matters online. Visa says that if an ecommerce merchant uses the cardholder's payment credential to decide whether to convert the price into the cardholder's billing currency, every DCC rule applies.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 Converting because of the card is DCC. Showing a local price because of where the shopper is browsing is pricing.
DCC vs multi-currency pricing at a glance
| Dynamic currency conversion | Multi-currency pricing | |
|---|---|---|
| When the currency changes | At payment, once the foreign card is known | From the first price the customer sees |
| What triggers it | The card's billing currency | The customer's location or chosen market |
| Who sets the rate | The DCC provider, with a markup | Your payment provider, often with a conversion fee |
| Customer's choice | Must be offered and expressly accepted | Must be allowed to pay in your local currency if you show it |
| Who earns on the conversion | The provider, usually sharing the markup with you | The payment provider |
| Typical setting | Terminals in hotels, airports, tourist retail | Online stores selling abroad |
| Examples | Adyen, Fiserv, Planet, Fexco, Worldline | Stripe Adaptive Pricing, Shopify Markets, PayPal |
Verdict
If you sell online, you are almost always choosing a multi-currency pricing setup, not a DCC provider. DCC is a terminal product first, and the few online versions carry the same Visa obligations as in store.
Which companies offer dynamic currency conversion?
The list below comes only from each company's own pages, read on October 14, 2026. It isn't a ranking: none of these companies publishes a DCC markup or merchant share, so there is nothing to rank them on. What changes between them is the channel and how you get access.
| Company | Channels it lists | Currencies it states | How you earn | How you get it |
|---|---|---|---|---|
 Adyen | In person (Terminal API or standalone terminals) | About 60 | A share of the markup, settled with your payment | Switched on through an existing Adyen integration |
| Fiserv (Carat) | Retail, ecommerce, MOTO, ATM and mobile | More than 70 | Revenue share on converted transactions | Through your Fiserv sales contact |
| Planet | In person (retail, hospitality, airlines, parking) and online | More than 135 | "Passive income", no terms published | Directly from Planet |
| Fexco | Point of sale and online checkout | Not stated | Not stated | Through acquirers on the Visa Acceptance Platform |
| Worldline (Greece page) | Point-of-sale terminals | 24 | The DCC commission | Activated on new terminals, Visa and Mastercard cards issued outside the euro area |
| Stripe | Not offered | n/a | n/a | Offers Adaptive Pricing instead |
What each provider says, in detail:
- Adyen. DCC is documented for in-person payments only, on contact chip and contactless Visa, Mastercard and Maestro cards. It isn't available in Brazil, and a surcharge and DCC can't be applied to the same transaction. Funds settle in your settlement currency at the pre-conversion amount, and your share of the markup shows as a credit in the settlement reports.5Adyen Docs, Dynamic Currency Conversion (in-person payments) Adyen's product page says 30% of shoppers offered DCC accept it; that is Adyen's own figure.6Adyen, Dynamic Currency Conversion product page
- Fiserv (Carat). Its 2023 product sheet lists DCC for retail, ecommerce, MOTO, ATM and mobile, funding in the merchant's local currency "at a guaranteed exchange rate from the time of transaction", and a separate Multicurrency Pricing product.7Fiserv Carat, Dynamic Currency Conversion product sheet, October 2023
- Planet. It lists in-person and online payments, more than 135 currencies, and a "Best Rate Guarantee": if the card issuer's rate was better on another transaction that day, Planet says it refunds the difference up to 150%.8Planet, Dynamic Currency Conversion (DCC) The Datatrans gateway documents online DCC using Planet's exchange rates, with a conversion screen shown only when the card is eligible.9Datatrans Docs, Dynamic Currency Conversion
- Fexco. Since March 2026, Fexco says its DCC is available through the Visa Acceptance Platform and the Cybersource gateway, for acquirers already connected to it, "at point of sale or online checkout".10Fexco, Fexco and Visa Partner to Enhance Global Access to Dynamic Currency Conversion, March 25, 2026
- Worldline. Its Greek page lists 24 currencies, no access cost, automatic activation on new terminals, and a commission for the merchant.11Worldline (Greece), Dynamic Currency Conversion
Check with your acquirer first
DCC runs on the acquiring side. If your acquirer doesn't support it, a specialist usually can't plug in on its own: Fexco, for example, reaches merchants through acquirers. Ask your current acquirer before you shortlist anyone else.
Who offers multi-currency pricing instead
Stripe is direct about it: "Stripe doesn't offer dynamic currency conversion."3Stripe, Dynamic currency conversion: how it works, how to handle it and how Stripe can help Shopify and PayPal don't sell DCC either. All three offer ways to charge customers in their own currency, with different costs and different people paying them.
Stripe Adaptive Pricing
Shows prices in the local currency in more than 150 countries, on Checkout and Payment Links (always on for Payment Links). Stripe says it uses machine learning to pick the presentment currency. You pay 0%; the customer pays a 2 to 4% fee built into the rate, unless they pay in your currency. The rate is guaranteed for 24 hours.
Shopify Markets
Prices convert automatically at market rates, or at a manual rate with Managed Markets. Full functionality needs Shopify Payments. The merchant is charged a conversion fee of 1.5% for US stores and 2% elsewhere, and Shopify includes it in the customer's price.
PayPal
When a payment needs converting, PayPal's US fee page lists a 3% currency conversion spread, charged to the merchant on top of its transaction fees.15PayPal, Merchant and business fees (US), updated October 1, 2026
A few limits from the Stripe documentation: Adaptive Pricing isn't available for businesses using Elements with the Payment Intents API, nor for Indian businesses, nor with manual capture. Your price currency must be one of your settlement currencies. Refunds use the same exchange rate as the original payment, so the customer gets back exactly what they paid. For cross-border subscriptions, it supports cards, Link, Apple Pay and Google Pay only.4Stripe Docs, Adaptive Pricing (read October 14, 2026)
Adaptive Pricing is a different setup from charging a customer yourself in a currency you don't settle in. In that case, Stripe's US pricing adds 1% for currency conversion to the merchant's fee.14Stripe, Pricing (United States), October 2026 At Shopify, the conversion fee applies whether rates are automatic or manual; refunds and chargebacks don't add a new conversion fee, but the original fee isn't returned.12Shopify Help Center, International pricing fees and costs13Shopify Help Center, Currency conversion and exchange rates The full fee comparison is in our guide to transaction fees.
Which providers offer both DCC and multi-currency pricing?
Among the official pages we read, Fiserv is the one that lists both side by side: Dynamic Currency Conversion and a Multicurrency Pricing product where you "select your currencies, set pricing and manage the customer experience."7Fiserv Carat, Dynamic Currency Conversion product sheet, October 2023 Adyen, Planet and Worldline document DCC; Stripe, Shopify and PayPal document local-currency pricing. Large acquirers may offer both under contract, but if it isn't on their public pages, ask for it in writing.
Choosing both is common in omnichannel businesses: DCC on terminals for travelers, local pricing online for customers abroad. Visa's rules apply to each one separately. For multi-currency pricing, if you display your local currency, the customer must be allowed to pay in it, with no extra requirement and no preselected currency that pushes them toward the foreign one.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026
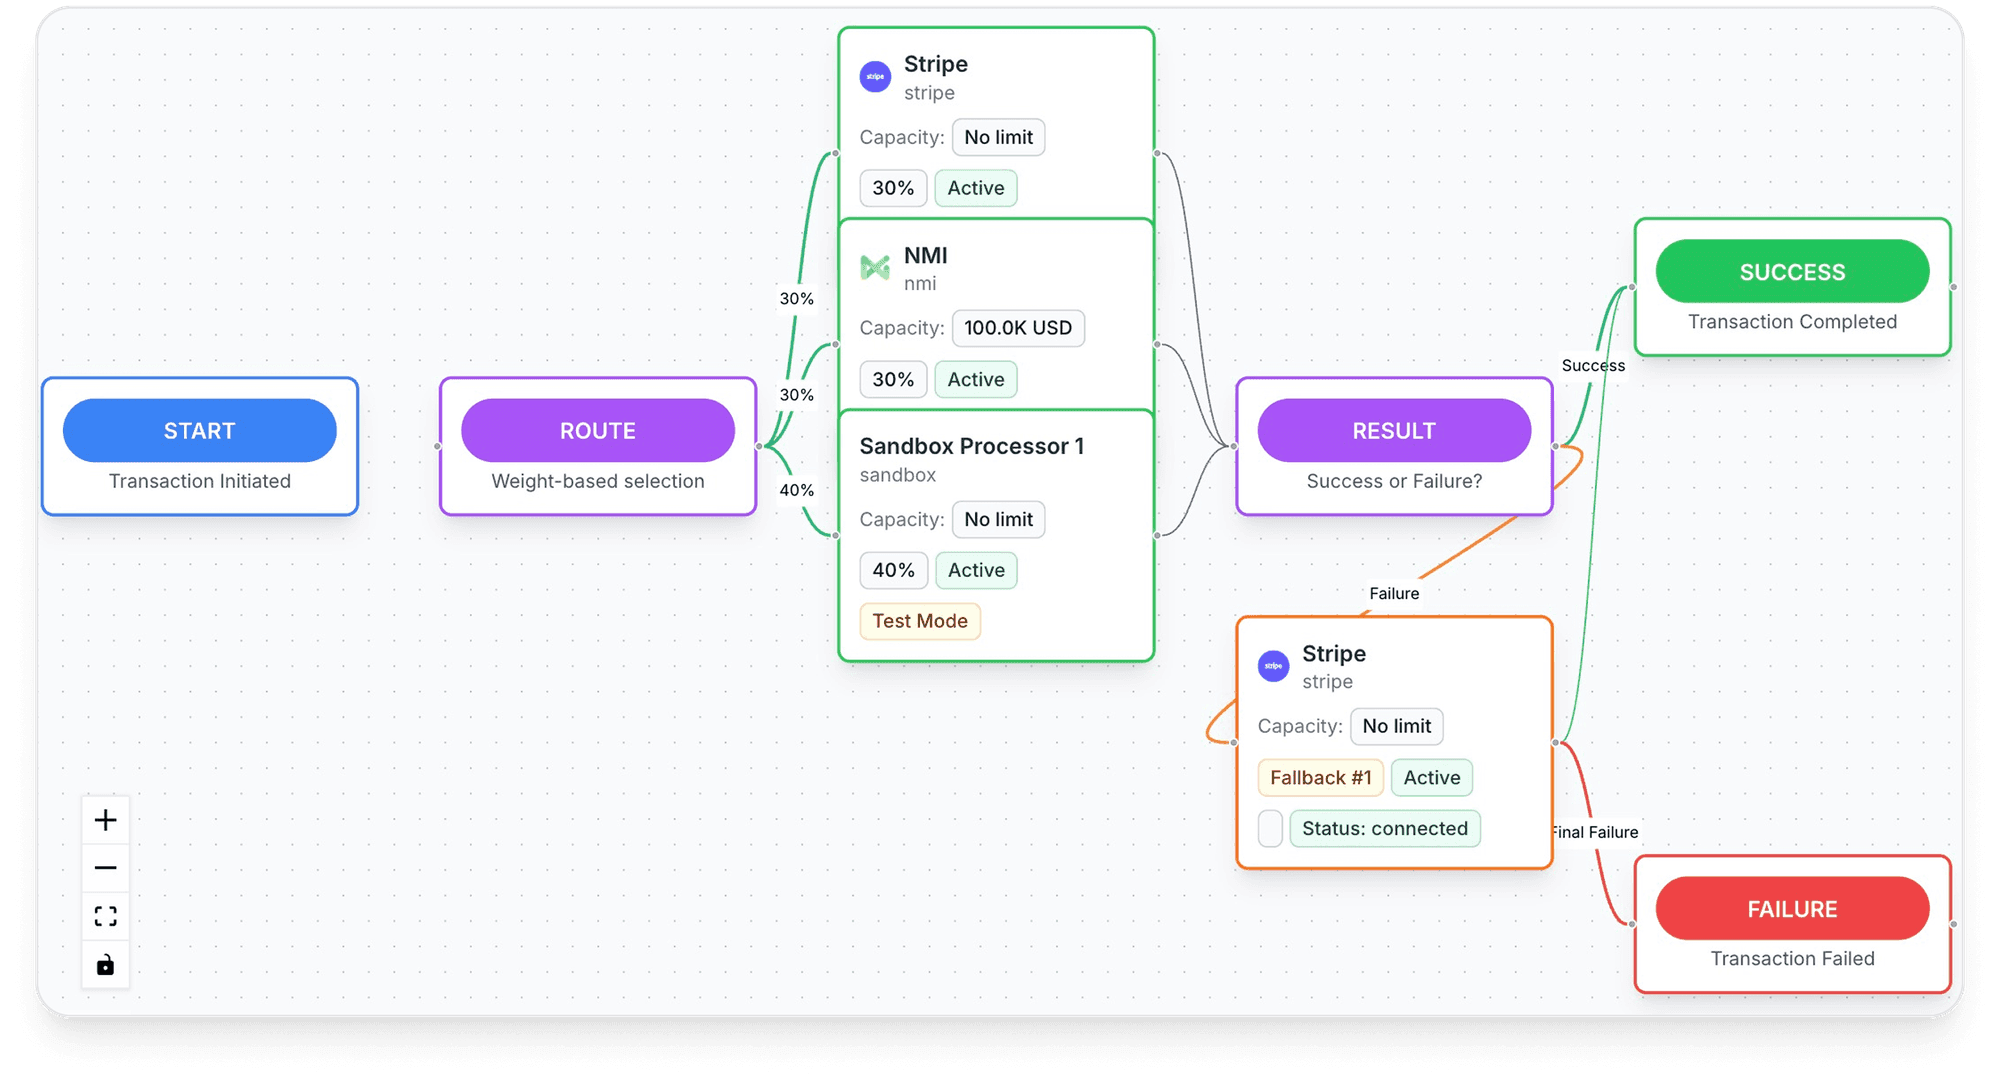
Inside Tagada
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
Is there AI-driven dynamic currency conversion?
Many questions about DCC now ask which provider "uses AI". Among the official pages reviewed for this guide, only Stripe mentions it, and not for DCC: Adaptive Pricing uses machine learning to determine the most relevant presentment currency, and Stripe sets its customer fee within the 2 to 4% range "for the purposes of increasing customer conversion".4Stripe Docs, Adaptive Pricing (read October 14, 2026) No DCC provider page we read describes AI setting the rate or the offer.
The rules put a limit on any automation. The DCC choice belongs to the cardholder: no language or procedure, like a preselected option, that makes DCC the default.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 And Visa already has rules for AI agents that shop on behalf of a cardholder:
For an Agentic Transaction containing a Merchant's offer of Dynamic Currency Conversion (DCC) or Multi-Currency Pricing (MCP), either: provide the details displayed by the Merchant […] and obtain Cardholder consent before initiating the Transaction; at the time of capturing the Cardholder's payment instructions, obtain consent to complete the Transaction without additional acknowledgement.
Visa's rules for DCC
Before an acquirer processes any DCC transaction, it must be registered and certified under Visa's DCC Guide, and every outlet offering DCC must follow the Visa Rules. DCC may not be offered on cards enabled with the Visa Multi-Currency Solution or on travel prepaid cards.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 For the merchant, the rules are these:
- Say it's optional. Inform the cardholder that DCC is optional, and use no language or procedure, such as preselecting DCC, that makes it the default.
- Get an express yes. The cardholder must expressly agree. In person, the details are shown on a customer-facing screen or handheld device, and the cardholder accepts on it directly.
- Offer the billing currency. DCC is offered in the cardholder's billing currency, not another one.
- Don't make local currency harder. No extra requirement for paying in your local currency.
- Don't convert afterwards. An amount approved in local currency can't be converted into another currency after the sale.
- Don't call it Visa's. Your DCC service can't be presented as a Visa service.
Source: Visa Core Rules, April 18, 2026, section 5.8.9.2. The Australian surcharge rule is left out.
A receipt is required for every DCC transaction. It must show the amount in your local currency and in the transaction currency, the conversion rate, the commission, fees or markup over a wholesale or government-mandated rate, a statement that the cardholder was offered a choice of currencies and expressly agreed, and a statement that the conversion was done by the merchant.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 Adyen's own receipts add the rate source and an acceptance statement.5Adyen Docs, Dynamic Currency Conversion (in-person payments)
Breaking these rules has a cost on both sides of the acquiring contract:
- DCC applied without an express yes, or local currency refusedThe issuer can open a dispute under condition 12.3, Incorrect CurrencyThe dispute covers the entire transaction amount
- The acquirer can't prove the cardholder agreedIt can only re-present in local currency, before conversionDCC fees and commission are excluded from the amount
- Pre-arbitration on a DCC caseThe amount is cappedLimited to the difference between what was charged and what should have been
- Visa audit finds a DCC violationThe acquirer is assessedUp to USD 10,000 or USD 50,000, plus Visa's general schedule
Visa assesses the acquirer, which is responsible for making sure every outlet offering DCC follows the rules.1Visa Core Rules and Visa Product and Service Rules, April 18, 2026 A currency dispute also counts like any other chargeback in your dispute rate: see our guide to chargeback prevention.
EU rules: Regulation 2019/518
In the EU, currency conversion at the point of sale has its own disclosure law. Regulation (EU) 2019/518 added an Article 3a to Regulation 924/2009 on card payments. Its first four paragraphs apply since April 19, 2020.2Regulation (EU) 2019/518 amending Regulation (EC) No 924/2009 (currency conversion charges)
| What must be disclosed | When | Who |
|---|---|---|
| Total conversion charges as a percentage markup over the latest ECB euro reference rates | Before the payment is initiated | Payment providers and parties offering conversion at an ATM or point of sale |
| The amount in the payee's currency and in the currency of the payer's account | Before the payment is initiated | The party offering conversion at an ATM or point of sale |
| That the payer can pay in the payee's currency and let their own bank convert | Before the payment is initiated | The same party |
| The markup and both amounts on a durable medium | After the payment is initiated | The same party |
The regulation also asks the cardholder's own bank to send an electronic message with its markup when a card is used in another EU currency, and requires all this information to be free and neutral.2Regulation (EU) 2019/518 amending Regulation (EC) No 924/2009 (currency conversion charges) For a DCC provider, it means two references on the screen: Visa's rules on choice, and an EU markup measured against the ECB rate.
Is DCC worth it for a merchant?
The business case is a share of a margin the cardholder pays, set against trust and disputes.
What providers put forward
- A share of the conversion markup on every accepted conversion (Adyen, Fiserv, Worldline)
- Payment in your own currency, at a rate fixed at the time of the sale (Fiserv, Adyen)
- No need to set prices in several currencies, since the conversion happens at payment (Fiserv)
- An amount the traveler recognizes, matching their statement (Fiserv)
What it costs you
- A higher price for the cardholder: the markup is the source of your share
- A dispute right for the full amount if the choice wasn't clear (Visa 12.3)
- Disclosure work on the terminal, the checkout and the receipt, plus the EU markup format
- No DCC on Visa Multi-Currency Solution cards or travel prepaid cards
DCC fits places where many foreign cards are used in person: hotels, airports, tourist retail, attractions, which are the sectors Adyen and Planet target.6Adyen, Dynamic Currency Conversion product page8Planet, Dynamic Currency Conversion (DCC) For an online store that sells abroad, local prices from the first page usually solve the real problem, a customer who doesn't know what they will pay, and they also open local payment methods that only work in one currency, like iDEAL in euros.4Stripe Docs, Adaptive Pricing (read October 14, 2026) The wider choice of wallets and bank payments is covered in our guide to alternative payment methods.
How to build a shortlist of DCC or currency providers
Treasury and payment teams usually compare on six questions. The answers are rarely on public pages, so ask for them in writing.
| Question | Why it matters | Where to look |
|---|---|---|
| DCC, local pricing, or both? | They are different products under different Visa rules | Your channels: terminals, online, payment links |
| Which channels are covered? | Many DCC products are terminal-only | Provider docs (Adyen documents in-person only) |
| Who sets the markup, and what is your share? | It's the whole business case, and the customer's cost | Your contract; no provider we read publishes it |
| How are you paid? | Settlement currency and rate guarantee decide your FX risk | Settlement reports, funding terms |
| How are refunds and chargebacks converted? | Rate changes can create gains or losses | Provider docs (Stripe Adaptive Pricing refunds at the original rate) |
| Who handles disclosure and receipts? | Visa and EU rules apply to every DCC sale | Terminal screens, checkout screens, receipt templates |
For payment links, Stripe's Adaptive Pricing is always on for Payment Links, so customers abroad see a local price without extra setup.4Stripe Docs, Adaptive Pricing (read October 14, 2026) For terminals, start with your acquirer: if it offers DCC, the integration is often a setting rather than a project, as Adyen describes.6Adyen, Dynamic Currency Conversion product page
How Tagada helps
Several processors behind one checkout
Tagada runs the checkout, with one-click upsells, order bumps, A/B tests, Apple Pay and Google Pay. Payments route across TagadaPay and processors such as Stripe, NMI and Airwallex, with one logic and a cascade to another processor when one is down or times out, and 3D Secure 2 is native. A card vault lets you switch processors without re-onboarding customers, and subscriptions keep charging. Tagada doesn't list a DCC product of its own: currency options depend on the processors you connect. Pricing is on the pricing page. Tagada follows Visa and Mastercard rules and the laws that apply to payments.
Whatever you choose, the test is the same: the customer sees both amounts, the markup, and a real choice, before they pay. A conversion that only works when customers don't notice it will come back as a dispute.
Frequently asked questions
Which platform offers dynamic currency conversion for merchants?
Does Stripe offer dynamic currency conversion?
Does Adyen offer DCC for online payments?
What is the difference between DCC and multi-currency pricing?
Which payment processor uses AI for dynamic currency conversion?
Who pays the markup on a DCC transaction?
Sources
Checked October 14, 2026- Visa Core Rules and Visa Product and Service Rules, April 18, 2026
- Regulation (EU) 2019/518 amending Regulation (EC) No 924/2009 (currency conversion charges)
- Stripe, Dynamic currency conversion: how it works, how to handle it and how Stripe can help
- Stripe Docs, Adaptive Pricing (read October 14, 2026)
- Adyen Docs, Dynamic Currency Conversion (in-person payments)
- Adyen, Dynamic Currency Conversion product page
- Fiserv Carat, Dynamic Currency Conversion product sheet, October 2023
- Planet, Dynamic Currency Conversion (DCC)
- Datatrans Docs, Dynamic Currency Conversion
- Fexco, Fexco and Visa Partner to Enhance Global Access to Dynamic Currency Conversion, March 25, 2026
- Worldline (Greece), Dynamic Currency Conversion
- Shopify Help Center, International pricing fees and costs
- Shopify Help Center, Currency conversion and exchange rates
- Stripe, Pricing (United States), October 2026
- PayPal, Merchant and business fees (US), updated October 1, 2026
TagadaPay
Selling across borders? Keep more than one processor ready
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors