Return Item Chargeback: A Bounced Deposit, Not a Dispute
A return item chargeback is a bank fee on a bounced deposited check, not a card dispute. Who pays it, and how its online cousin, the ACH return, works.
Article summary
TL;DR
A return item chargeback is what your bank does when a check you deposited bounces: it takes back the credit it gave you and usually charges a fee. It's not a card chargeback. No customer dispute, no card network, nothing to contest. For an online store, the version that matters is the ACH return.
- A return item chargeback hits the person or business that deposited a bad check, not the one who wrote it.
- The word comes from banking law: a bank may charge back a provisional credit when the item isn't paid.
- Online, the equivalent is an ACH return: a bank debit sent back with a return code such as R01 or R10.
- An ACH dispute on a personal account can come up to 60 days after the debit, and you can't contest it through the ACH network.
- Nacha watches three return rates: 0.5% unauthorized, 3% administrative, 15% overall.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
A return item chargeback has nothing to do with a customer returning an item, and almost nothing to do with card chargebacks. It's a banking term for a deposited check that bounces. If you sell online and saw the phrase on a statement or in a report, here is what it means, and the bank-payment version that does concern ecommerce: the ACH return.
What is a return item chargeback?
A return item chargeback is the reversal your bank makes when a check you deposited is returned unpaid. When you deposit a check, the bank credits your account before it has collected the money. That credit is provisional. If the payer's bank refuses the check, your bank takes the credit back and usually adds a fee.
The word "chargeback" comes from banking law, long before card disputes. The Uniform Commercial Code gives a collecting bank the right to "charge back" a provisional credit when the item isn't paid, and to return the item to its customer.1Uniform Commercial Code § 4-214, Right of charge-back or refund (Cornell LII)
Fig. 1How a deposited check becomes a return item chargeback
- You deposit a checkFrom a customer or a client
- Provisional creditThe bank credits you before collecting
- Check refusedInsufficient funds, closed account, stop payment
- Charge backThe credit is removed from your account
- FeeCharged to you, the depositor
The depositor pays, not the check writer
Banks don't agree on a name. On a fee schedule or a statement, look for:
- Returned deposited item
- Deposited item returned (unpaid)
- Cashed item returned
- Returned check or rejected check fee
- Chargeback, or chargeback check
Return item chargeback vs card chargeback vs NSF fee
Three different events share the vocabulary. The difference is who starts it and who pays.
| Return item chargeback | NSF fee | Card chargeback | |
|---|---|---|---|
| What happened | A check you deposited bounced | A check or debit you wrote couldn't be paid | A cardholder disputed a payment with their card issuer |
| Who starts it | Your bank, when the check is refused | The payer's bank | The customer, through their card issuer |
| Who pays | The depositor | The person who wrote the check | The merchant: the amount plus a dispute fee |
| Card network involved | None | None | Visa, Mastercard and others |
| Can you contest it | Not a dispute. Ask your bank about the fee | Not a dispute. Ask your bank about the fee | With evidence, through your processor |
| Counts in your dispute rate | Not counted | Not counted | Counted from the day it's filed |
Verdict
If your report says "return item chargeback", look at the payment method before anything else. A bounced check is a cash collection problem. A card chargeback is a dispute with a deadline. They don't go through the same workflow.
Card chargebacks are covered in our guides to chargeback vs refund and chargeback fees.
Who pays a return item chargeback, and how much?
The depositor pays. The person who wrote the check deals with their own bank, which may charge them an insufficient funds fee. If a customer pays you with a check that bounces, you're the depositor: you lose the credit and pay the fee.
The lost credit
The check amount leaves your balance. You still have to collect the money from the person who wrote the check.
The bank fee
Set by your bank, per item. The amount and the name change from one fee schedule to the next, and business accounts have their own schedule.
The follow-up
Contacting the payer, asking for another payment method, correcting your books. Often the part nobody budgets for.
There's no dispute to file. You can ask the bank to waive the fee. For consumer accounts, the CFPB said in 2022 that charging this fee on every returned check, whatever the circumstances, is likely unfair: the depositor usually can't know whether the check writer has the funds.2CFPB Bulletin 2022-06, Unfair returned deposited item fee assessment practices
Why online stores rarely see one
A return item chargeback needs a paper check deposited at a bank. Most direct-to-consumer brands never take one. Where it still shows up: wholesale orders paid by check, B2B invoices, and a check from a retail partner. If you take bank payments online, what you'll see instead is an ACH return.
The online version: ACH returns
When a customer pays your store from their bank account, the payment usually runs on ACH Direct Debit. Like a deposited check, it isn't guaranteed: at Stripe, it takes up to 4 business days to learn whether the payment succeeded or failed.3Stripe Docs, ACH Direct Debit payments When the customer's bank refuses the debit, it sends it back with a return code. That's an ACH return, and if the funds were already in your balance, Stripe removes them right away.3Stripe Docs, ACH Direct Debit payments
Fig. 2Where an ACH debit can come back
approved declined or closed routing step
- CheckoutCustomer links a bank account and accepts the mandate
- sent to the customer's bankACH debit sentUp to 4 business days to confirm
- if the bank refusesReturn codeR01, R02, R10... the funds come back outDeclined
Not guaranteed until it settles
The return code tells you why and what you're allowed to do next. These are the ones an online store sees most.8Stripe, How to reduce ACH payment failures
| Code | What it means | What to do |
|---|---|---|
| R01 | Insufficient funds | You may retry. Nacha limits reinitiation to two times |
| R09 | Uncollected funds | Same as R01: a retry is allowed |
| R02 | Account closed | Ask the customer for another account or payment method |
| R03 | Account not found, or no account | Check the details, then ask the customer |
| R04 | Invalid account number | Usually a typing error. Verify the account before the next debit |
| R08 | Payment stopped | The customer stopped this debit. Contact them before anything else |
| R16 | Account frozen | Don't retry. Ask for another payment method |
| R07 | Authorization revoked | Stop debiting on this authorization |
| R10 | Customer says the debit wasn't authorized | Don't retry. A new debit needs a new authorization |
| R11 | Debit not in line with the authorization (wrong amount, too early) | Correct the error and send a new debit within 60 days of the return |
| R29 | Business customer says the debit wasn't authorized | Don't retry without a new authorization |
R05, R07, R10, R11, R29 and R51 count as unauthorized returns in Nacha's monitoring.5Nacha, Differentiating Unauthorized Return Reasons4Nacha, ACH Network Risk and Enforcement Topics R11 joined that group when Nacha split unauthorized returns between "not authorized" (R10) and "authorized, but the debit was wrong" (R11).5Nacha, Differentiating Unauthorized Return Reasons
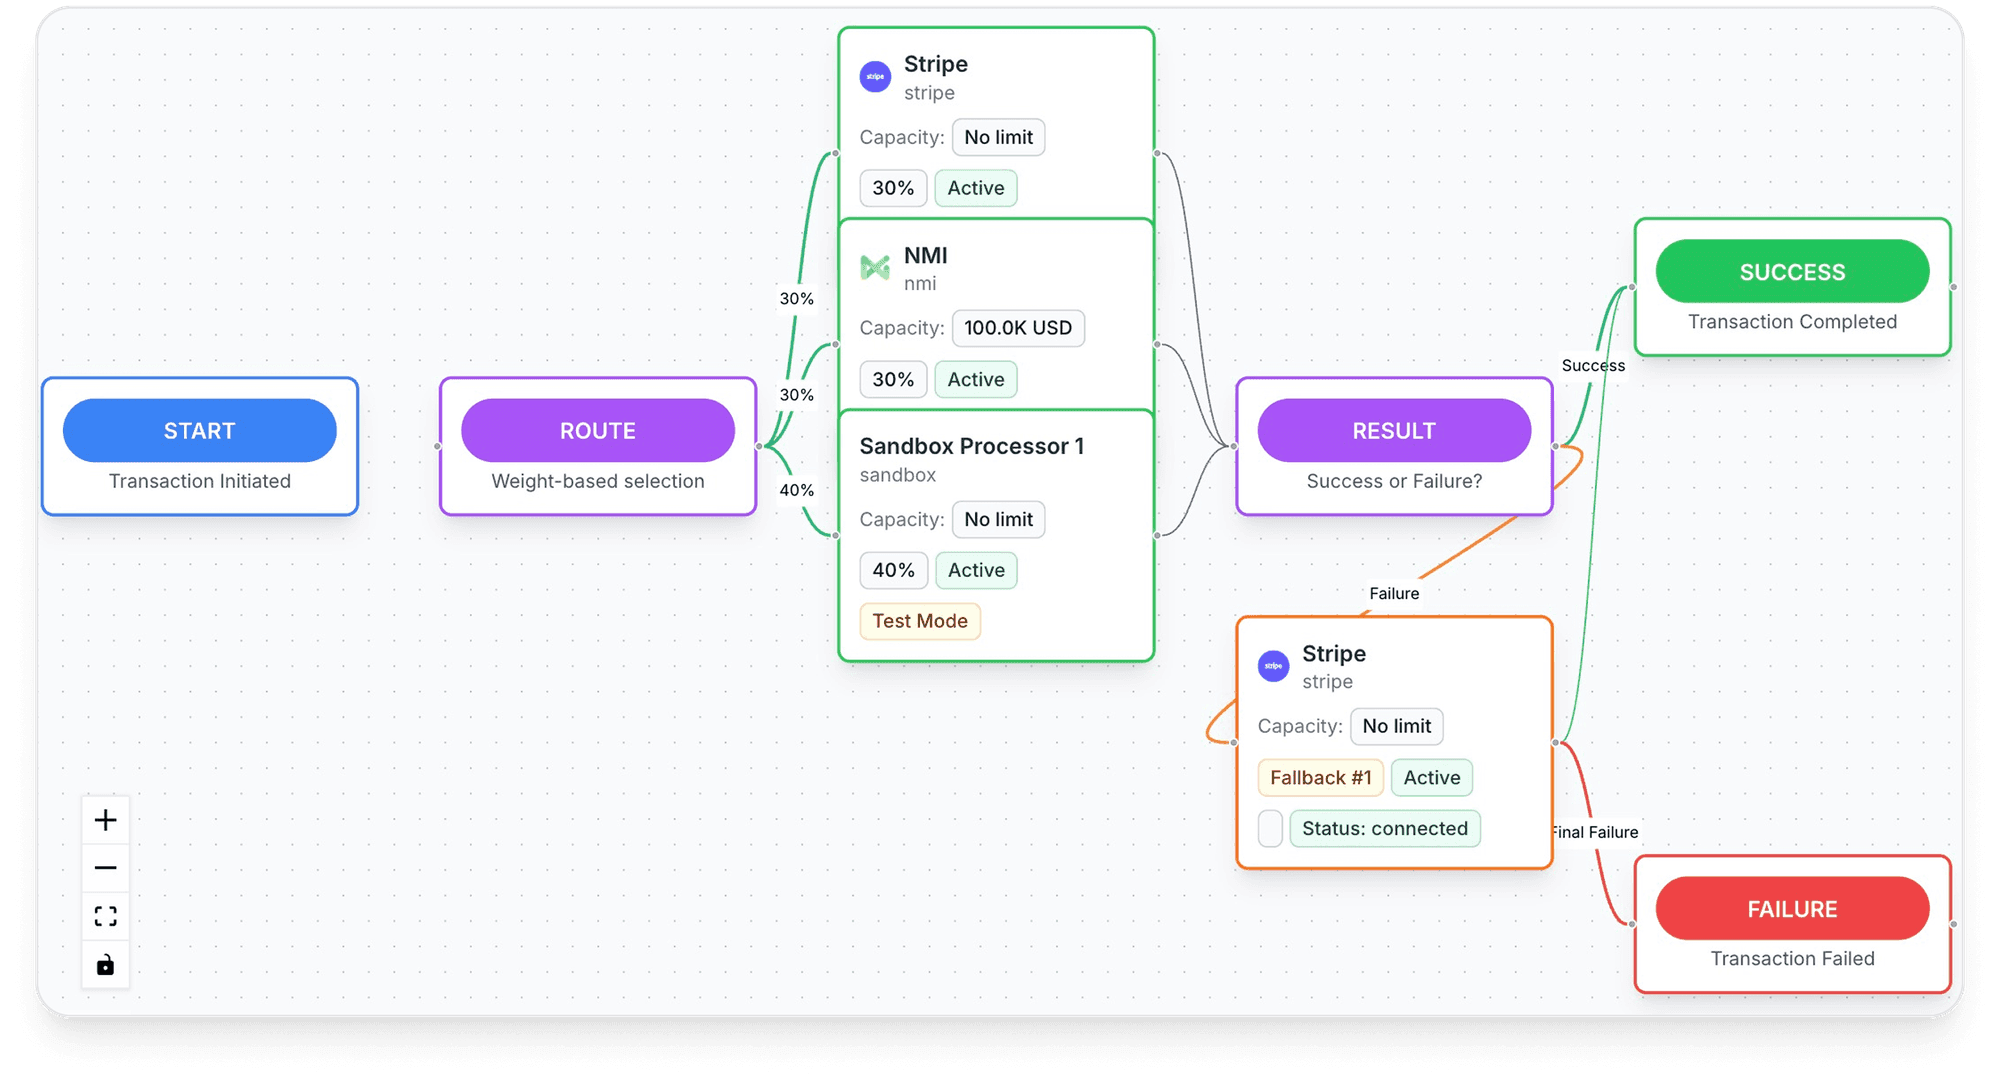
Inside Tagada
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
ACH return, ACH dispute and card chargeback: what you can contest
An ACH dispute is a return the customer starts: they tell their bank the debit wasn't authorized, was revoked, or didn't match what they agreed to. Stripe shows it as a dispute. The rules are much harder on the merchant than for cards.3Stripe Docs, ACH Direct Debit payments
Card chargeback
- Customer disputesUsually within 120 days
- You respondEvidence through your processor
You can respond with evidence, and win the money back
ACH dispute
- Customer disputesUp to 60 days, personal account
- Funds come back outThe mandate becomes invalid
Final: no evidence, no appeal through the ACH network
What Stripe's ACH documentation says, point by point:3Stripe Docs, ACH Direct Debit payments
- Timing. Customers can generally dispute an ACH debit for up to 60 calendar days after the debit on a personal account, and up to two business days on a business account.
- Final. Disputes received within those windows can't be contested through the ACH network. You can't submit evidence. Contact the customer directly.
- Late returns. In rare cases a dispute arrives after the window. The banks decide, and the customer's bank may ask for proof of authorization. With Stripe-hosted mandates, Stripe answers with the mandate. With custom mandates, you upload it, once, before the deadline.
- The fee. Stripe doesn't refund the dispute fee.
- The mandate. A dispute invalidates the authorization. To charge the customer again, settle the issue with them and collect a new mandate. A second dispute and Stripe blocks the bank account.
- Late failures. If the bank returns a payment for insufficient funds or bad account details after it showed as succeeded, Stripe creates a dispute with that reason and charges a failure fee.
Refunding doesn't stop an ACH dispute
On cards, an open dispute blocks a separate refund. On ACH, it doesn't: if you refund while the customer's bank processes a dispute, the customer can be credited twice. Stripe's advice is to tell the customer you're refunding, and how long it takes, so they don't go to their bank too.3Stripe Docs, ACH Direct Debit payments
What to do when an ACH payment comes back
- Hold the order. If it hasn't shipped, wait. If it has, it's now a collection case.
- Read the return code. It decides your options: retry, correct, or ask for another payment method.
- Retry only funds returns. After R01 or R09, you can reinitiate, up to two times. The retry keeps the same company name, company ID and amount, with "RETRY PYMT" in the entry description.6Nacha, Minor Rules Topics (reinitiation limited to two times)4Nacha, ACH Network Risk and Enforcement Topics Stripe's automatic retries follow the same limit: at most 2, within 40 days of the first attempt.3Stripe Docs, ACH Direct Debit payments
- Correct and resend after R11. Fix the amount or the date, and send a new debit within 60 days of the return, without a new authorization.5Nacha, Differentiating Unauthorized Return Reasons
- Stop after R07, R10 or R29. Contact the customer. You need a new authorization before any new debit.4Nacha, ACH Network Risk and Enforcement Topics
- Book it as what it is. A return is not a refund and not a card chargeback. Keep it in its own line so your dispute rate and your cash stay readable.
Never retry a debit returned as unauthorized without a new authorization: Nacha treats it as an improper reinitiation.
If the mistake is yours, you can send a reversal instead of waiting for a return. Nacha allows it for a duplicate, the wrong receiver, the wrong amount, or a debit dated earlier than intended, within 5 banking days of the settlement date. A reversal for any other reason is improper.7Nacha, Reversals and Enforcement
Nacha return rate limits
Nacha watches every business that sends ACH debits. Your rates are computed over the last 60 days or two calendar months: returned debits divided by debits sent.4Nacha, ACH Network Risk and Enforcement Topics
0.5%
Unauthorized return rate threshold: R05, R07, R10, R11, R29 and R51
3%
Administrative return rate level: R02, R03 and R04, closed or wrong accounts
15%
Overall return rate level: all debit returns, whatever the reason
The 0.5% is a threshold with enforcement behind it. The 3% and 15% levels start an inquiry by Nacha, not an automatic fine.4Nacha, ACH Network Risk and Enforcement Topics5Nacha, Differentiating Unauthorized Return Reasons In practice, your processor or bank sees the problem first: Stripe can block a customer's bank account after certain returns until the issue is resolved.3Stripe Docs, ACH Direct Debit payments
How to prevent ACH returns and disputes
Most returns come from three things: an account that doesn't exist or is empty, a customer who doesn't recognize the debit, and a customer who forgot they agreed to it.
- Account details typed by handR03 and R04 returns, a few days after checkoutVerify the account: instant bank login, or microdeposits
- The customer doesn't recognize the debitAn R10 dispute, final on personal accountsUse a statement descriptor that matches your store name, within 16 characters
- No proof of what the customer agreed toNothing to show on a late returnDisplay the mandate at checkout and email a copy, as Nacha requires
- Recurring debit changes dateA surprised customer goes to the bankGive at least 7 calendar days' notice before changing the timing
- You refund without telling the customerRefund plus dispute: paid twiceTell them the refund is on its way and when it lands
These points all come from Stripe's ACH documentation.3Stripe Docs, ACH Direct Debit payments The broader ACH setup, credit vs debit, settlement windows and costs, is in our ACH payment processing guide. For card disputes, start with chargeback prevention.
For a store, the safest setup treats bank debits as one payment method among several, never the only one. When an ACH debit comes back, the customer can pay by card in the same checkout instead of disappearing. That's the logic behind Tagada: one checkout connected to several processors, with the customer, the subscription and the payment history in one place.
How Tagada helps
Payments that follow the card network rules
Tagada follows Visa and Mastercard rules and the laws that apply to payments. TagadaPay runs native 3DS2, device intelligence and a rules engine, and payments route across TagadaPay and processors such as Stripe, NMI and Airwallex, with one logic. See pricing for plans.
Frequently asked questions
What is a return item chargeback fee?
Is a return item chargeback the same as a credit card chargeback?
Who pays a return item chargeback?
Can I get a return item chargeback fee waived?
Can a merchant contest an ACH return or ACH dispute?
How long does a customer have to dispute an ACH debit?
Sources
Checked October 14, 2026- Uniform Commercial Code § 4-214, Right of charge-back or refund (Cornell LII)
- CFPB Bulletin 2022-06, Unfair returned deposited item fee assessment practices
- Stripe Docs, ACH Direct Debit payments
- Nacha, ACH Network Risk and Enforcement Topics
- Nacha, Differentiating Unauthorized Return Reasons
- Nacha, Minor Rules Topics (reinitiation limited to two times)
- Nacha, Reversals and Enforcement
- Stripe, How to reduce ACH payment failures
TagadaPay
Taking bank payments? Keep cards and a backup processor in the same checkout
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors