
How to Write a Chargeback Rebuttal Letter (With Template)
A chargeback rebuttal letter template for each dispute reason, a filled-in example, the evidence to attach, and the submission rules banks actually apply.
Article summary
TL;DR
A chargeback rebuttal letter tells the card issuer why the chargeback is wrong and points to the evidence that proves it. Keep it to one page: the case reference, one sentence on why you contest, the facts in order, and a numbered list of attached exhibits. Match the argument to the dispute reason.
- One letter per dispute, matched to its reason: fraud, not received, not as described, subscription, credit, duplicate.
- State the facts, then list the exhibits. The evidence wins the case, not the wording.
- You get one submission. Stripe forwards it at once and you can't add anything after.
- No links, audio or video: banks don't open them. Send screenshots and PDFs.
- At Stripe, files must stay under 4.5 MB in total, and 19 pages for Mastercard.
 ChatGPT
 Claude
 Perplexity
 Grok
On this page
A chargeback rebuttal letter is the cover page of your response to a dispute. The bank reads it to understand your case, then checks the evidence behind it. Pick the dispute reason below to get a letter you can fill in and the exhibits to attach, then read on for a filled-in example and the mistakes that lose cases.
Rebuttal letter builder
What does the dispute say?
Re: Chargeback [case ID], reason "Fraudulent", amount [amount], payment of [date]

To the card issuer,

We are contesting this chargeback. The cardholder, or someone they authorized, made this purchase.

Order: [order number], placed on [date] by [customer name] for [product], [amount], card ending [last 4].

The payment was made by the cardholder: [one or two sentences, facts only, in the order they happened].

The attached evidence shows it:
  Exhibit A: Billing and shipping address matching the card
  Exhibit B: Delivery confirmation to that address
  Exhibit C: IP address and device of the order
  Exhibit D: Earlier undisputed orders from the same customer
  Exhibit E: 3-D Secure result, if the payment was authenticated

We ask that the chargeback be reversed and the funds returned.

[Name], [role], [store name], [support email]
Replace every [bracket]. Attach the exhibits as images or PDF: banks don't open links, audio or video.
What goes in a rebuttal letter
- The case reference. Dispute ID, reason, amount, payment date. The bank must find the case in seconds.
- Why you contest, in one sentence. "The cardholder made this purchase." "The order was delivered." The sentence matches the dispute reason.
- The facts, in order. Order, payment, delivery or use, contact with the customer. No opinions, no blame.
- The exhibits. A numbered list, each with what it proves: "Exhibit A: tracking showing delivery on March 3."
- The request. Reverse the chargeback and return the funds.
Keep it to one page. The detail belongs in the exhibits.
One letter, one reason
Generic letters lose. A fraud dispute and a "not as described" dispute need different arguments and different evidence. Read the reason before you write a word, and read the customer's own claim if your processor shows it.1Stripe Docs, Respond to disputes
A filled-in example
A customer disputes a $64 order as "Product not received". The tracking shows delivery. Here is the letter, filled in.
- Re
- Chargeback DP-48211, reason Product not received, $64.00, payment of March 1
- Why we contest
- The order was delivered to the address the customer entered at checkout.
- Facts
- Order 10482 placed March 1 by J. Cooper, shipped March 2 with UPS, delivered March 4, no contact from the customer before the dispute.
- Exhibit A
- Order confirmation with the shipping address
- Exhibit B
- UPS tracking page, screenshot, showing delivery on March 4 to that address
- Exhibit C
- Shipping label with the full address
- Request
- Reverse the chargeback and return the funds.
Names, numbers and dates are made up for the example.
Three things make this letter work: the reason is answered in the first sentence, every fact has a date, and every exhibit says what it proves.
The evidence for each dispute reason
What you need to prove depends on the reason the bank gives. A refund you already issued settles any of them.2Stripe Docs, Dispute reason code categories
| Dispute reason | What you must show | Evidence that shows it |
|---|---|---|
| Fraudulent | The cardholder, or someone they authorized, made the payment | Matching billing and delivery address, IP and device, 3-D Secure, earlier undisputed orders |
| Product not received | It was delivered, or isn't due yet | Tracking with delivery confirmation, promised delivery date |
| Not as described | It matched its description and wasn't defective | Product page at the time of purchase, photos, messages |
| Subscription canceled | The subscription was active and the customer didn't follow your cancellation process | Terms accepted at sign-up, renewal reminder, use after the claimed cancellation |
| Credit not processed | The refund was issued, or isn't owed | Refund confirmation, or the policy shown at checkout |
| Duplicate | Each payment was for something different | Both orders, with what each covered |
| Unrecognized | The cardholder made the payment | Same as fraud, plus the receipt showing your descriptor |
Strong and weak evidence for a fraud dispute
Fraud disputes are the hardest to win, and the evidence that works is specific. Stripe's guidance for physical products lists what issuers accept.2Stripe Docs, Dispute reason code categories
Evidence that wins
- Delivery to an address that matches a billing address verified by the card's address check
- A link between the person who received the goods and the cardholder, such as an email or photo
- Proof the purchase was made by a member of the cardholder's household
- Earlier payments on the same card that weren't disputed
- A 3-D Secure authentication on the payment
- For recurring payments, the contract, earlier undisputed payments and proof the customer still uses the product
Evidence that doesn't
- A link to a tracking page: banks don't click links
- A long letter with no attachment behind each claim
- Delivery to an address that wasn't verified and isn't the cardholder's
- A video or an audio recording
- "Please call us for more information"
Fraud on Visa: Compelling Evidence 3.0
If you can show at least two earlier undisputed orders from the same cardholder, with matching IP address and a matching email or delivery address, Visa's Compelling Evidence 3.0 rules weigh heavily in your favor. Stripe flags eligible disputes and pre-fills the fields: don't edit them.1Stripe Docs, Respond to disputes
Inside Tagada
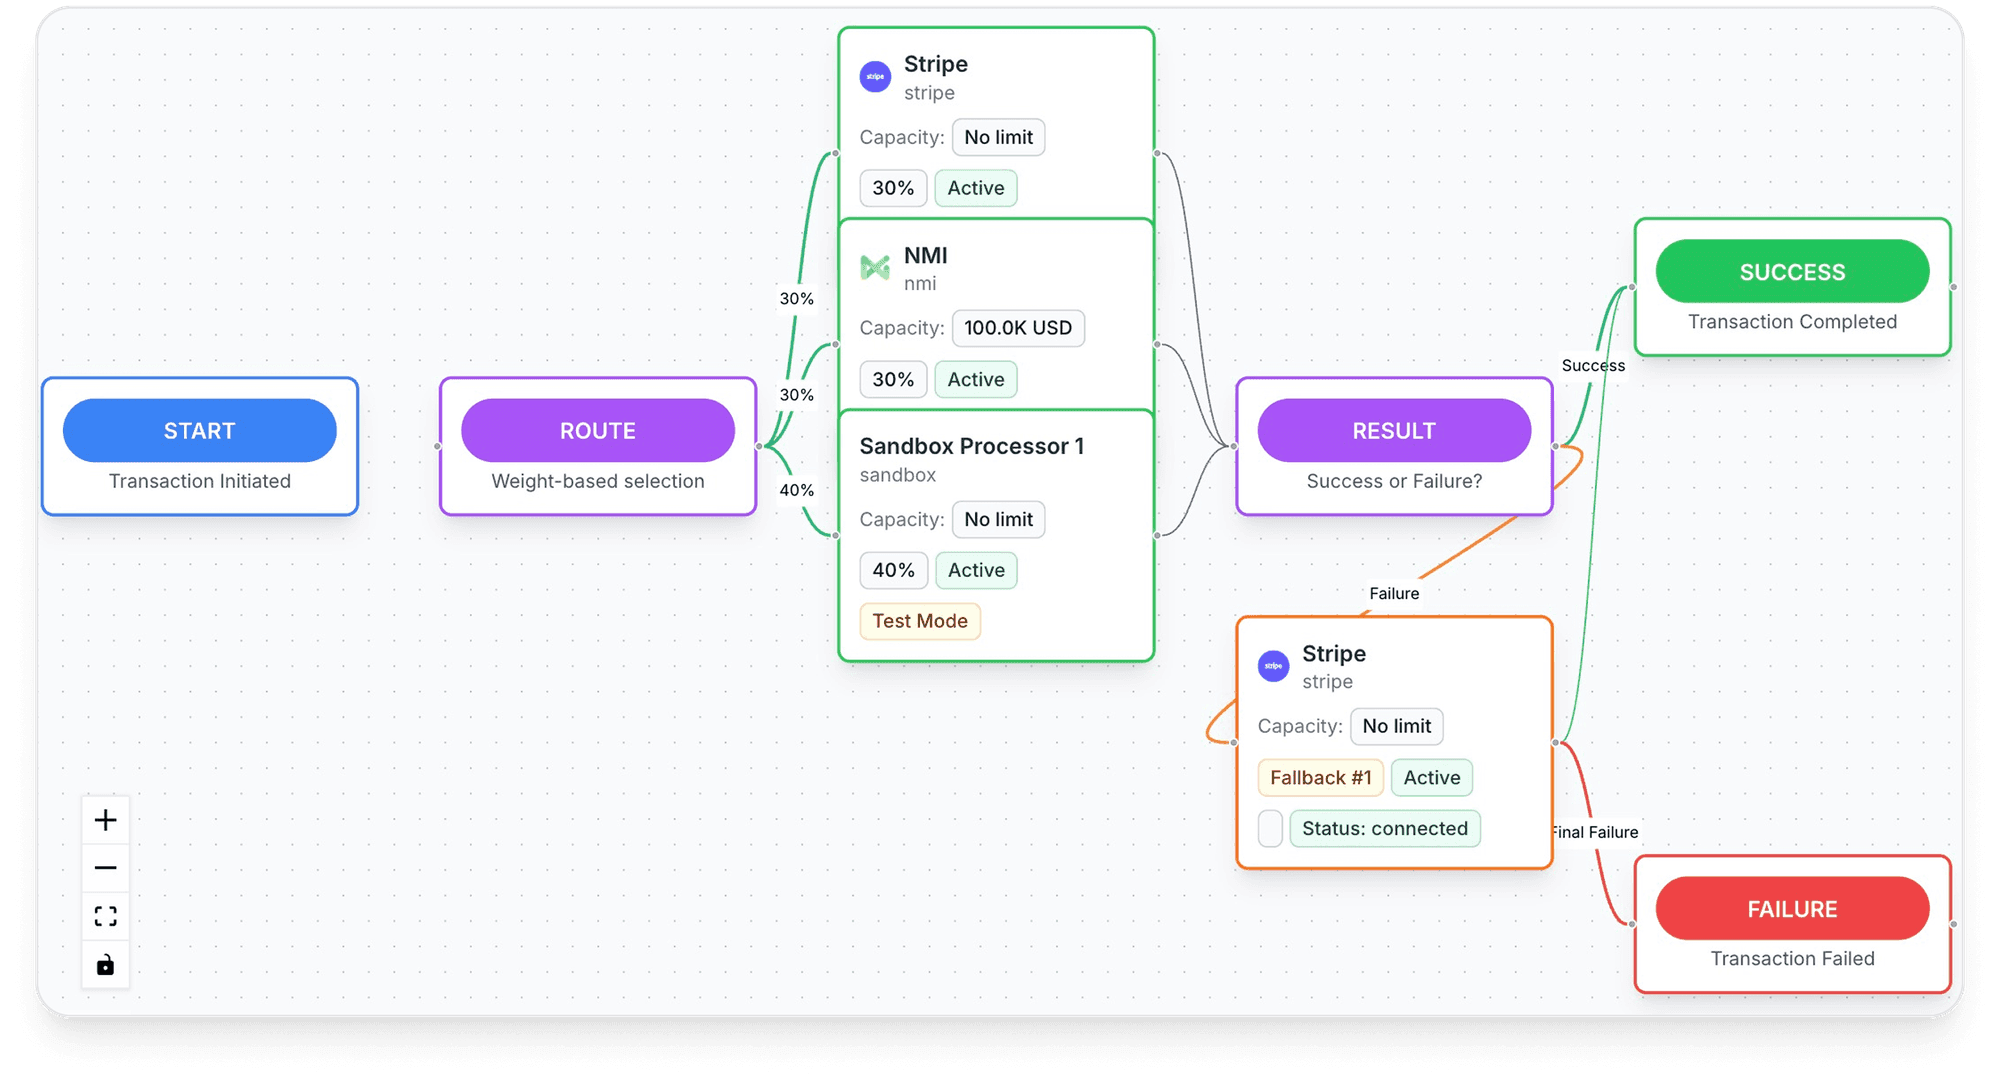
See every payment's route, processor by processor
Set the order your processors are tried in, per store, per country or per product.
Rules your submission must follow
The best letter loses if the bank can't read the evidence. Stripe's rules are a good baseline for any processor.1Stripe Docs, Respond to disputes
- One submission onlyStripe sends it to the bank at once, no edits, no extra filesGather everything before you click submit
- One file per type of evidenceSeveral documents of the same kind must be combinedMerge them into one multi-page PDF
- No links, audio or videoBanks don't open external contentScreenshot tracking pages and messages
- 4.5 MB in total, 19 pages for MastercardLarger files can't be sentCompress images before uploading
- 7 to 21 days to respondMiss it and the dispute is lostStart the file the day the dispute arrives
Mistakes that lose winnable cases
Answering the wrong reason
Proving delivery on a fraud dispute doesn't prove the cardholder ordered. Answer the reason on the dispute, not the one you expected.
Missing the deadline
At Stripe, no response before the deadline means the dispute is lost automatically.
Ignoring a withdrawal
A customer who says they withdrew the dispute isn't enough. At Stripe, you still have to submit evidence for it to close in your favor.
Editing pre-filled fields
On Compelling Evidence 3.0 cases, changing the data Stripe filled in can break eligibility.
After you submit
The dispute moves to "under review" and the bank decides, usually within 60 to 75 days.4Stripe Docs, How disputes work You're told the outcome by email and in your dashboard: won, and the amount comes back, or lost, and the decision is final. The full timeline is in our guide to how long a chargeback takes.
When not to send a rebuttal
Answering costs time, and at Stripe a second fee, returned only if you win. Skip it when the customer's claim holds: a parcel that never arrived, a product that didn't match its page, a cancellation you didn't honor. Accept, fix the cause, and see chargeback fees for a quick way to check whether a case is worth answering.
The better fix is upstream: most disputes you'd lose can be avoided with the steps in our guide on how to prevent chargebacks, or settled with a refund before the bank is involved. See chargeback vs refund.
How Tagada helps
Payments that follow the card network rules
Tagada follows Visa and Mastercard rules and the laws that apply to payments. TagadaPay runs native 3DS2, device intelligence and a rules engine, and payments route across Stripe, Adyen and TagadaPay with one logic. See pricing for plans.
Frequently asked questions
What is a chargeback rebuttal letter?
How long should a rebuttal letter be?
What evidence wins a chargeback?
Can I send more evidence after submitting?
The customer says they withdrew the dispute. Do I still need to respond?
Should I respond to every chargeback?
Sources
Checked October 14, 2026TagadaPay
Fewer disputes to answer starts at checkout
Tell us what you sell and how you sell it. Each application is underwritten, and approval is not guaranteed.
- 01Tell us what you sell and how
- 02Underwriting reviews your business
- 03Process through TagadaPay alongside your other processors